AI agents for business finance: what they can and can't do
What AI agents can do in bookkeeping, close, collections and compliance today, where a person must stay in charge, and how to judge a product.
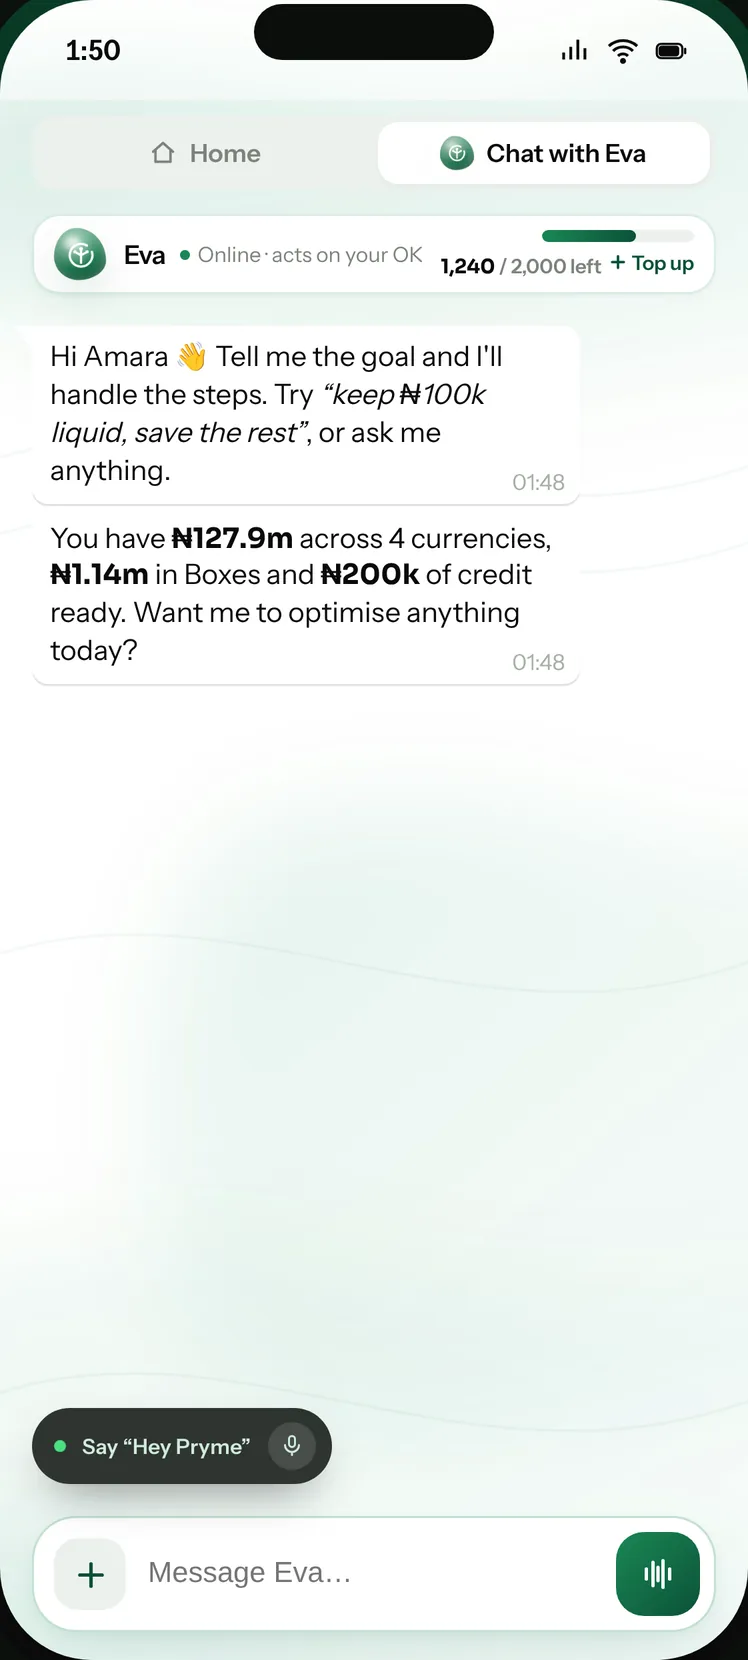
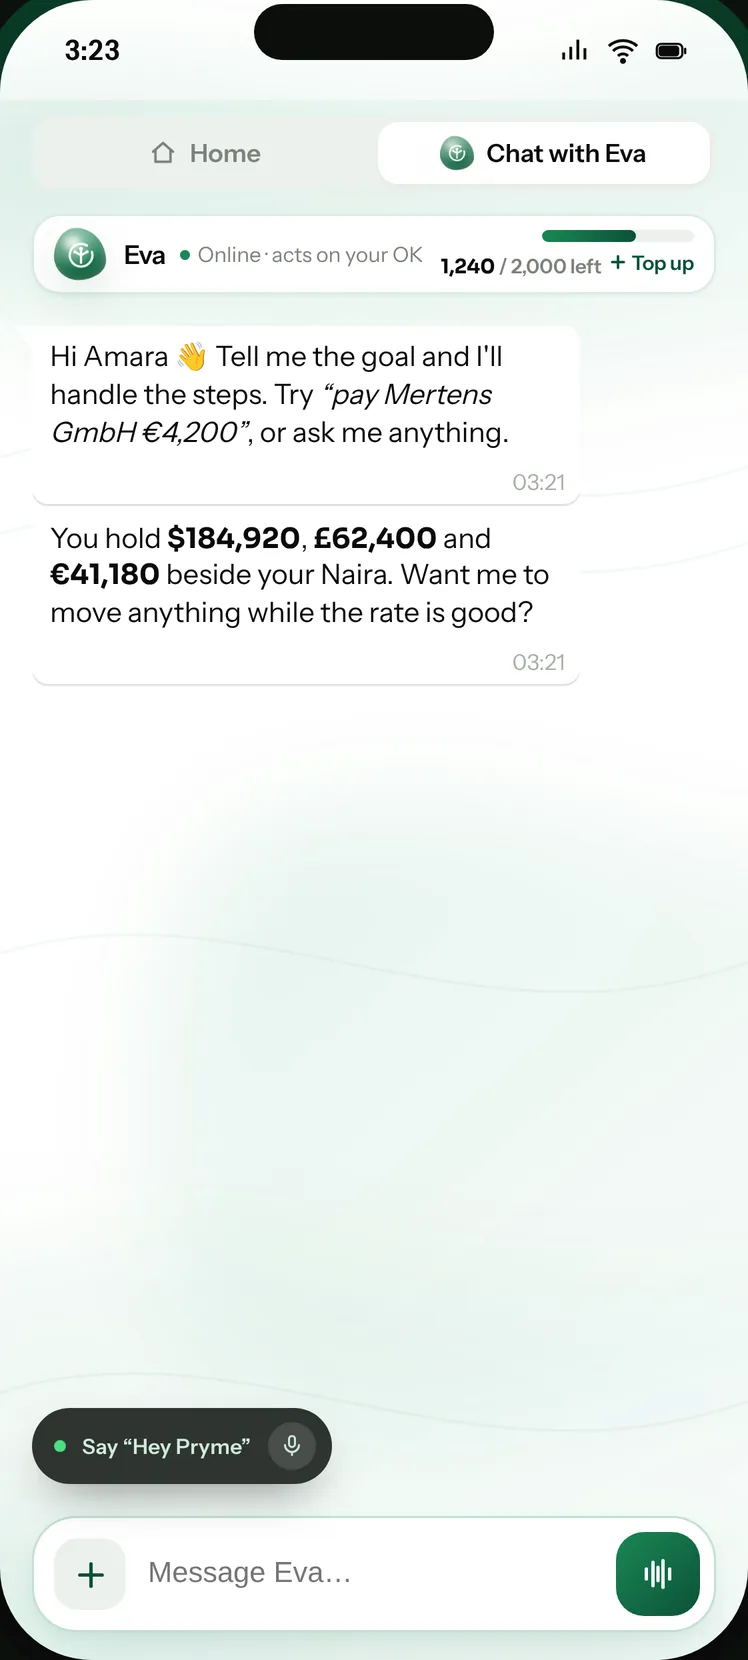
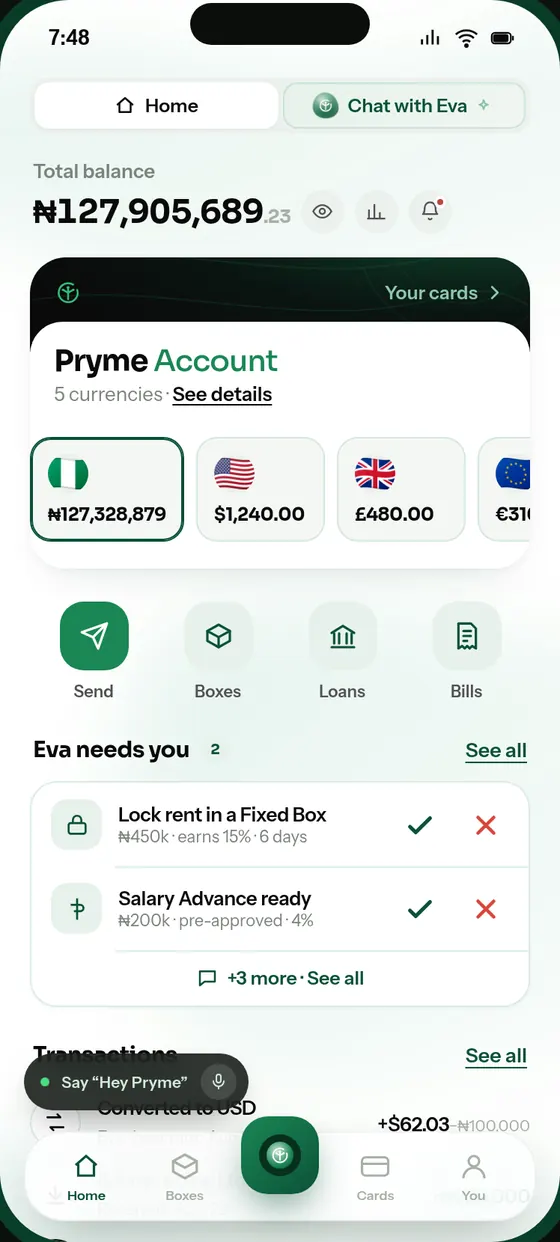
Meet Eva, the assistant inside the Pryme app. She opens accounts, moves money, saves toward your goals and follows up. Nothing leaves your account without your approval.
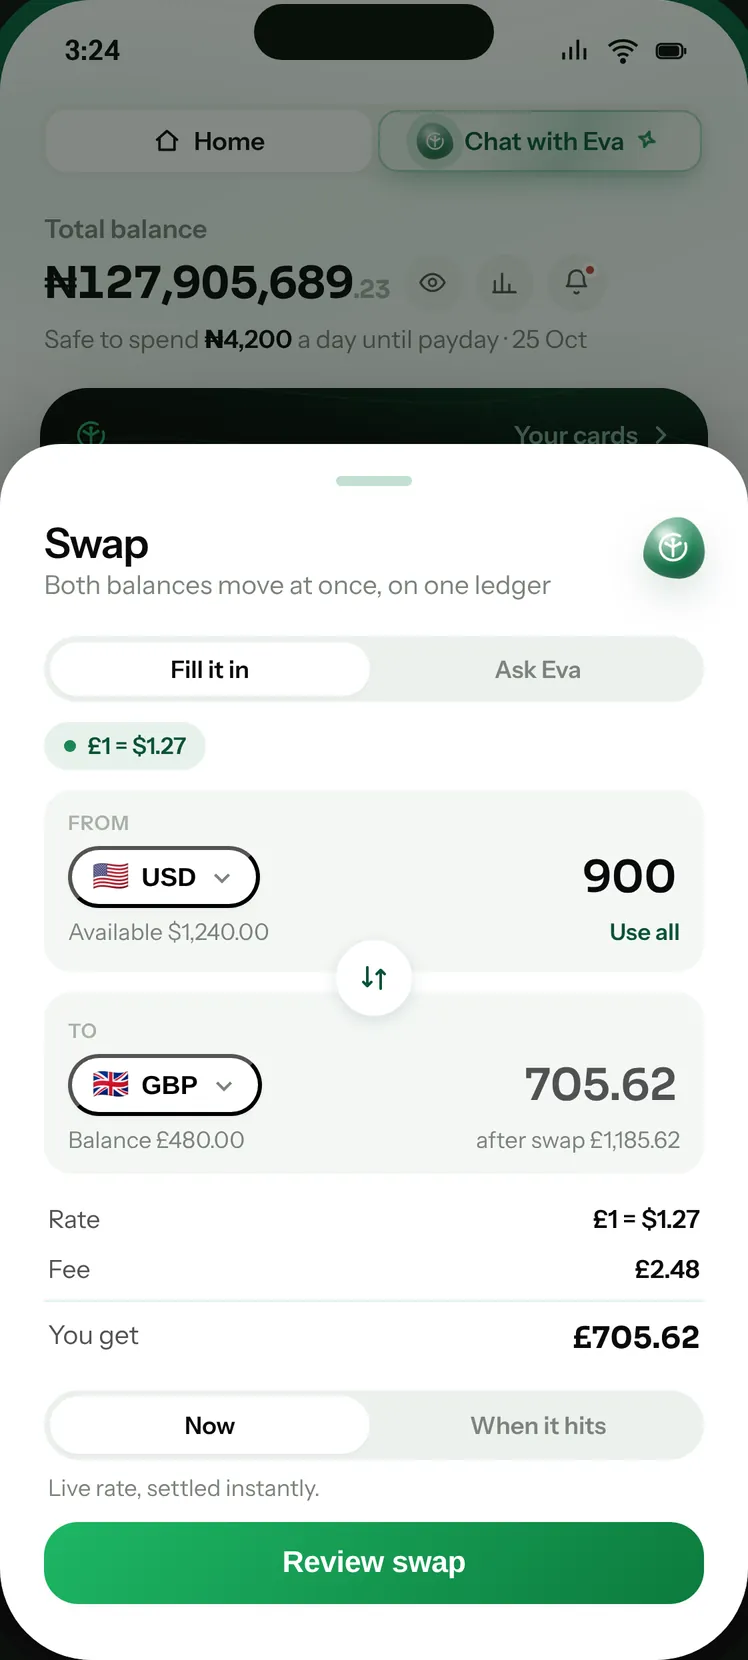
Meet Eva, the assistant inside the Pryme app. She holds dollars, pounds, euros and Naira side by side, swaps at a locked rate, pays bills in any of them and sends anywhere, asking before anything moves.
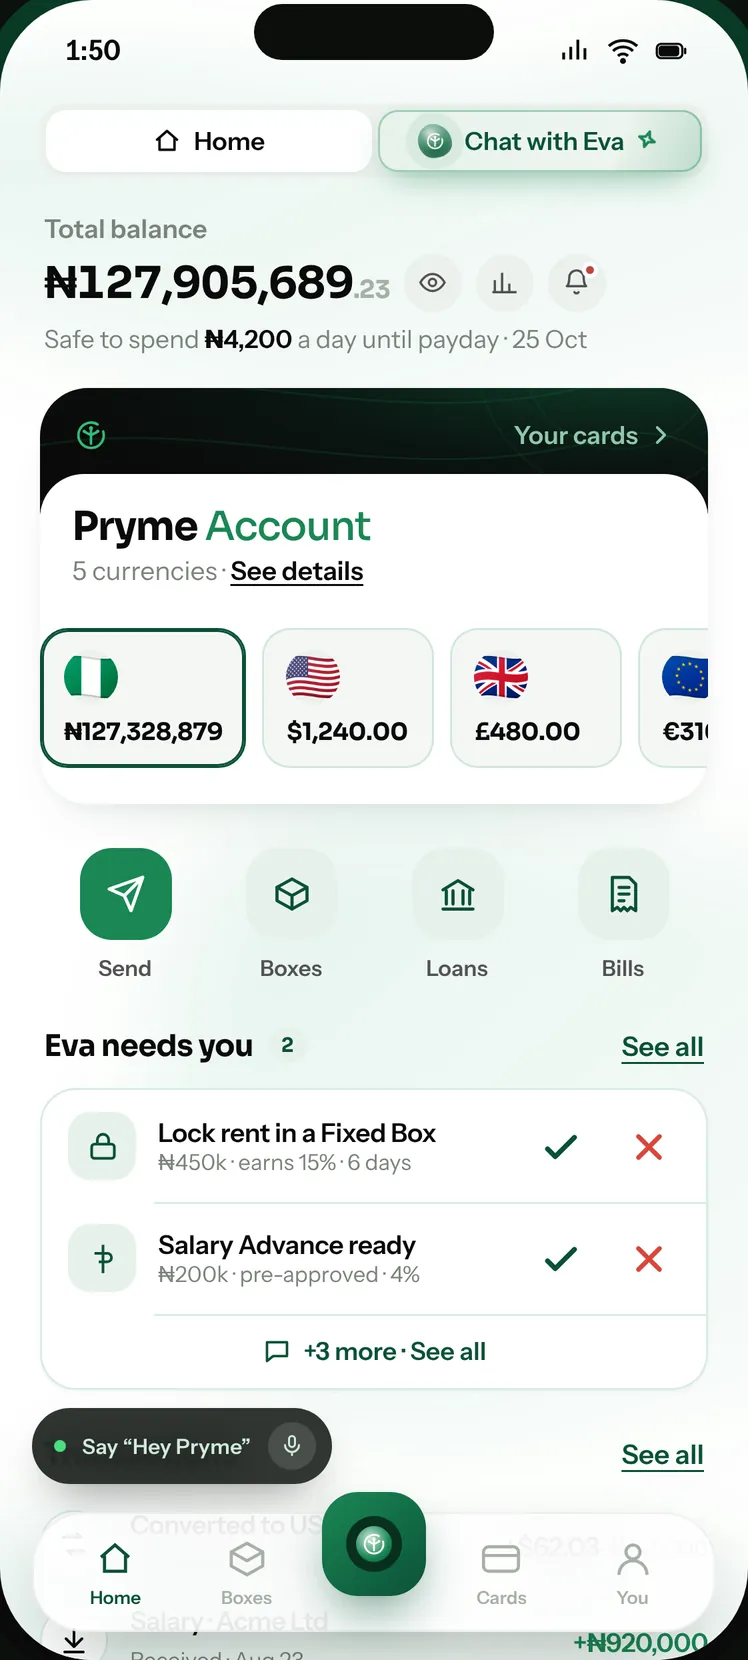
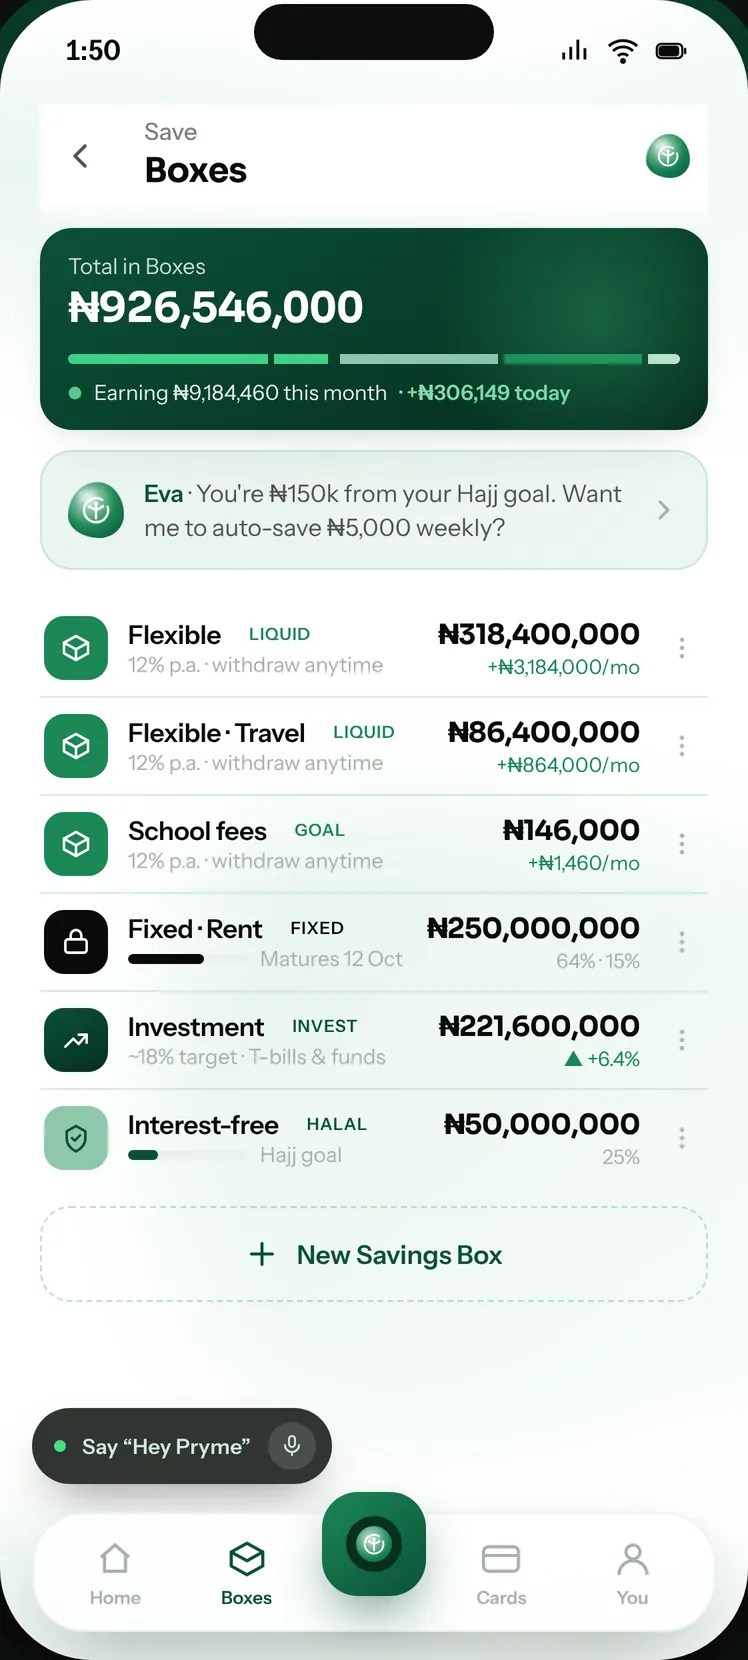
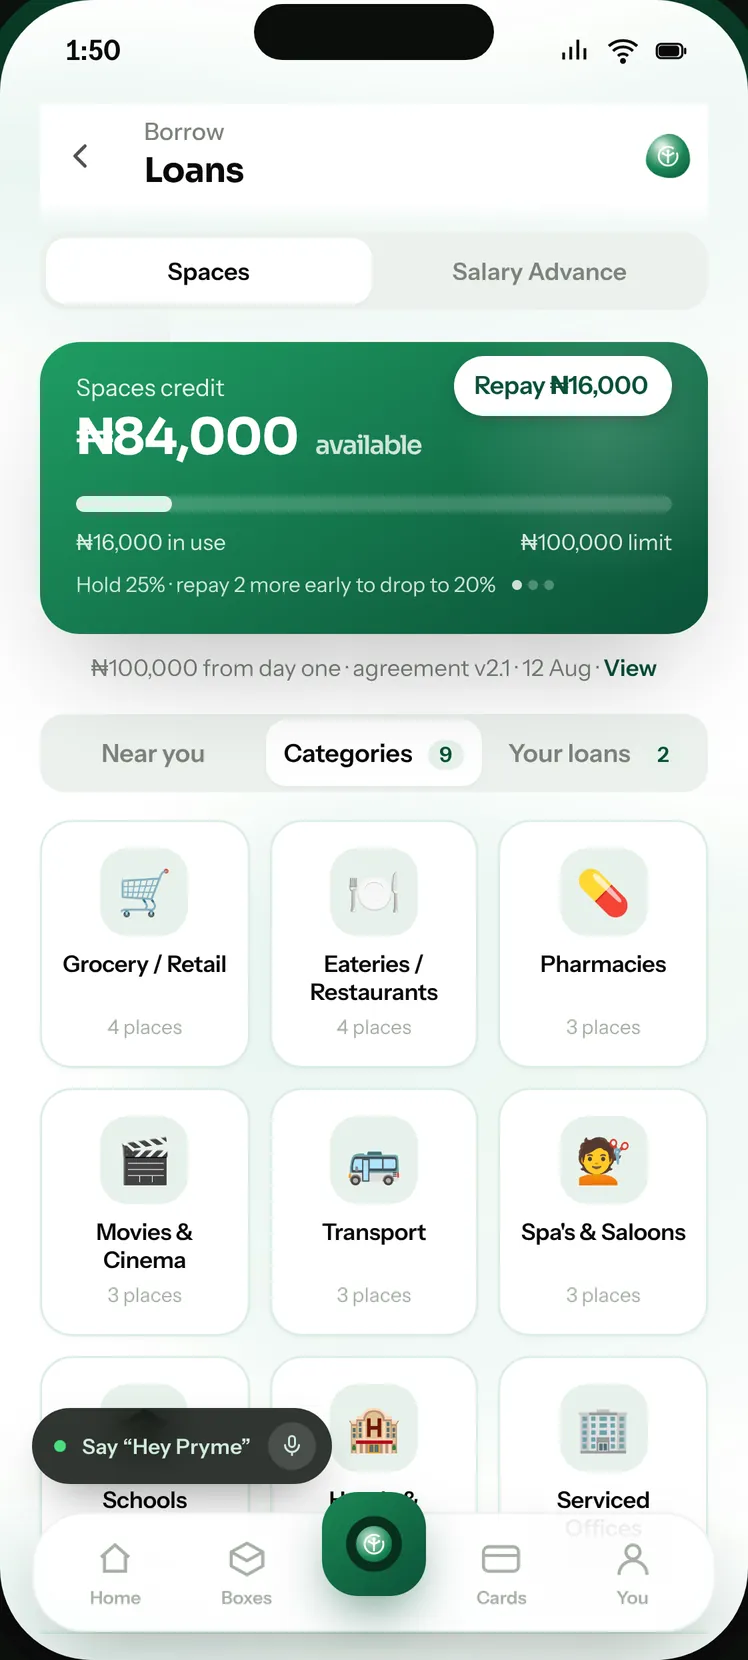
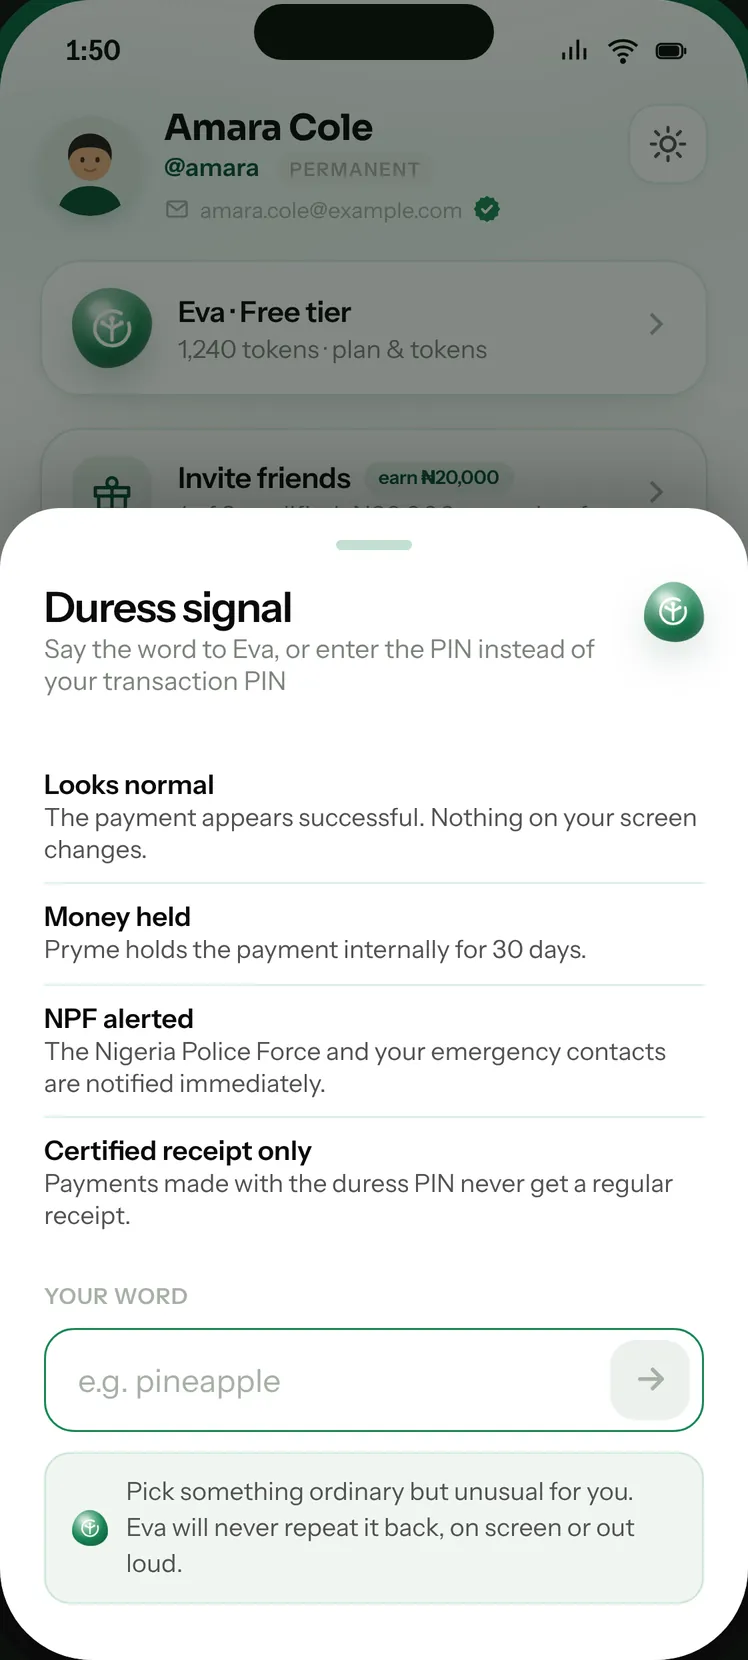
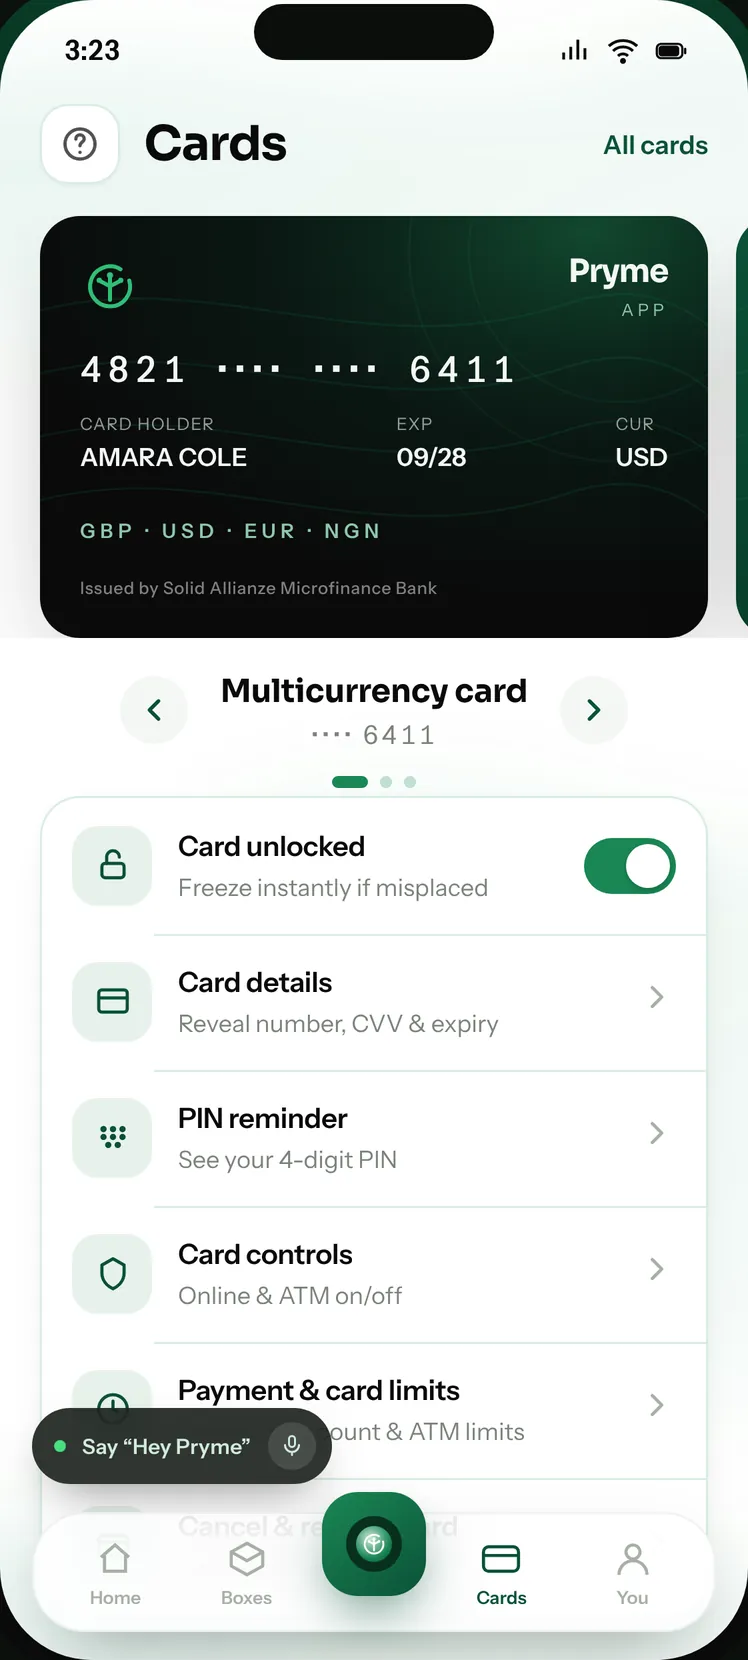
We give you a limit to spend at the shops and services you already use — and an account that works on your month while you get on with it. Dollars, pounds and euros sit beside your Naira, and an assistant handles the running of it, asking you first every single time.
One global account for your money and business. Move across currencies, automate everyday operations and put AI agents to work — with you in control of every important decision.
 Evayour assistant
 DanielChief of Staff
 BenFinance
 BruceCare
Your competitor down the road sells the same thing you sell. The difference is who walks in. We put money in people’s hands that can only be spent in businesses like yours — and then we point them at you.
You are not borrowing. You are selling to somebody who already has the money — and that money can only be spent with a business like yours.
₦100,000 from day one · agreement v2.1 · 12 Aug · View
Eva waits for your rate and asks before she moves anything.
No card, no OTP, nothing for the buyer to type in. They transfer from the bank app they already use, and the money lands in the same account your agents are running — already matched to the order, already in your books.
We give the buyer a one-time account number. They transfer to it from any bank app or by USSD — no card, no OTP, nothing to type in.
Get the account numberTo this account, from any bank app. We watch it, and the page updates itself.
₦26,767.50 from GTBank · John D., matched to order ORD‑1042.
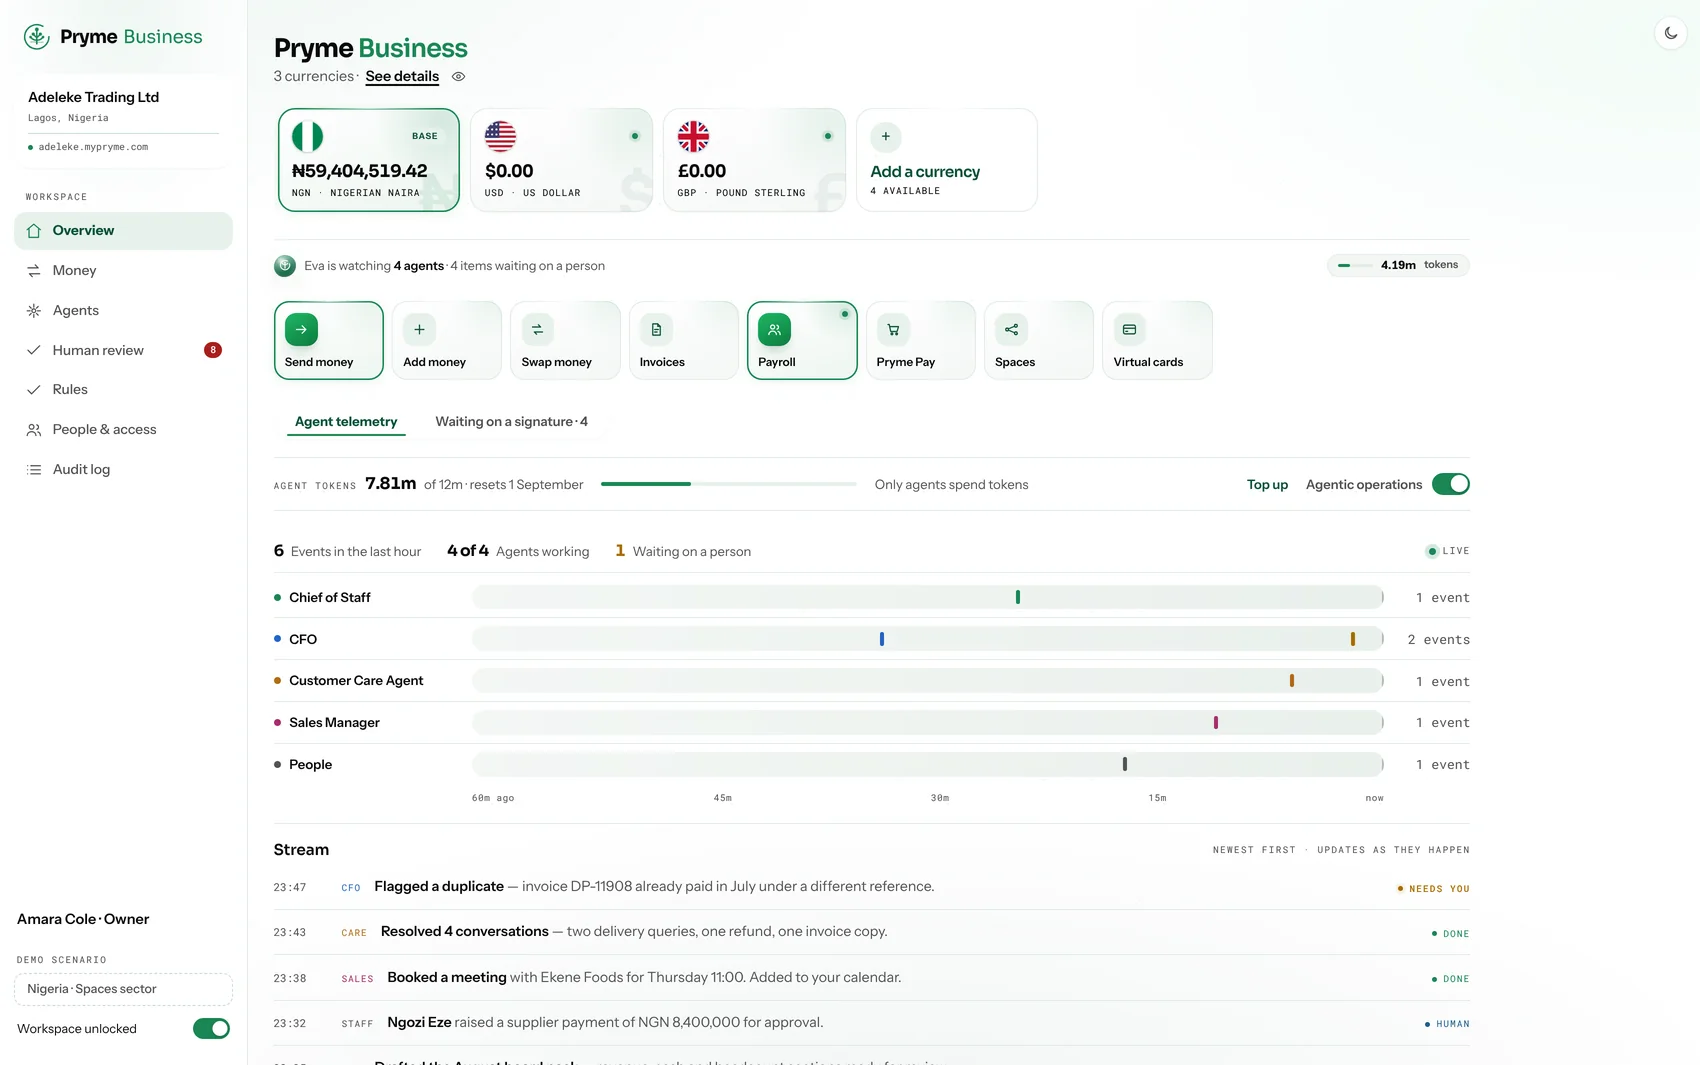
Five agents come with the account. Each one has a job description, a budget and a ceiling you set. They do the work and bring it to you — nothing leaves the account without your signature.
Knows what is stuck, who is waiting and what you promised — and keeps all three moving.
Booked a meeting with John Doe Foods for Thursday 11:00.Keeps the books as you trade and tells you the moment something does not add up.
Flagged a duplicate — invoice DP‑11908 was already paid in July.Holds every filing to its own clock and screens names and payments against your policy — and logs what it refuses.
Screened 412 payments overnight and refused two of them.Goes back to the buyers who went quiet, with the receipt already attached.
Recovered ₦410,000 across three overdue invoices.Replies, follows up on what they asked for and hands you only the ones that need you.
Resolved 4 conversations — two deliveries, one refund.Issue a dedicated Naira account number to each of your own customers, collect into it and reconcile against it. The same rails the Business Account runs on, with the licence behind them.
Dollars, pounds and euros beside a Naira account, on one ledger and one set of books. Five agents come with it and run the account — nothing leaves without your signature.
Five agents come with the account. Each has a job description, a budget and a ceiling you set. They do the work and bring it to you — they propose, you approve.
Knows what is stuck, who is waiting and what you promised, and keeps all three moving.
Booked the quarterly review with your auditor for Thursday.Keeps the books in every currency you hold and flags the moment something does not add up.
Flagged a duplicate — invoice DP‑11908 was already paid in July.Holds every filing to its own clock and screens names and payments against your policy — and logs what it refuses.
Screened 412 payments overnight and refused two of them.Goes back to the buyers who went quiet, with the invoice and the receipt already attached.
Recovered $12,400 across three overdue invoices.Replies, follows up on what they asked for and hands you only the ones that need you.
Resolved 4 conversations — two deliveries, one refund.The business has changed shape four times and never changed what it was rooted in. Each version was built out of what the last one could not do.
An online grocery store, built out of a faulty tab. Selling the food was the easy part — taking the money for it, and moving it, turned out to be the business.
A prepaid card. The first time the company issued rather than resold, and the first time it carried the obligations that come with holding somebody else’s money.
Solid Allianze acquired — an existing bank with an existing licence. The perimeter stopped being someone else’s to draw.
More than one currency on one balance, and the rebrand to Pryme. A Nigerian business could hold dollars without holding a second institution.
Accounts that do the work rather than only hold value. Five agents on the account, inside a policy you write — which is where the new mark starts.
Pryme is a financial technology company. It gives people and businesses in Nigeria one account that holds Naira alongside dollars, pounds and euros, and a set of agents that do the running of it — keeping the books, chasing what is owed, answering customers and paying bills. Nothing leaves an account without the owner’s approval.
Yes. A Pryme account holds Naira, US dollars, pounds sterling and euros side by side on one ledger, each with its own account details — a Nigerian account number, a US account number, a UK sort code and an IBAN for the euro area. You can swap between them at a rate you set, and every currency has its own statement.
Spaces is available in Nigeria. It gives a shopper money to spend that can only be spent with a participating business. The business is paid into its Naira account whether or not the shopper repays, because Pryme carries the credit. For the business it is free to join, there is nothing monthly, and the customer’s identity is never shown — only a reference and what it is worth.
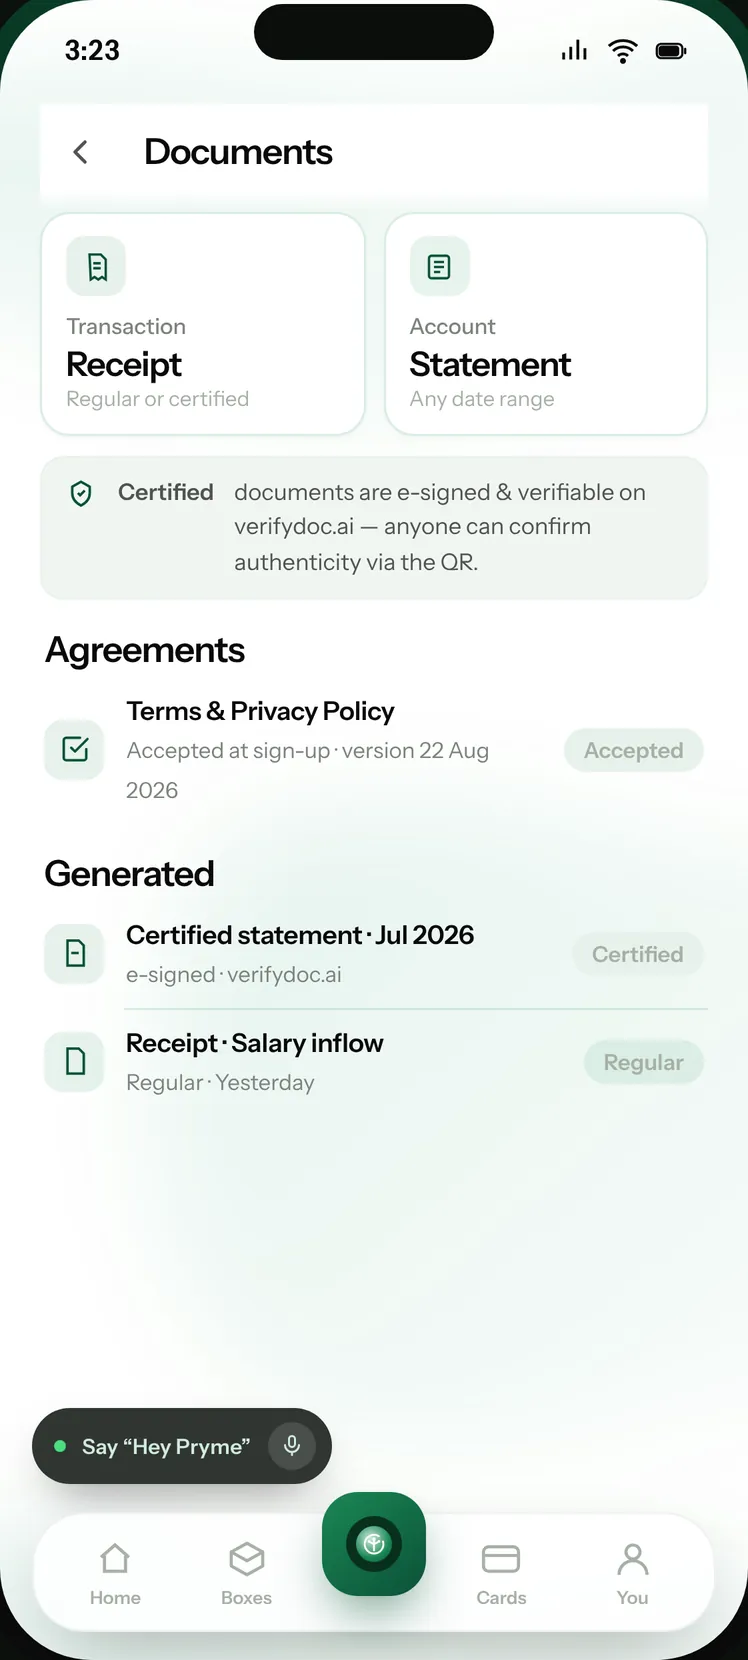
Five agents come with the account. The Chief of Staff runs the week and keeps what is stuck moving. Finance watches the money and keeps the books as you trade. Compliance keeps the filings on time and screens what moves. Sales chases what you are owed. Customer Support answers your customers and follows up. Each has a job description, a budget and a ceiling you set, and each one proposes rather than acts — nothing leaves the account without your signature.
Pryme Pay takes payments on your own site or on a checkout page you control. The buyer is given a one-time account number and transfers to it from any bank app or by USSD — no card, no OTP, nothing to type in. The money lands in the same account your agents are running, already matched to the order and already in your books.
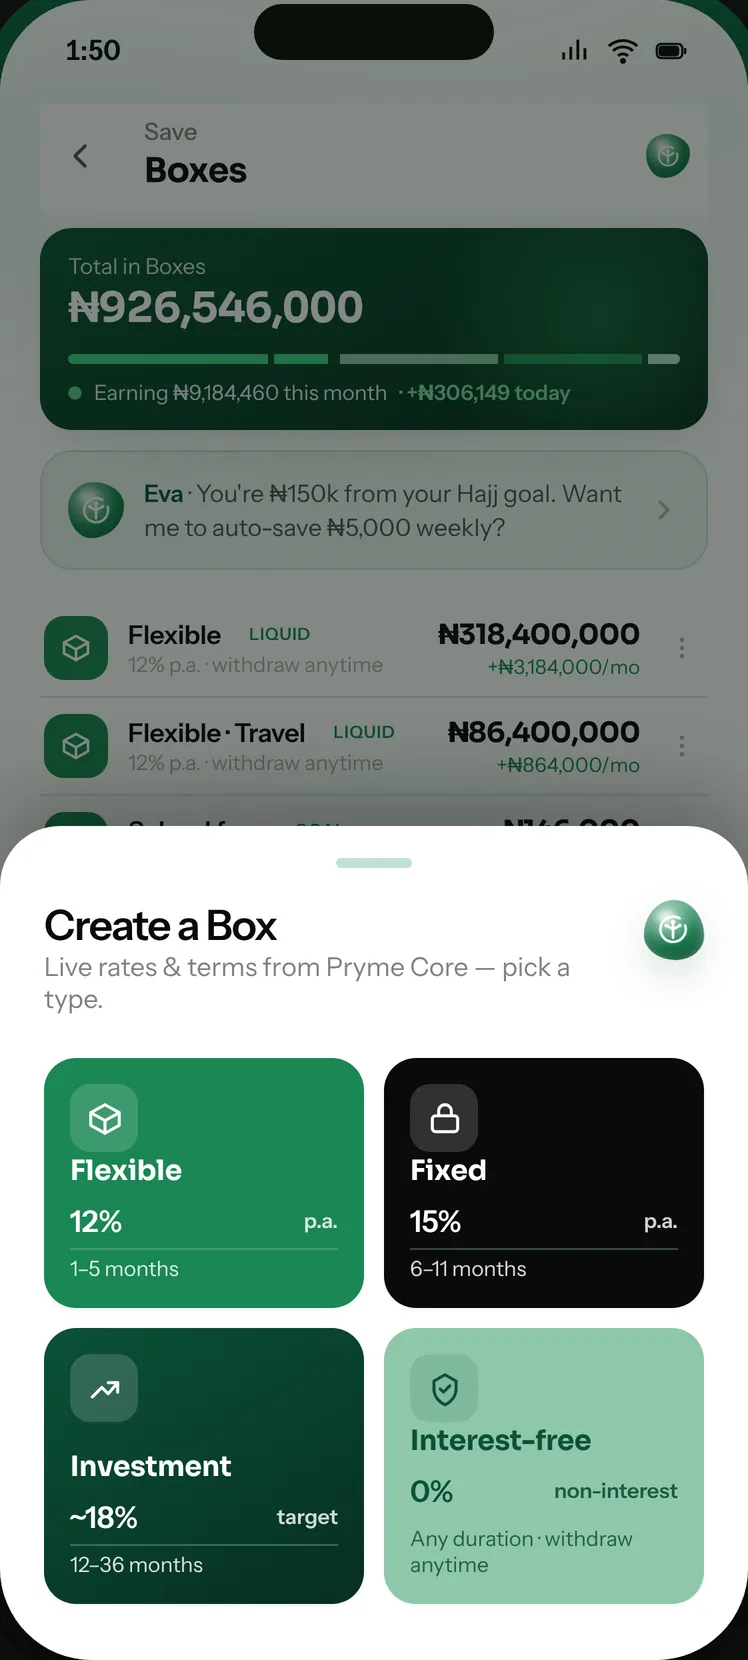
Savings Boxes are separate pots inside a Pryme account, held in Naira. Flexible Boxes can be withdrawn at any time, Fixed Boxes hold to a date, Investment Boxes hold for longer, and Interest-free Boxes earn nothing by design. A business can use them to ring-fence payroll and the tax it withholds, so that money cannot be spent by accident.
Pryme is a financial technology company, not a bank. Accounts and deposits are provided by Solid Allianze Microfinance Bank Limited, which is licensed by the Central Bank of Nigeria and is a member of the Nigeria Deposit Insurance Corporation.
Yes. Pryme Rails lets a platform issue a dedicated Naira account number to each of its own customers, collect into it and reconcile against it, over one API — the same rails the Pryme Business Account runs on.
Pryme is a financial technology company. It gives you one account that holds US dollars, pounds sterling and euros beside Naira, with an assistant that runs the account for you and asks before anything moves. Accounts are provided in Nigeria today, and further markets open as each licence lands.
Accounts are provided in Nigeria today, subject to verification and approval. Foreign-currency balances are held and converted inside that account, so you can hold, receive and swap dollars, pounds and euros wherever you are.
Naira, US dollars, pounds sterling and euros, side by side on one ledger. Each has its own details — a Nigerian account number, a US account number, a UK sort code and an IBAN for the euro area — and each has its own statement.
Swap at a rate you set rather than the rate of the day, then send to any Pryme username or to a Nigerian bank account. There is no fee to send to another Pryme account.
Eva is the assistant inside the Pryme app. She opens accounts, moves money, saves toward your goals, pays what is due and follows up what is owed to you — and asks you before anything moves.
Pryme Rails lets a platform issue a dedicated Naira account number to each of its own customers, collect into it and reconcile against it, over one API — the same rails the Pryme Business Account runs on.
Notes on money that does the work: what we are building, what the regulation actually says, and how we think about letting software act on money. Read the Ledger
What AI agents can do in bookkeeping, close, collections and compliance today, where a person must stay in charge, and how to judge a product.
How multi-currency business accounts work: local details vs SWIFT, payment rails, the real cost of FX, safeguarding vs deposit protection, and hedging.
How UK, US, Canadian and European firms pay Nigerian suppliers and get paid by Nigerian clients: FX, Form A and M, tax, compliance and payout routes.
What it really costs to send money to Nigeria from the UK, US, Canada and Europe: fees, exchange-rate margins, CBN naira rules, BVN, speed and scams.
What AI can and cannot do in day-to-day bookkeeping, how much time it saves on real numbers, and which jobs must stay with you or your accountant.
What we are building, what the regulation actually says, and how we think about letting software act on money.
All of All diasporaInvest and save at home · 103 articles
Why unpaid ground rent and land fees can lead to revocation of an Abuja title, and how a buyer abroad can confirm the bills are clear before paying.
What an estate allocation letter gives a buyer in Nigeria, why it is not title, and the documents that should follow before your purchase is secure.
How Nigerian angel networks pool members' money into startups through SPVs and syndicates, what members pay and commit, and what to check abroad.
How shareholders living abroad accept, partly accept or renounce rights in a Nigerian bank's offer, how to pay in naira, and the deadlines to watch.
How to reactivate an old Nigerian stockbroking account from abroad and confirm through CSCS that your shareholdings are still intact.
Before you send money for blocks and cement, get the family's consent on paper and the land into your name. The documents, and the disputes they prevent.
Several names on one deed, a family company, or a trust: what each structure needs, what it costs to run, and the clauses that stop disputes later.
Who must sign when you buy customary family land in Nigeria, how to confirm the family really consented, and the checks to run from abroad first.
Much Ibeju-Lekki land was under government acquisition. How to confirm excision and gazette status, avoid project land and vet developers.
The main Nigerian land documents explained for buyers abroad: what a C of O, deed of assignment, survey plan, excision and receipts each prove.
How often you can move your RSA to a new Pension Fund Administrator, what PenCom bans, and how to prepare a transfer request while living abroad.
How to change your address, phone, email and dividend bank details with a Nigerian registrar from abroad, and how CSCS and broker records fit in.
How to confirm a Lagos agent or developer is registered with LASRERA before you send a deposit from abroad, and what else to check besides the register.
How to confirm a Nigerian lawyer is enrolled on the Supreme Court roll and known to the NBA, before you send money for land or legal work.
Use the SEC's Find a Registered Operator directory and NGX's broker list to confirm a Nigerian stockbroker is real before you send money from abroad.
Your share of inherited or family land does not lapse because you moved away. How rights arise, how a share is separated, and how a lawyer acts for you.
How siblings spread across countries agree to sell an inherited Nigerian property, sign from abroad, satisfy the administrators rule and share the proceeds.
The developer's root title, the sub-lease or assignment you receive, the Governor's consent and handover checks for a completed flat bought from abroad.
How a lump-sum contractor compares with buying materials and hiring labour yourself when you are building in Nigeria from abroad and cannot be on site.
The latest stop rates on 91, 182 and 364-day Nigerian Treasury bills, how they compare with inflation, and what withholding tax does to them.
Why an unregistered deed of assignment leaves a buyer exposed in Nigeria, and the consent, stamping and registration steps to finish from abroad.
How to turn old paper Nigerian share certificates into CSCS holdings while you live abroad: the broker, the registrar, the forms and the identity checks.
The red flags the SEC lists for Nigerian investment schemes, how they show up in offers to Nigerians abroad, and how to check registration before paying.
How Nigerians abroad become limited partners in Nigeria-focused venture funds: commitments, capital calls, lock-ups, reporting and the checks to run.
What a property due diligence firm in Nigeria should check, what it will not cover, and how to write a brief that gets you usable answers from abroad.
What Nigerian dollar (Eurobond) funds hold, the fees and holding periods on two real funds, how fast you can get out, and the risks to weigh.
What Nigerian law says about pricing and paying for property in dollars, why the naira is legal tender, and the payment risks for buyers abroad.
What can happen if you miss instalments on a Nigerian estate plot, the contract clauses that decide it, and what to agree before you pay from abroad.
Security, power, water, waste, roads: what a Lagos estate service charge covers, what binds you to pay it, and what courts have said in disputes.
What excision and a gazette mean for Nigerian land, why excised land is not the same as titled land, and how to check a plot from abroad.
The term, rent, community consent and registration points a Nigerian farmland lease must cover, and how the Land Use Act shapes who can grant one.
How often FGN bonds pay coupons, which naira account they land in, how to work out each payment, and what to do when you want it converted abroad.
The DMO's minimum for FGN bond auctions is out of reach for most savers. Here is the figure, how auctions work, and the routes for smaller sums.
How a Nigerian abroad sells an FGN bond before it matures, through whom, how the price is set and why rising yields can mean selling at a loss.
The most recent FGN bond auction yields across tenors, how they moved, and how retail FGN Savings Bond rates compare, dated and sourced.
What Nigeria's sovereign green bonds are, the minimum on the last issue, how to subscribe or buy later from abroad, and why you need a naira account.
Investing in Nigeria from abroad can run through imported FX with a CCI or a naira account. How each route treats repatriation, and the NRNIA option.
How Nigeria's SEC treats fractional real estate offers, where crowdfunding, REIT and tokenisation rules fit, and what a diaspora investor should verify.
Why a Nigerian property purchase is not complete until the Governor consents, who usually applies, the documents involved and how to run it from abroad.
What charting at the Surveyor-General's office reveals about a Nigerian plot, how to check a surveyor is registered, and how to brief one remotely.
A Nigerian company can own land, collect rent and pass to heirs as shares. What it costs to run, how it is taxed, and when it is not worth it.
Moving a late parent's Nigerian shares into your name from abroad: the court grant, the registrar's transmission papers and the CSCS steps.
Which covers exist for a Nigerian house, which the law makes compulsory for rented and multi-storey buildings, and how to buy and claim from abroad.
The documents behind investing in a Nigerian startup from abroad: subscription, CAC allotment filings, the CCI for foreign currency, and PSC disclosure.
Why buying Nigerian land on an irrevocable power of attorney leaves you weaker than a deed of assignment, when it is used, and how to protect yourself.
How develop-and-share deals with Nigerian landowners work, and the agreement terms that protect an investor who funds the build from abroad.
Why fencing, a caretaker, signage and regular visits matter for land you own in Nigeria, and how they help you prove possession if someone moves in.
The Lagos planning permit and building control approvals your house needs, how the online EPPPS system works from abroad, and what a representative does.
Lagos launched an e-GIS land portal in 2024. What it was announced to do, what a search shows, and which checks still need someone on the ground.
How to check flood-prone areas, drainage and wetland status before buying property in Lagos from abroad, using official outlooks and on-site checks.
What rules apply to a Lagos shortlet run from abroad, where estate bans and taxes stand, and how bookings, cleaning, caution deposits and payouts can work.
How to estimate occupancy, platform fees, power, cleaning and management costs to see what a Lagos shortlet earns, with a worked example against a long let.
How land banking works in Nigeria, why it is marketed to the diaspora, the legal and fraud risks, and the checks to make before you pay a company or plan.
The title, survey, search and identity documents to ask for and check before you send any money for land in Nigeria, with what each one proves.
What to do from abroad when a stranger builds on your Nigerian land: evidence, a police report, a petition, an injunction and a trespass suit.
What a land registry search shows, what your lawyer or representative needs from you, what it costs in Lagos, and how to read the result.
How to manage Nigerian tenants from abroad: choosing a property manager, collecting rent, receipts, notices and records, with Lagos Tenancy Law points.
How LASRERA handles complaints about Lagos agents and developers, what its law lets it do, and how to prepare and file a complaint while you live abroad.
A child cannot open a CSCS account or BVN alone. How parents abroad hold Nigerian shares, bonds and savings for a child, and where the limits are.
How the surrender value of a Nigerian savings or endowment life policy is worked out, what to ask the insurer, and how a policyholder abroad gets paid.
How to work out which PFA holds your Nigerian pension, what they need to confirm it is you, and how to get your RSA PIN back from outside Nigeria.
Who PenCom's micro pension plan is for, whether a Nigerian living abroad fits, and the newer foreign-currency RSA route PenCom points the diaspora to.
How naira money market fund redemptions are paid when you live abroad, how long they take, and the holding-period charges to check first.
A high naira yield is only half the answer. How to convert a Nigerian return into pounds, dollars or euros, with labelled worked examples.
How Nigerian dividends are paid by registrars into a naira account, how to set up an e-dividend mandate from abroad, and the tax taken first.
The ETFs on the Nigerian Exchange, what each type holds, the trading costs, and how investors outside Nigeria can buy them through a stockbroker.
How bonus issues and share splits on the Nigerian Exchange reach your CSCS account, and how to confirm from abroad that yours were credited.
The facts of Nigeria's first diaspora bond from its own pricing notice: where it was sold, the minimum, the coupon dates and when it matured.
Nigeria's only diaspora bond matured in 2022. What officials have said about a second one since, what is on offer instead and how to spot a fake.
How Nigerian Eurobonds trade, the minimum lot size the DMO cites, the broker routes open to individuals abroad, and the fund options for smaller sums.
Which companies with Nigerian operations trade on foreign exchanges, how Africa ETFs carry Nigeria exposure, and what that exposure means for investors abroad.
What Nigerian banks do with a fixed deposit at maturity if you give no instruction, and how to roll it over or take the money from abroad.
How Nigerian commercial paper works, who is allowed to buy it, the routes for Nigerians abroad, how the discount pays you and the risk you carry.
How to convert a Nigerian Exchange index or portfolio return into dollars, pounds or euros to see what you earned after the naira's moves.
How to set up a written crop-sharing or profit-sharing agreement when you fund a farm in Nigeria run by a relative, and the terms that matter.
What happens to a Nigerian life insurance policy when you emigrate: paying premiums from abroad, updating beneficiaries, and how a claim works.
How diaspora investors take part in a Nigerian IPO, public offer or rights issue: the stockbroker, the CSCS account, NGX Invest and paying in naira.
NMRC does not lend to you. It refinances mortgages that lenders make to agreed standards, including a diaspora standard. What that means for your loan.
How a landlord living abroad ends a tenancy in Nigeria through a solicitor: notice periods, the 7-day notice, court recovery, and what not to do.
What a buyer abroad can do when a Nigerian developer misses the handover date: read the contract, send notice, claim a refund or damages, or go to LASRERA.
How to structure milestone payments to a Nigerian developer or builder, when escrow helps, what to hold back, and the evidence to ask for at each stage.
Half of each voluntary pension contribution can come out one year after you pay it in. How the PenCom rule works, the tax point, and asking from abroad.
The records, site checks and cost controls that protect money you put into a small poultry or catfish farm in Nigeria that someone else runs.
How to check the developer, the title and the payment terms behind Nigerian homes marketed at diaspora property expos before you pay a deposit.
The searches, documents and post-sale steps a Nigerian property lawyer should handle for a buyer abroad, and how to check and pay them safely.
The clauses to put in a property management agreement for a Nigerian house you own from abroad: fees, rent remittance, reporting, repairs and exit.
The payment records, receipts and stamped documents a buyer abroad should keep for title, tax and moving money later, and how to organise them.
Who may legally value property in Nigeria, how to check them from abroad, what a proper valuation report contains, and when you need one.
Direct transfer to your naira account, an agent or a property manager: how each rent collection method works, the receipts Lagos law requires, and tax.
How to find your RSA PIN and PFA, check your balance and statement from abroad, and update the email, phone and identity details your PFA holds.
How PenCom's rule letting RSA holders put a quarter of their balance towards a mortgage deposit works, and where Nigerians abroad may fall short.
How RSA retirement benefits work if you retire outside Nigeria: programmed withdrawal or annuity, lump sum rules, and the account the money is paid into.
How to spot pension deductions your former Nigerian employer never paid into your RSA, and how to complain to your PFA and PenCom from abroad.
From power of attorney to Governor's consent and capital gains tax: the order of steps to sell a Nigerian house or land without flying home for each one.
NGX sales settle in naira two business days after the trade. What comes off the proceeds, where the money lands, and the routes for moving it abroad.
How Nigerian states borrow through bonds, the repayment backstop called an ISPO, who usually buys, and what to check before you put money in from abroad.
How off-campus and PPP student hostel investments work in Nigeria, what drives demand, and the land, approval, insurance and policy risks for investors abroad.
What charting a survey plan at the Surveyor-General's office reveals, the fees states publish, and how to have it done while you live abroad.
Where the CBN and DMO publish Nigerian Treasury bill and FGN bond auction dates, how the Q4 2026 programme looks, and how to plan from abroad.
What happens when a Nigerian Treasury bill matures, how rollover and redemption work, and the documents that let you move the naira abroad.
Direct Nigerian T-bill holdings versus the notes, units and pooled plans sold in apps, and the questions that tell you which one you have bought.
A half-built house is worth land plus usable work, not what you spent. How valuers price it, what buyers ask for, and finishing versus selling.
A video call shows you a plot, not who owns it. What remote inspections miss on Nigerian land, and the checks to do in person or by proxy.
You can add the other type later — many of our customers hold both.
The business first, then you. Nothing is submitted until you review it.
Ideal customer profiles
Generated from your website by VerifiedLead.ai
Pick the ones that look right. Your Sales agent works these first, and you can change them at any time after opening.
We ask this because you have not given us a website. It helps us set the right limits from day one.
Which of these represents you?
Officers listed against this company on the UK register.
We have sent a six-digit code to your email address. Enter it below to confirm the address is yours.
Wrong address? Go back and change it — nothing is created until this step passes. We never ask for a code by phone or email; anyone who does is not us.
Last step. Each time you sign in we email you a six-digit code — we never send codes by SMS.