AI agents for business finance: what they can and can't do
What AI agents can do in bookkeeping, close, collections and compliance today, where a person must stay in charge, and how to judge a product.
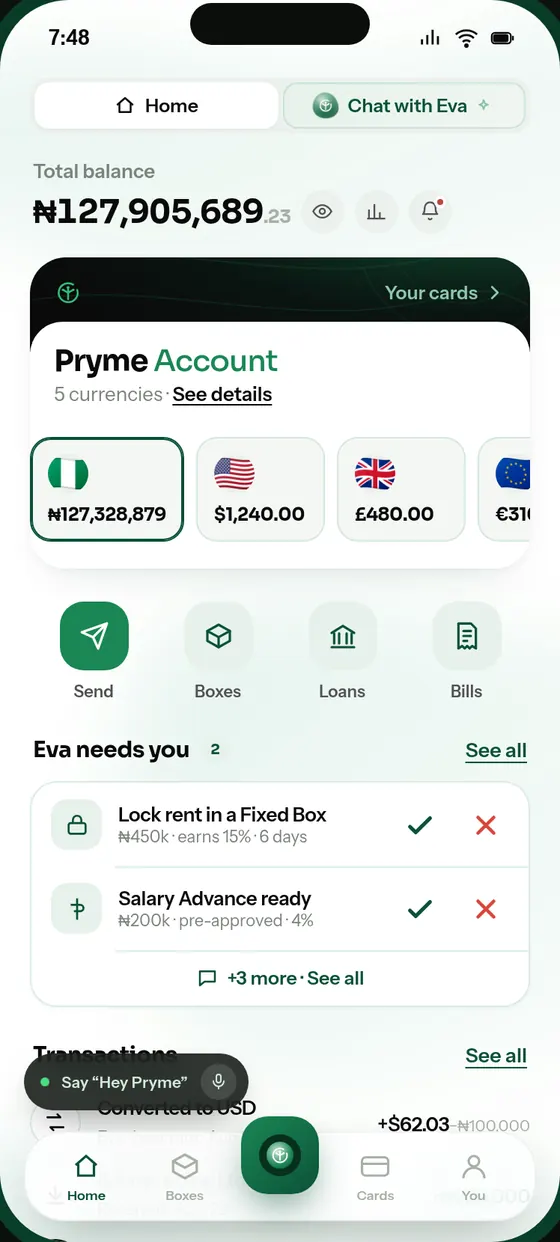
Meet Eva, the assistant inside the Pryme app. She opens accounts, moves money, saves toward your goals and follows up. Nothing leaves your account without your approval.
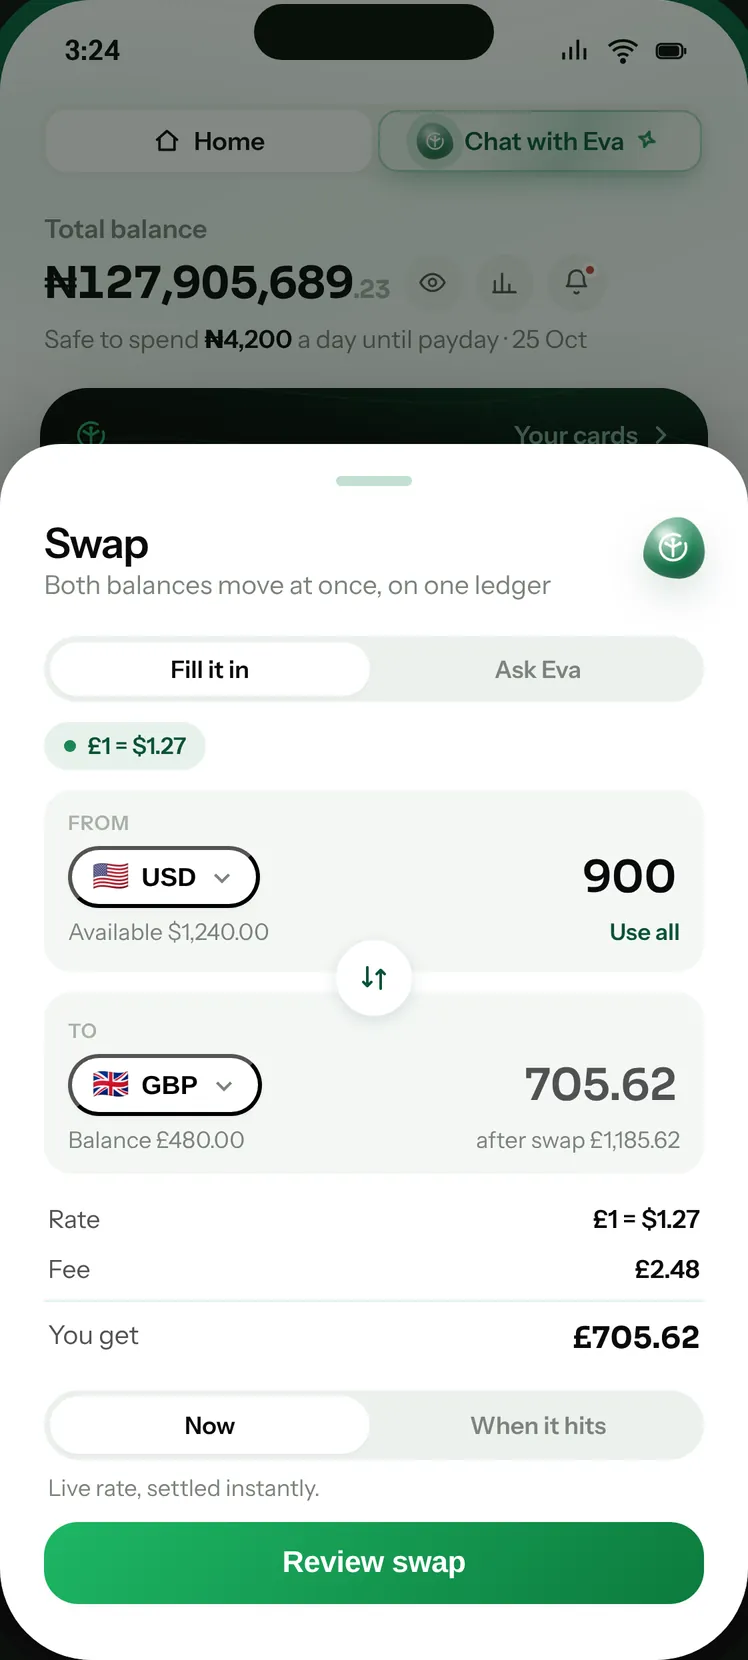
Meet Eva, the assistant inside the Pryme app. She holds dollars, pounds, euros and Naira side by side, swaps at a locked rate, pays bills in any of them and sends anywhere, asking before anything moves.
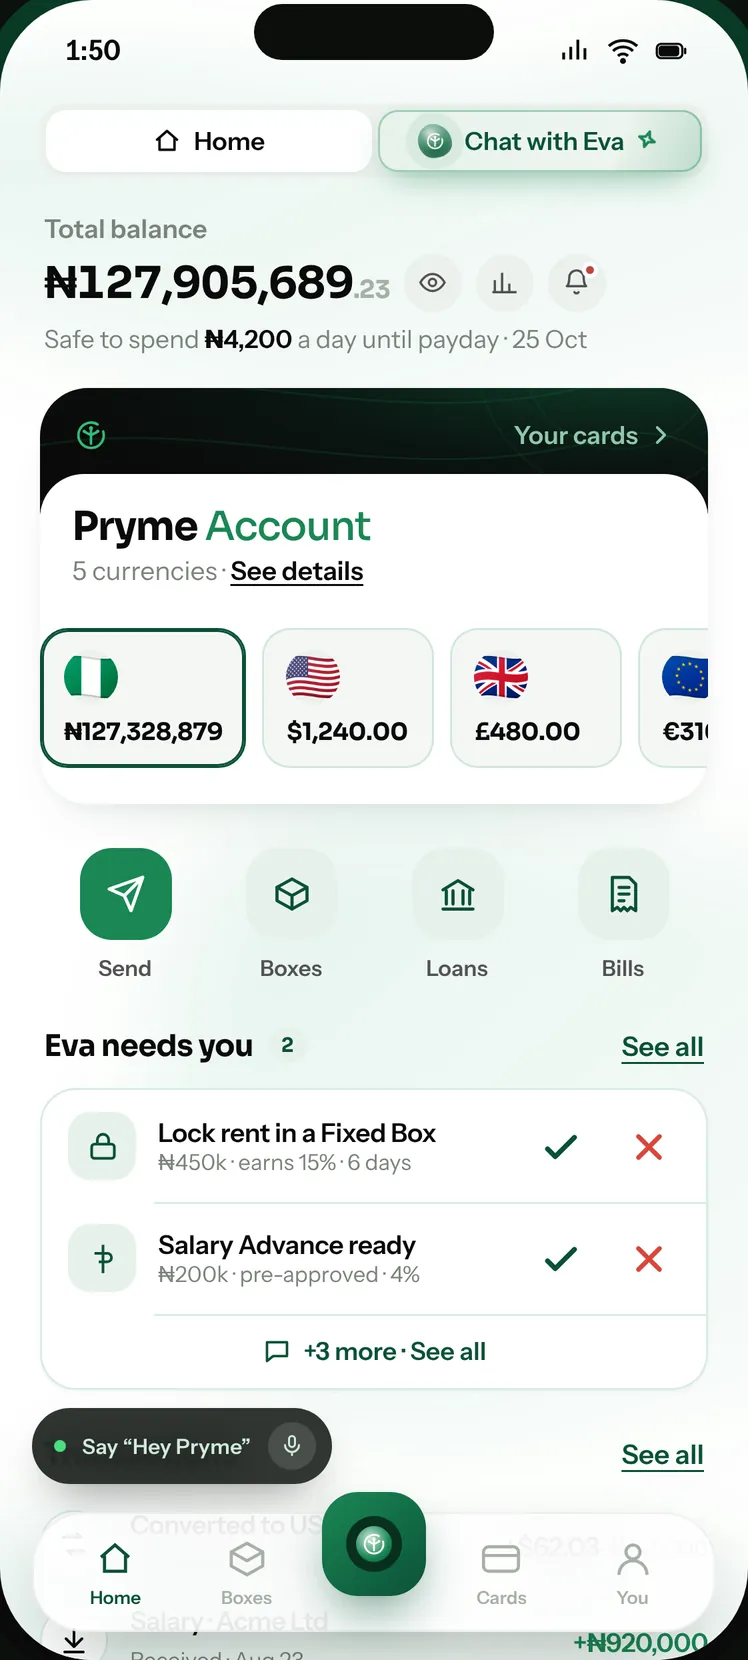
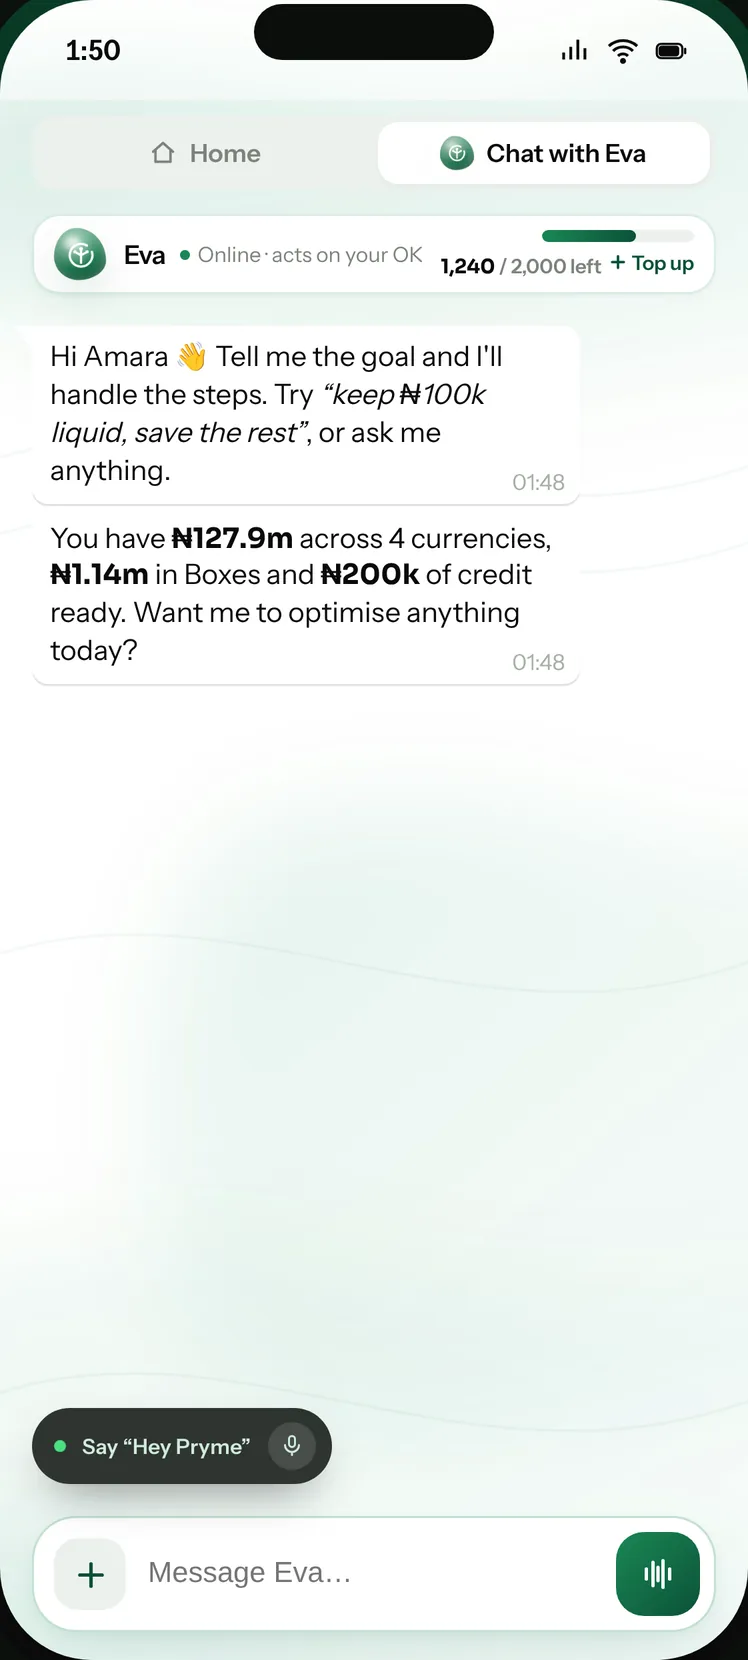
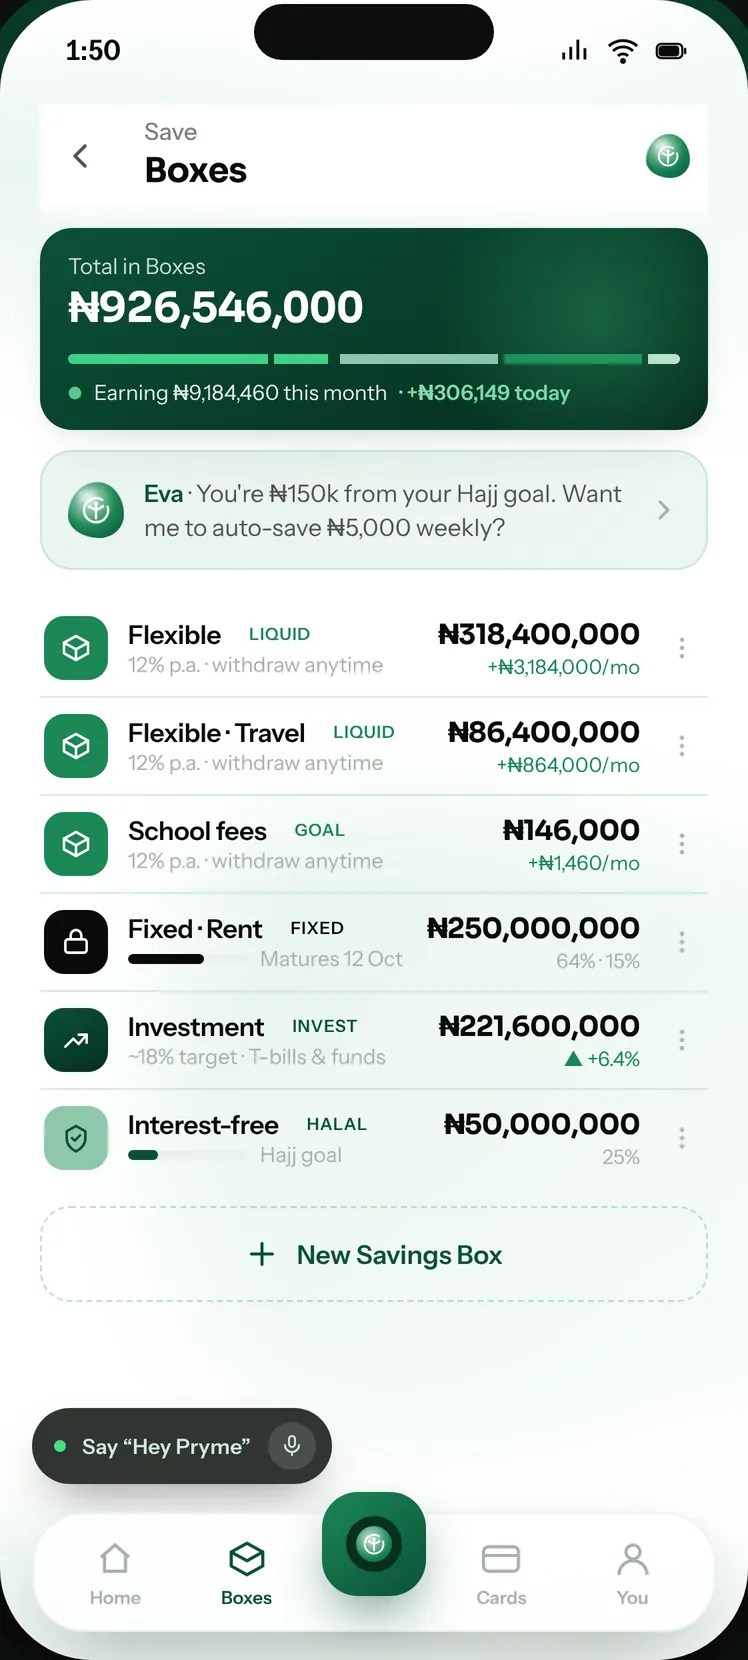
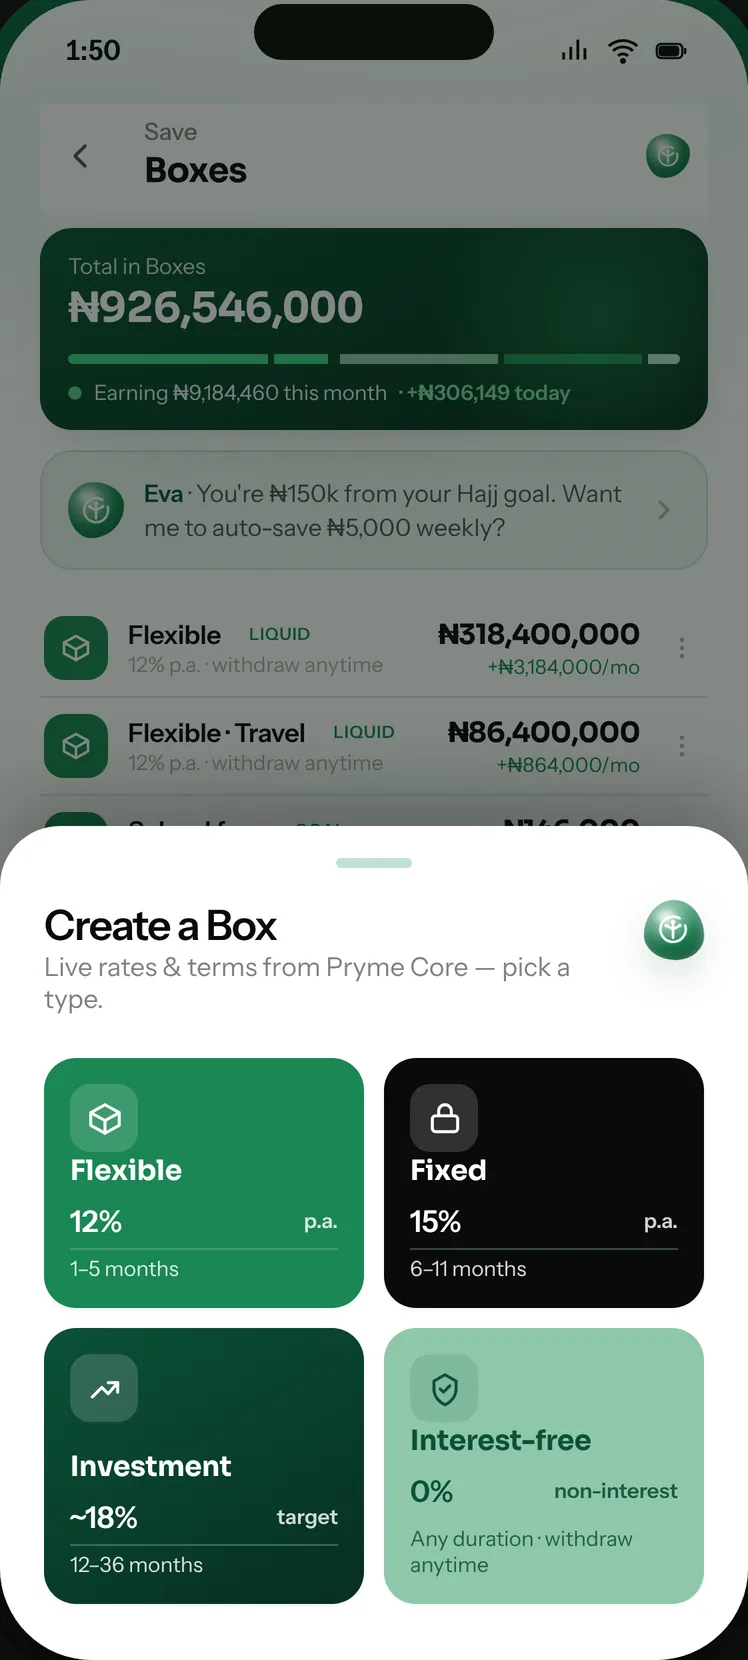
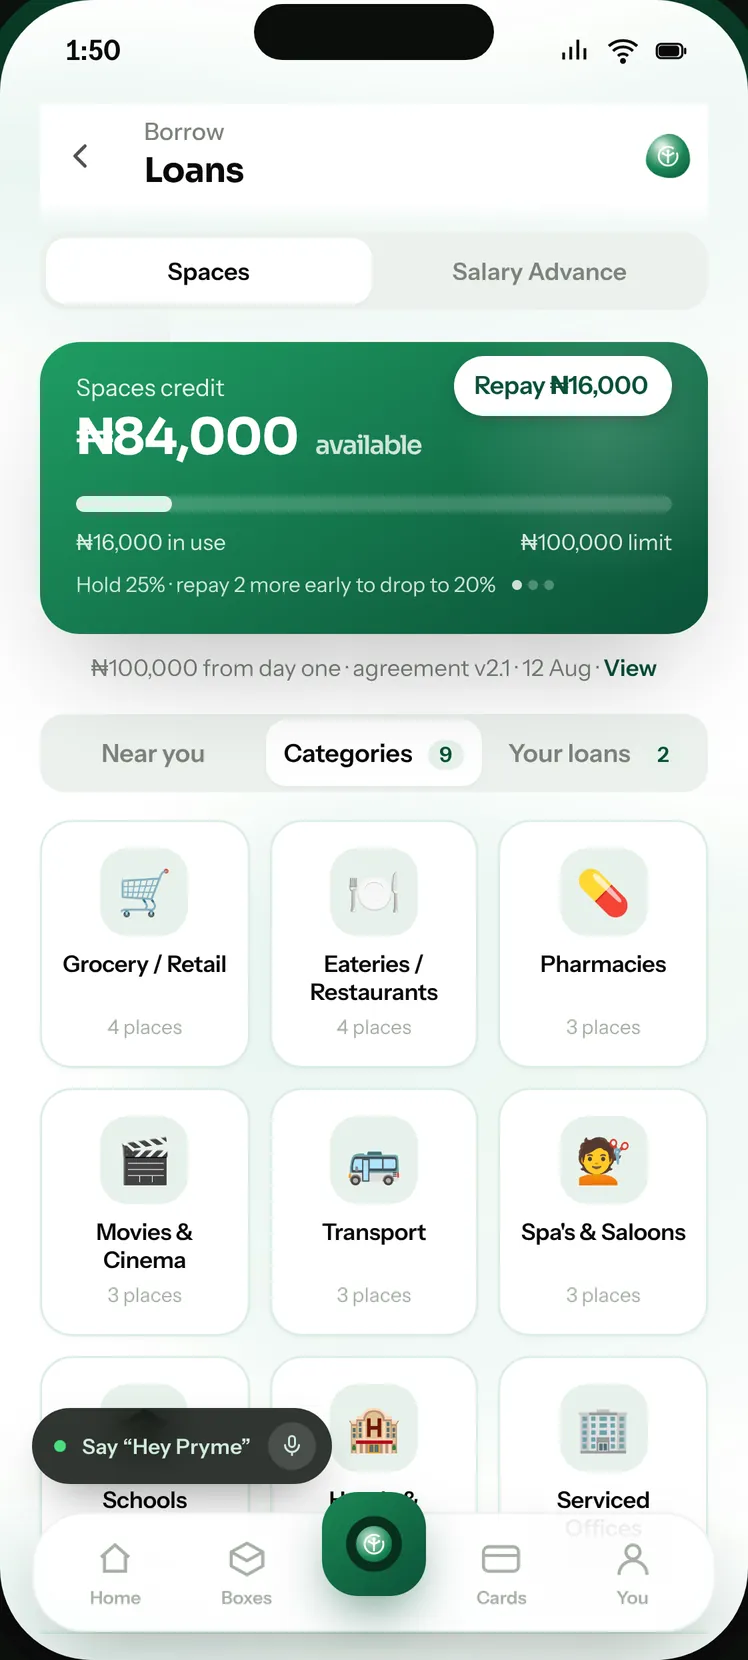
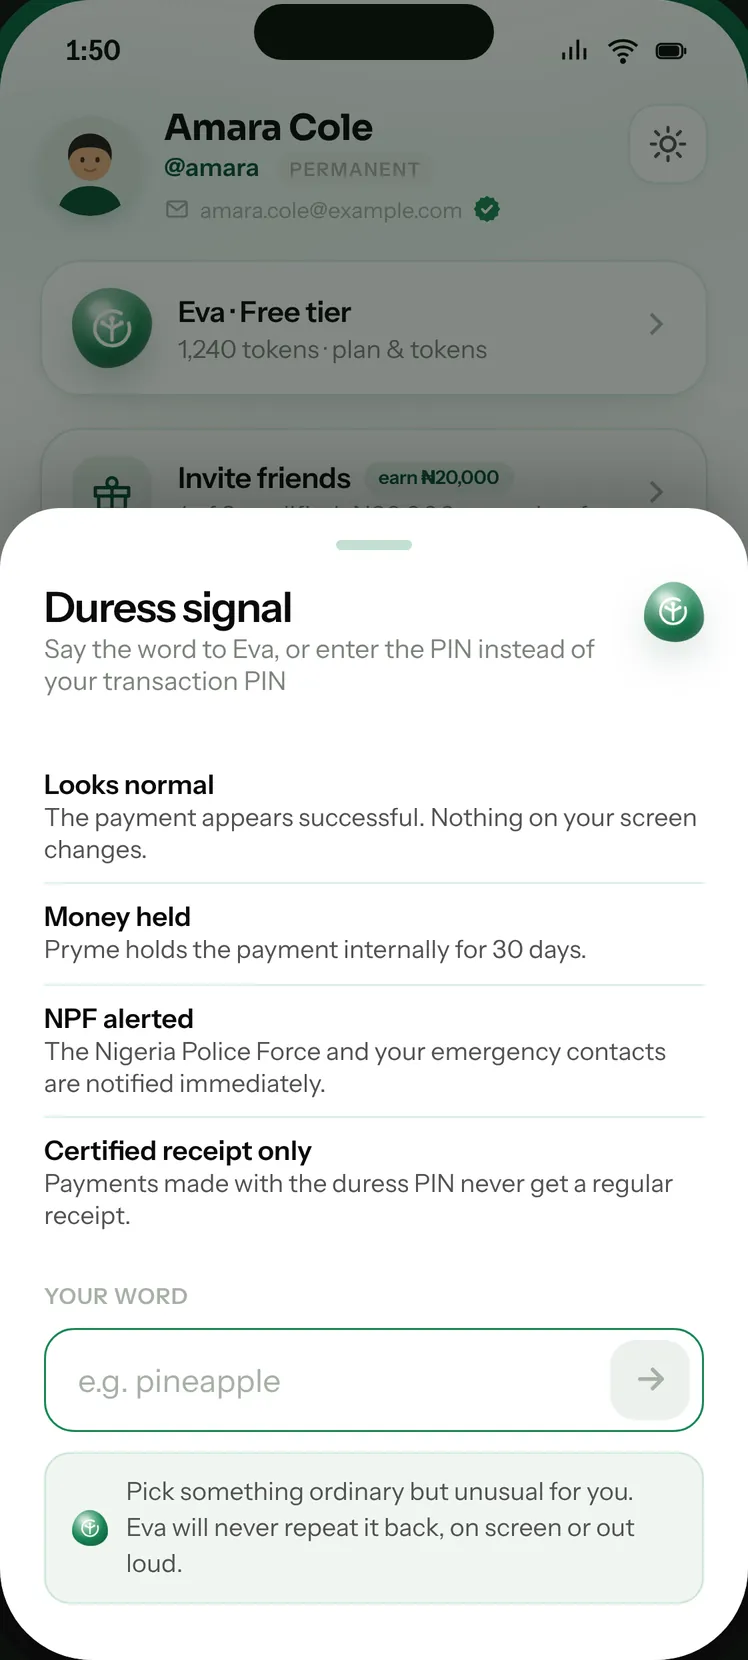
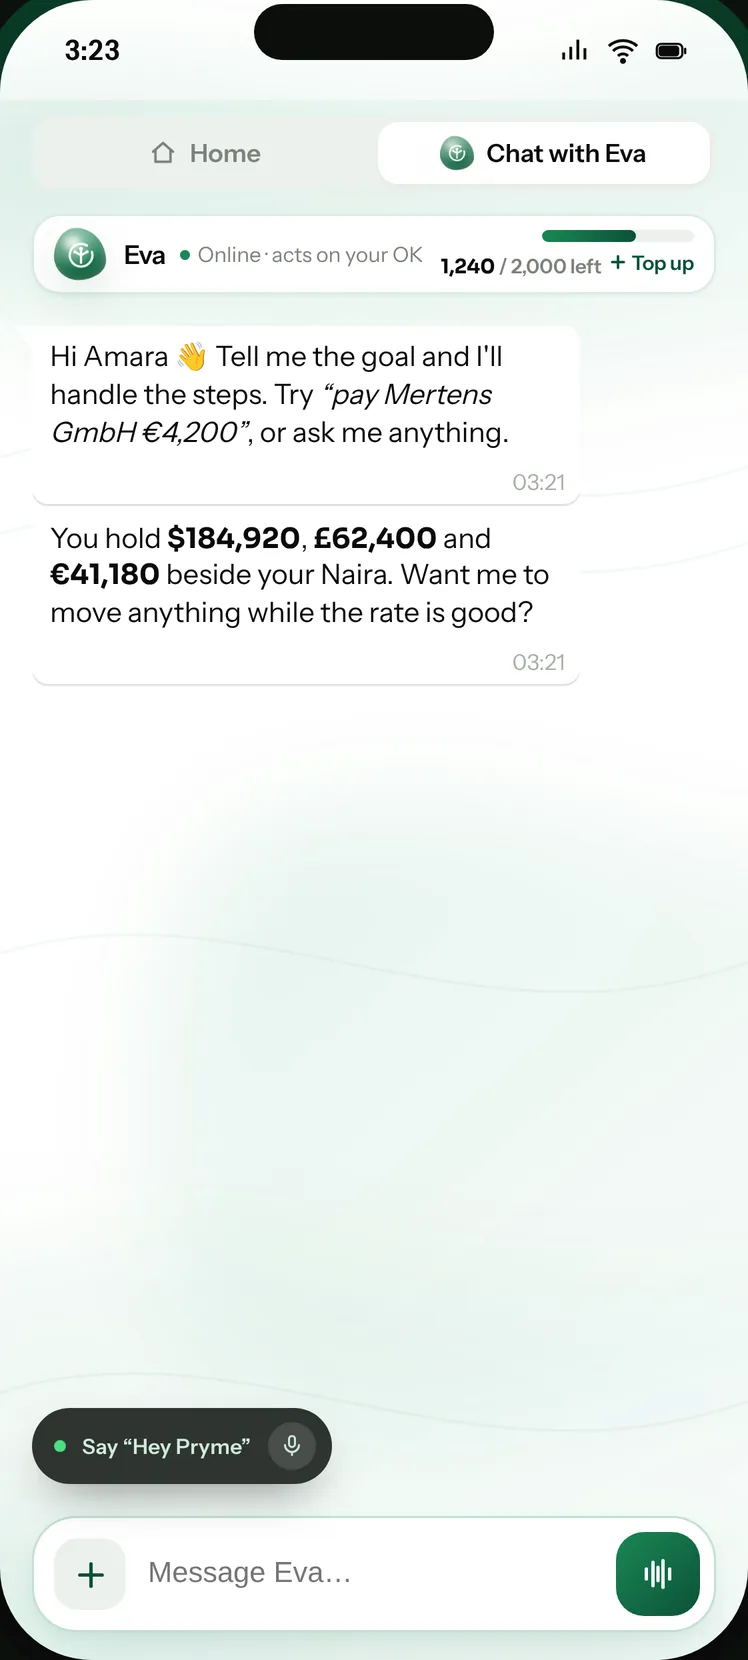
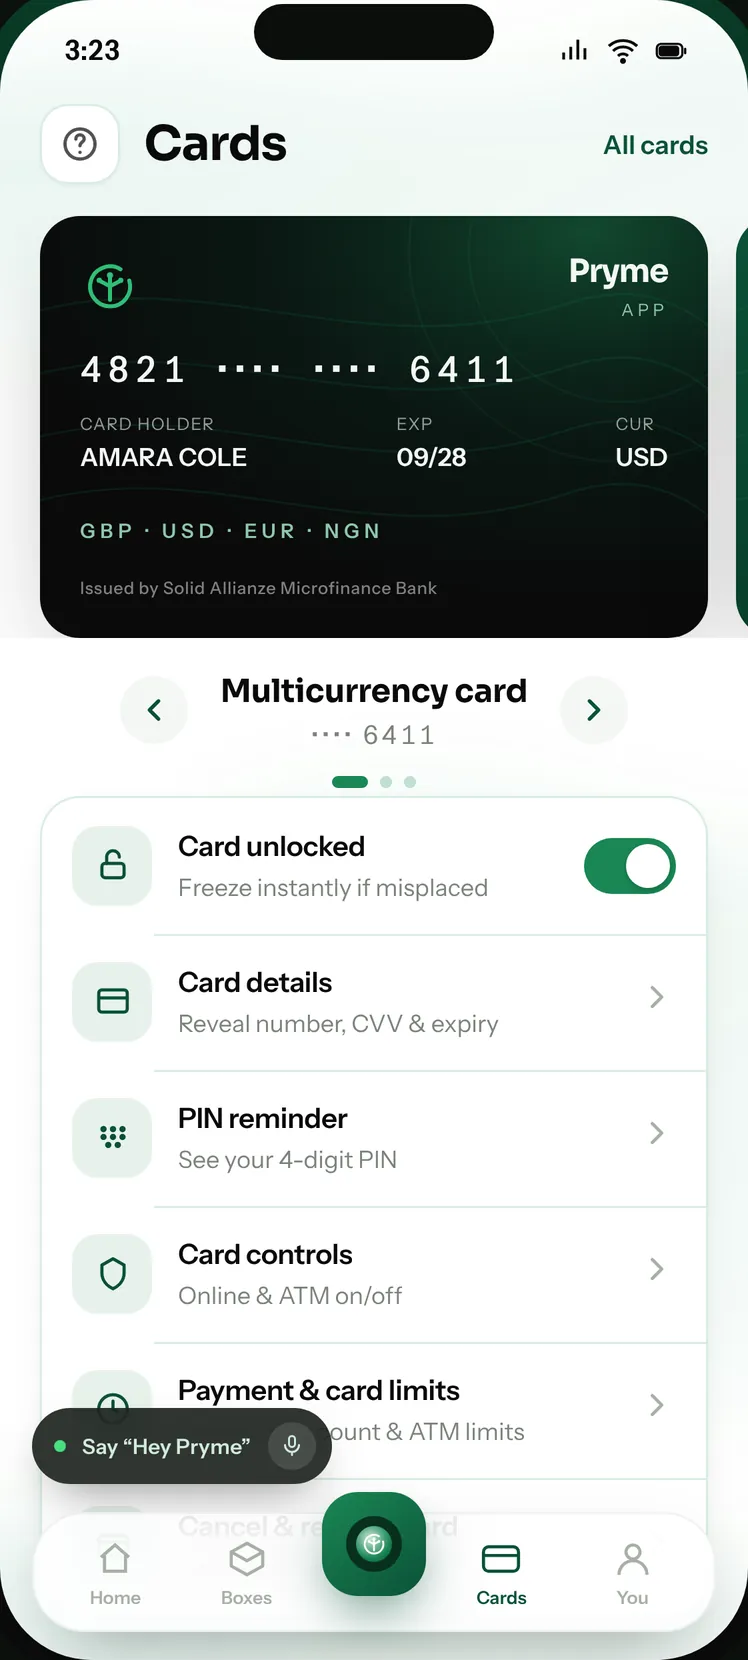
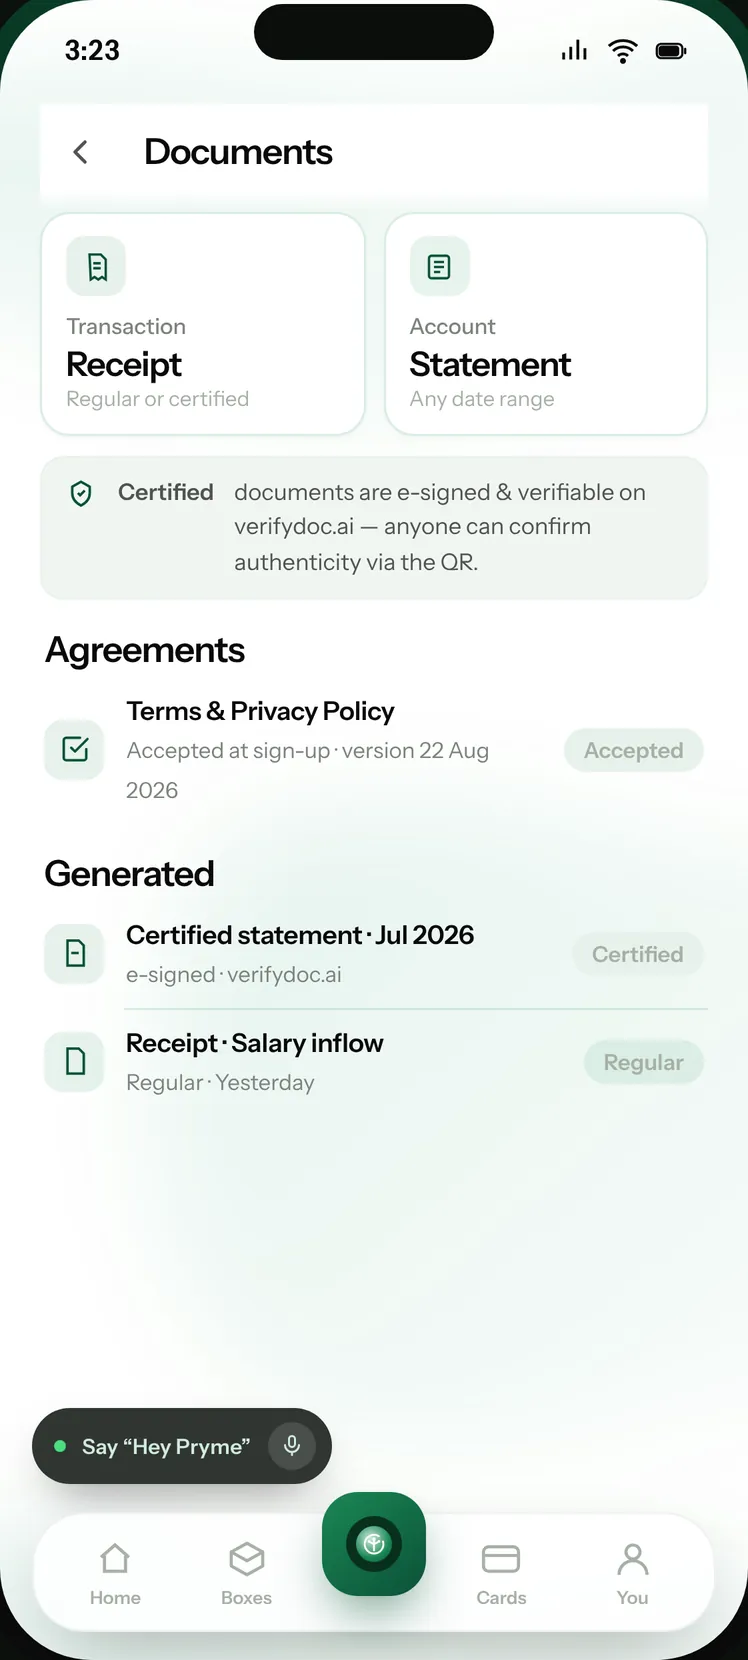
We give you a limit to spend at the shops and services you already use — and an account that works on your month while you get on with it. Dollars, pounds and euros sit beside your Naira, and an assistant handles the running of it, asking you first every single time.
One global account for your money and business. Move across currencies, automate everyday operations and put AI agents to work — with you in control of every important decision.
 Evayour assistant
 DanielChief of Staff
 BenFinance
 BruceCare
Your competitor down the road sells the same thing you sell. The difference is who walks in. We put money in people’s hands that can only be spent in businesses like yours — and then we point them at you.
You are not borrowing. You are selling to somebody who already has the money — and that money can only be spent with a business like yours.
₦100,000 from day one · agreement v2.1 · 12 Aug · View
Eva waits for your rate and asks before she moves anything.
No card, no OTP, nothing for the buyer to type in. They transfer from the bank app they already use, and the money lands in the same account your agents are running — already matched to the order, already in your books.
We give the buyer a one-time account number. They transfer to it from any bank app or by USSD — no card, no OTP, nothing to type in.
Get the account numberTo this account, from any bank app. We watch it, and the page updates itself.
₦26,767.50 from GTBank · John D., matched to order ORD‑1042.
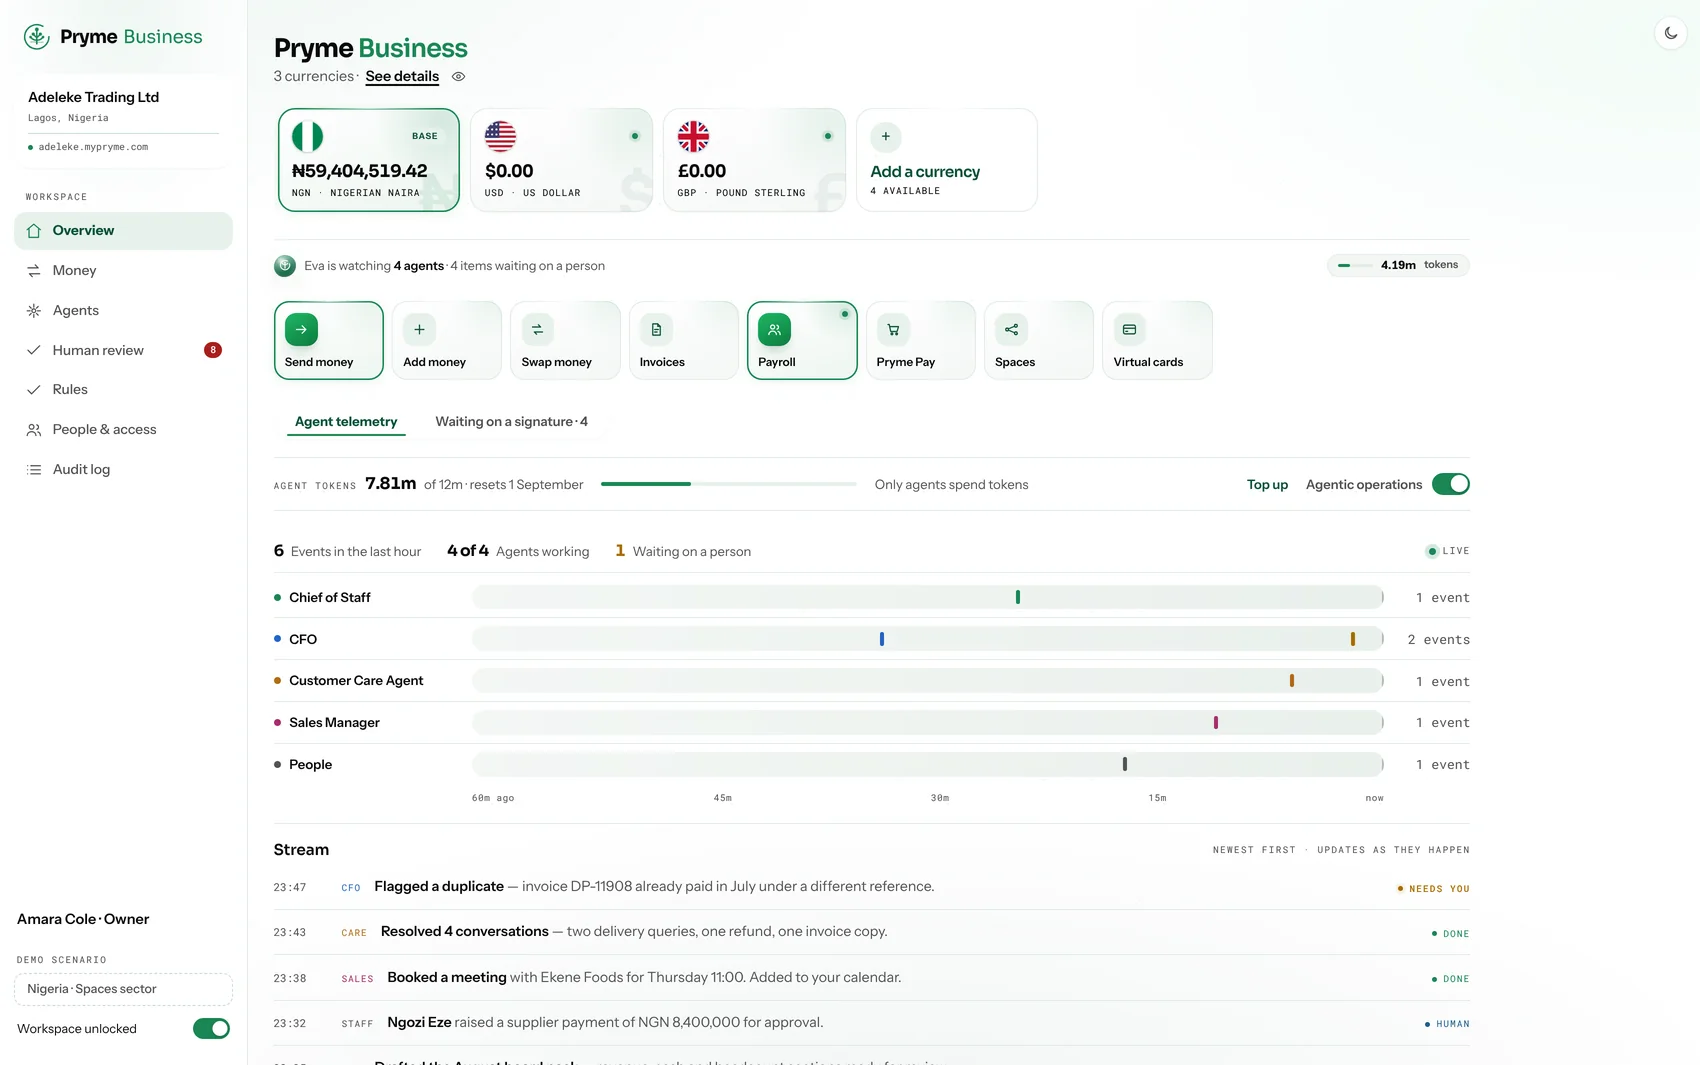
Five agents come with the account. Each one has a job description, a budget and a ceiling you set. They do the work and bring it to you — nothing leaves the account without your signature.
Knows what is stuck, who is waiting and what you promised — and keeps all three moving.
Booked a meeting with John Doe Foods for Thursday 11:00.Keeps the books as you trade and tells you the moment something does not add up.
Flagged a duplicate — invoice DP‑11908 was already paid in July.Holds every filing to its own clock and screens names and payments against your policy — and logs what it refuses.
Screened 412 payments overnight and refused two of them.Goes back to the buyers who went quiet, with the receipt already attached.
Recovered ₦410,000 across three overdue invoices.Replies, follows up on what they asked for and hands you only the ones that need you.
Resolved 4 conversations — two deliveries, one refund.Issue a dedicated Naira account number to each of your own customers, collect into it and reconcile against it. The same rails the Business Account runs on, with the licence behind them.
Dollars, pounds and euros beside a Naira account, on one ledger and one set of books. Five agents come with it and run the account — nothing leaves without your signature.
Five agents come with the account. Each has a job description, a budget and a ceiling you set. They do the work and bring it to you — they propose, you approve.
Knows what is stuck, who is waiting and what you promised, and keeps all three moving.
Booked the quarterly review with your auditor for Thursday.Keeps the books in every currency you hold and flags the moment something does not add up.
Flagged a duplicate — invoice DP‑11908 was already paid in July.Holds every filing to its own clock and screens names and payments against your policy — and logs what it refuses.
Screened 412 payments overnight and refused two of them.Goes back to the buyers who went quiet, with the invoice and the receipt already attached.
Recovered $12,400 across three overdue invoices.Replies, follows up on what they asked for and hands you only the ones that need you.
Resolved 4 conversations — two deliveries, one refund.The business has changed shape four times and never changed what it was rooted in. Each version was built out of what the last one could not do.
An online grocery store, built out of a faulty tab. Selling the food was the easy part — taking the money for it, and moving it, turned out to be the business.
A prepaid card. The first time the company issued rather than resold, and the first time it carried the obligations that come with holding somebody else’s money.
Solid Allianze acquired — an existing bank with an existing licence. The perimeter stopped being someone else’s to draw.
More than one currency on one balance, and the rebrand to Pryme. A Nigerian business could hold dollars without holding a second institution.
Accounts that do the work rather than only hold value. Five agents on the account, inside a policy you write — which is where the new mark starts.
Pryme is a financial technology company. It gives people and businesses in Nigeria one account that holds Naira alongside dollars, pounds and euros, and a set of agents that do the running of it — keeping the books, chasing what is owed, answering customers and paying bills. Nothing leaves an account without the owner’s approval.
Yes. A Pryme account holds Naira, US dollars, pounds sterling and euros side by side on one ledger, each with its own account details — a Nigerian account number, a US account number, a UK sort code and an IBAN for the euro area. You can swap between them at a rate you set, and every currency has its own statement.
Spaces is available in Nigeria. It gives a shopper money to spend that can only be spent with a participating business. The business is paid into its Naira account whether or not the shopper repays, because Pryme carries the credit. For the business it is free to join, there is nothing monthly, and the customer’s identity is never shown — only a reference and what it is worth.
Five agents come with the account. The Chief of Staff runs the week and keeps what is stuck moving. Finance watches the money and keeps the books as you trade. Compliance keeps the filings on time and screens what moves. Sales chases what you are owed. Customer Support answers your customers and follows up. Each has a job description, a budget and a ceiling you set, and each one proposes rather than acts — nothing leaves the account without your signature.
Pryme Pay takes payments on your own site or on a checkout page you control. The buyer is given a one-time account number and transfers to it from any bank app or by USSD — no card, no OTP, nothing to type in. The money lands in the same account your agents are running, already matched to the order and already in your books.
Savings Boxes are separate pots inside a Pryme account, held in Naira. Flexible Boxes can be withdrawn at any time, Fixed Boxes hold to a date, Investment Boxes hold for longer, and Interest-free Boxes earn nothing by design. A business can use them to ring-fence payroll and the tax it withholds, so that money cannot be spent by accident.
Pryme is a financial technology company, not a bank. Accounts and deposits are provided by Solid Allianze Microfinance Bank Limited, which is licensed by the Central Bank of Nigeria and is a member of the Nigeria Deposit Insurance Corporation.
Yes. Pryme Rails lets a platform issue a dedicated Naira account number to each of its own customers, collect into it and reconcile against it, over one API — the same rails the Pryme Business Account runs on.
Pryme is a financial technology company. It gives you one account that holds US dollars, pounds sterling and euros beside Naira, with an assistant that runs the account for you and asks before anything moves. Accounts are provided in Nigeria today, and further markets open as each licence lands.
Accounts are provided in Nigeria today, subject to verification and approval. Foreign-currency balances are held and converted inside that account, so you can hold, receive and swap dollars, pounds and euros wherever you are.
Naira, US dollars, pounds sterling and euros, side by side on one ledger. Each has its own details — a Nigerian account number, a US account number, a UK sort code and an IBAN for the euro area — and each has its own statement.
Swap at a rate you set rather than the rate of the day, then send to any Pryme username or to a Nigerian bank account. There is no fee to send to another Pryme account.
Eva is the assistant inside the Pryme app. She opens accounts, moves money, saves toward your goals, pays what is due and follows up what is owed to you — and asks you before anything moves.
Pryme Rails lets a platform issue a dedicated Naira account number to each of its own customers, collect into it and reconcile against it, over one API — the same rails the Pryme Business Account runs on.
Notes on money that does the work: what we are building, what the regulation actually says, and how we think about letting software act on money. Read the Ledger
What AI agents can do in bookkeeping, close, collections and compliance today, where a person must stay in charge, and how to judge a product.
How multi-currency business accounts work: local details vs SWIFT, payment rails, the real cost of FX, safeguarding vs deposit protection, and hedging.
How UK, US, Canadian and European firms pay Nigerian suppliers and get paid by Nigerian clients: FX, Form A and M, tax, compliance and payout routes.
What it really costs to send money to Nigeria from the UK, US, Canada and Europe: fees, exchange-rate margins, CBN naira rules, BVN, speed and scams.
What AI can and cannot do in day-to-day bookkeeping, how much time it saves on real numbers, and which jobs must stay with you or your accountant.
What we are building, what the regulation actually says, and how we think about letting software act on money.
All of United KingdomSend money home · 186 articles
Most UK transfer apps require senders to be 18. What under-18s can and cannot do, and the safe ways a parent can send the money for them.
The Access Bank UK personal current account: who it is for, its £10 to £30 monthly tiers, SWIFT timings and transfers to Access Bank group accounts.
ACE Money Transfer offers cash pickup in Nigeria but names no pickup partners. What it does name: eight deposit banks and a 1-hour pickup claim.
ACE Money Transfer pays naira into major Nigerian banks and for cash pickup. Its steps, payment methods and the fee pattern its own blog described in 2026.
The UK's APP scam refund rules cover Faster Payments and CHAPS between UK accounts. How that applies when the money ended up in Nigeria.
Which providers list Apple Pay or Google Pay as a way to pay for a UK to Nigeria transfer, what limits apply, and why the card behind it still matters.
Barclays charges no fee for international payments in its app or Online Banking, with a conversion charge of up to 2.75%. How to pay a Nigerian bank.
Barclays lets you choose who pays the charges on an international payment. How the OUR option works for Nigeria, what it costs and where to find it.
Why no time of day reliably beats another for pounds to naira, what does change across the week, and how rate locks and planning help more than timing.
Once a UK bank accepts a SWIFT payment you cannot just cancel it. A recall needs the banks to agree, may cost a fee, and can fail once funds are credited.
The CBN's official rate is the NFEM dollar rate, a volume weighted average. Why UK apps quote a different pound to naira rate, and where to see each live.
On a £100 transfer to Nigeria the fee and the exchange-rate margin together decide the cost. How to compare them on the day you send.
A high-street transfer shop must be on the FCA register as an agent of a named principal. How to check it, what the receipt shows, and warning signs.
Unhappy with a UK money transfer firm? The 15-day and 8-week rules, the 6-month deadline and how to bring a complaint to the ombudsman for free.
UK banks and payment firms must answer payment complaints within 15 business days, or 35 with a holding reply. How to use it, and when to go further.
Confirmation of Payee checks names on UK payments only. What that means for money sent to Nigeria, and how to check a Nigerian account name yourself.
How identity checks on UK remittance apps work now BRPs have gone, what an eVisa share code can and cannot prove, and what to have ready.
Apps collect your pounds locally by Faster Payments and pay out locally in Nigeria; bank SWIFT payments travel through a chain. Why that changes speed.
FirstBank UK's July 2026 current account terms: how to instruct a payment, cut-off times for GBP, EUR and USD, conversion rules and cash limits.
FBN Bank UK's terms set the channels, details and cut-offs for a payment from FirstBank UK online banking to an account in Nigeria. What they say.
Most UK money transfer apps are e-money or payment firms, not banks. Their customer money is safeguarded, not FSCS covered. Here is the difference.
Grey's UK account details take Faster Payments, BACS or CHAPS. How loading pounds first works, what can hold it up, and what Grey's pages leave unsaid.
The FX margin is the mark-up between the rate you get and the mid-market rate. How to measure it in pounds before sending money to Nigeria.
There is no UK income tax relief for supporting family in Nigeria. What GOV.UK does allow, the inheritance tax gift rules, and why records still help.
Family in Lagos asking for dollars? Remittance apps now pay out in naira only. The routes that still deliver dollars, and the cash rules on both sides.
Can't make the wedding? How to send gift money from the UK on time, what the CBN Act says about spraying naira, and why buying new notes is risky.
What Grey's own pages state about receiving pounds, converting to naira and paying out, what they leave out, and the UK authorisation point to check.
GTBank UK sends international payments as Priority Payments over SWIFT. How they work, the 3pm cut-off and where GTBank UK lists the charges.
What Guaranty Trust Bank (UK) says about international payments to Nigeria: account entry costs, SWIFT cut-offs, exchange rates and charges.
App transfers to Nigerian banks often land within minutes; bank SWIFT payments take longer. What speeds a payout up and what holds it back.
HSBC UK charges £5 to send money to a bank outside the EEA, including Nigeria. Here is who pays it, who does not, and what else comes off.
HSBC UK lets you send up to £50,000 online and £10,000 by phone. What that means for large payments to Nigeria and what to do above the limit.
HSBC UK charges £5 for international payments outside the EEA unless you are Premier or use Global Money. Limits, timings and how to pay Nigeria.
Before sending money to Nigeria, check the firm on the FCA register: its status, its permissions, its real company name and the contact details.
Transfer receipts, statements and the reason behind each payment: what to keep when you send money to Nigeria from the UK, for how long and why.
What we could and could not confirm about Kuda’s UK money transfer service in October 2026, how its rate was shown, and what to check before sending.
Why UK banks pause big payments to Nigeria, what they ask about purpose and source of funds, the papers that speed release, and how to complain.
LemFi says a failed transfer is not charged and the money usually returns to your balance right away. Where it goes, how long, and when to contact support.
LemFi names a UK passport or driving licence for UK sign-up, plus a selfie. What its help page says, what it leaves out and how to avoid delays.
LemFi does not publish fixed UK limit figures. Your limit depends on verification level and account type, and the app shows it under Account Limits.
Lloyds charges £9.50 on non-euro international payments. How it applies to Nigeria, the optional £20 correspondent fee and the exchange margin.
Lloyds charges £9.50 for non-euro international payments, with a margin from 3.55% on amounts up to £10,000. Steps, limits and timings for Nigeria.
Measure the margin on any pounds-to-naira quote in four steps: find the mid-market rate, read the app rate, do one division, then add the fee back in.
Asked to receive money in your UK account and send it to Nigeria? How money mule recruitment works, the penalties in the UK, and what to do now.
MoneyGram UK sets 3, 5, 15 and 35 business day stages for complaints, then the Financial Ombudsman. What each stage means for a Nigeria transfer problem.
Collecting MoneyGram cash at a GTBank branch? GTBank says non-customers can collect with valid ID such as BVN or passport; over $200 goes to an account.
MoneyGram sends from the UK online, in its app or at agent locations, paying naira as cash or into Nigerian banks. Steps, payment options and payout rules.
Yes: Monzo sends naira to Nigerian bank accounts. Its own help pages on details needed, the ₦95m per-transfer limit, NIP delivery, fees and recalls.
To pay a Nigerian account from Monzo you need the recipient name, bank name and 10-digit account number. Limits, timing and what to do if it goes wrong.
Your family in Nigeria received less than the quote promised. The usual causes, how to tell which one applies, and what to ask your provider.
A quote is a snapshot. When UK providers fix the naira rate, how long a lock lasts, and the four reasons the payout can come in below what you were shown.
NALA says accounts can send up to £5,000 a day to Nigeria, varying by account and purpose, and that custom limits are offered. How to ask for one.
NALA charges £0.99 on each bank transfer from the UK to Nigeria, and earns a margin in its exchange rate. How to work out the full cost on the day.
What NALA’s own Nigeria page says about the £0.99 bank fee, the rate margin, limits and timing, and how to read the quote before you pay.
Nationwide charges £15 per SWIFT payment, except on some Flex accounts, and its rate includes a 2.2% mark-up. What a Nigeria payment really costs.
Nationwide sends to Nigeria by SWIFT from a current account: £15 on most accounts, a 2.2% currency mark-up, no upper limit and over four working days.
NatWest charges no fee to send abroad online, but adds an exchange margin of up to 3.25%. What that costs on a Nigeria payment and how to check it.
NatWest charges no fee to send an international payment online, applies an FX margin of up to 3.25%, and limits new payees. Steps and timing for Nigeria.
NatWest's cut-off for non-euro payments is 16:00 UK time, with 1 to 3 business days to arrive. How to time a payment to Nigeria around it.
FATF took Nigeria off increased monitoring on 24 October 2025. What that changed in UK money laundering rules, and why apps may still ask questions.
Your provider says paid but the account in Nigeria shows nothing. How to get the session ID, what the bank checks and how to escalate in both countries.
To pay a Nigerian bank account from the UK you need the 10-digit account number, the bank's name and the exact account name. SWIFT adds more.
The session ID is the reference Nigerian banks use to find a NIP transfer. What it is, where UK senders get one and how to use it in a dispute.
NUBAN is Nigeria's 10-digit bank account number standard. How it is built, why its check digit catches typos and why apps ask for it.
What “pay by bank” means on a UK remittance app, how the money moves over Faster Payments, and how its protection differs from a card payment.
Buying prepaid electricity for parents in Nigeria from abroad: the meter details you need, DisCo portals and apps, and what to do if a token will not load.
Why UK card issuers often treat a money transfer as a cash transaction, what that costs in fees and day-one interest, and how a debit card compares.
How the way you pay a UK transfer app changes the fee, the rate and the limit, with what providers' own pages say as at October 2026.
How MoneyGram UK's Pay By Bank works for Nigeria transfers, what you approve in your bank app, and why its first-transfer pricing excludes credit cards.
Your UK app usually keeps working when you land in Lagos. The weak point is the security code. How to plan for codes, data, card fees and naira payments.
Some UK transfer apps take prepaid cards and some do not. What each provider's own page says, as at October 2026, and the checks to expect.
When paying a third party's Nigerian account is fine, why the name you enter must match the account, and the patterns that cause holds.
Some UK personal transfer apps restrict or exclude business payees. What their terms say, as at October 2026, and when a business route is right.
Before paying a Nigerian lawyer from the UK, verify the lawyer and the firm, pay a firm account in the firm's name, and confirm the details by phone.
Why a SWIFT transfer from a UK bank may not reach a Nigerian microfinance bank account, and how local naira payouts over NIP get there instead.
What Paysend's UK site says about fees, rates and paying by card, what we could not confirm for the Nigeria route, and how to read the quote yourself.
Today's pound to naira rate comes in three versions: the official reference, the market mid-rate and your app's rate. Which matters, and where to check.
How a pound to naira quote is built, why a SWIFT payment from a UK bank often lands with fewer naira, and how to compare any two quotes yourself.
Welcome rates and fee-free first transfers from the UK to Nigeria usually apply once. Here is how to price the second transfer before you commit.
LemFi ties limits to your verification level and account type. Where to see your limit, where the upgrade appears, and how to prepare for the extra checks.
What “rate locked for 24 hours” or “guaranteed rate” means on a remittance app, how long locks last, what happens if your payment is late, and the limits.
A transfer to Nigeria failed or was cancelled. What providers say about refund times, how card and bank refunds come back and when to complain.
Family received less than you sent? The cut is often an intermediary SWIFT charge or a conversion, not a Nigerian bank fee. How to find out which.
Three ways to send money home to Nigeria every month from the UK, what a standing order can and cannot do, and why the naira amount changes each time.
Refer-a-friend rewards on UK money transfer apps come with conditions: who counts as new, minimum transfers, limits and expiry. What to read first.
The named recipient collects with valid ID and the transfer reference. What Remitly's UK terms say, the 60-day rule and how to avoid a name mismatch.
Remitly UK refunds its fees if money lands after the time it showed you. What it covers, when it is worth nothing and how to claim within 180 days.
Remitly's UK page for Nigeria shows one fee table, not an Economy and Express split. How speed and price change with the way you pay, and what to check.
Remitly's UK pricing page shows £0.99 below £100 and £0 at £100 or more. How the rate, the promo cap and your payment method change the real cost.
Remitly caps sending over 24 hours, 30 days and 180 days, varying with location and verification. How the windows interact and how to ask for more.
A Remitly transfer under review is held while Remitly checks you, the payment or the recipient. What it means, what you may be asked for and what to do.
UK transfer apps ask where your money came from because anti-money-laundering rules require it. What they look for and which documents usually work.
Family support, gift, education or goods? Why UK transfer apps ask the purpose, what each option signals and how to choose the one that fits.
Report Fraud has replaced Action Fraud. The order to act in after a transfer scam: your bank, the transfer firm, the police report and what to keep.
Revolut's Nigeria page shows an illustrative £1,000 transfer with a £10.40 fee, plus weekend and fair usage fees set by your plan. How to read it live.
Revolut UK pays Nigerian bank accounts in naira; card and wallet payouts are listed as coming soon. Fees by plan, weekend charges and timings.
Revolut sends naira to Nigerian bank accounts using the account number and BIC or SWIFT code. Card and wallet payouts are listed as coming soon.
Someone you met online wants money sent to Nigeria. The warning signs of romance and friendship scams, the checks to make, and where to report in the UK.
Money held by UK payment and e-money firms is safeguarded, not FSCS-protected. What that means for your money and what changed in May 2026.
The full cost of sending £1,000 to Nigeria is the fee plus the exchange-rate margin. A worked example shows how to add the two before you send.
Money transfer apps pay Nigeria in naira only under CBN rules. How dollars can still reach a Nigerian domiciliary account from the UK, and what it costs.
Moving tens of thousands of pounds to Nigeria for a property: bank versus provider routes, the documents to prepare and the risks of splitting.
Glasgow, Aberdeen or Edinburgh: the rules for sending money to Nigeria are UK-wide. What does differ in Scotland, and what stays the same.
Counter options in Birmingham for sending money to Nigeria, how to check an agent is authorised before you hand over cash, and what to bring.
How to find an authorised money transfer agent in Manchester for Nigeria, check it on the FCA register, and avoid cash deals that are not regulated.
A payment to Nigeria from a UK business account is checked as a business payment. What changes: purpose, checks, evidence and record-keeping.
Can you send money to family in Nigeria while claiming Universal Credit? What the capital limits and deprivation rules mean, with a worked example.
Most UK savings accounts cannot make international payments. Why, the exceptions banks state, and the simplest way to get savings to Nigeria.
A burial, a hospital deposit or an emergency at home. Which UK to Nigeria routes can pay out the same day, what slows them and how to avoid delays.
Paying a Lagos supplier from a personal UK remittance app? How purpose choices, provider terms and payout rules decide which route is right.
Funding a transfer to Nigeria from a UK joint account: whose ID the provider checks, whose card to use, and how to answer source-of-funds questions.
No rule we found stops students sending money home, but verification, source of funds and visa conditions on work and self-employment still matter.
How a weekend or UK bank holiday affects paying a transfer firm, the naira payout in Nigeria, and the rate you get, with the remaining 2026 dates.
Cash pick-up and mobile wallet payouts from the UK, the CBN naira-only rule, the $200 cash threshold reported in 2024, and what the recipient must bring.
All BRPs have now expired. What UK transfer firms list as accepted ID, why an eVisa alone may not pass, and what to use if your passport is away.
A friend gives you cash to send to Nigeria through your app. Why that makes you the sender on record, what providers check, and safer ways to help.
Counter services for Nigeria in London: how to find a real agent of a licensed firm, what to bring, and how the naira is paid out at the other end.
School fees and a monthly allowance need different routes. How to pay a Nigerian university from the UK, fund a student's account and keep proof.
How UK providers reach OPay and PalmPay: by the wallet’s ten-digit account number as a bank payout, or by phone number as a wallet payout.
A valid Nigerian passport is accepted ID at the main UK transfer providers. The harder part is proving a UK address. What each lists, and what to use.
Topping up a parent's MTN, Airtel or Glo line from abroad: international top-up apps, gifting from your own line and keeping your Nigerian number alive.
Naira-only payout since 2024, the CBN’s May 2026 settlement rule, the reported $200 cash threshold, and what your recipient takes to the agent.
How to send pounds from the UK so they arrive as pounds in a Nigerian GBP domiciliary account: the SWIFT details, the correspondent bank and the charges.
Large transfers to Nigeria attract source of funds checks. The documents banks and transfer firms usually ask for at £20,000 and above, and why.
On £50, a flat fee can cost more than the whole exchange margin. How the two compare on small transfers to Nigeria and how to judge the total.
At £500, the fee and the exchange margin carry similar weight. How to split the cost of a £500 transfer to Nigeria and compare offers on the day.
At £5,000, UK banks and money transfer firms often ask who you are paying, why, and where the money came from. What to expect and how to prepare.
Small gifts lose most to fixed fees and FX margins. How to send birthday money from the UK cheaply, and whether to pay the parent or a child's own account.
Holding euros in the UK? Sending them to Nigeria can save a conversion or add one. When EUR helps, when it costs more, and a worked example in naira.
Funding a car in Nigeria from the UK? Keep proof of where the money came from, who received it, what was bought and the vehicle papers, on both sides.
UK children's accounts are spending cards run by a parent, not payment accounts. Who can send money abroad, and why a teen's account must not be used.
Google Pay is a way to pay for a transfer, not a transfer service. Which providers list it for UK senders as at October 2026, and what to check.
Send at 11pm and many apps pay out in minutes over Nigeria's NIP system, while bank SWIFT payments wait for business hours. What decides it, and cut-offs.
Apps and FCA rules work the same in Northern Ireland as in the rest of the UK. Cash declaration rules and bank holidays are where it differs.
Most UK credit unions focus on savings and loans, not overseas payments. Here is how members usually get money to Nigeria and what to check.
Graduate visa holders face no special limit on money sent home. What decides your transfer is ID, where the money came from and how the provider prices it.
From completion day to the Nigerian account: how house sale money moves from solicitor to bank to Nigeria, how long it takes and what avoids holds.
Acting for a parent under an LPA? What GOV.UK says an attorney may pay to family in Nigeria, what needs the Court of Protection, and the records to keep.
A pending visa extension does not stop you sending money home. What matters is valid ID, an eVisa share code and how each provider checks status.
When the account in Nigeria is joint, which name to type in your UK app, how the Nigerian name check sees it, and what to keep as proof.
If you send sterling to a USD domiciliary account, the Nigerian bank has to convert it or send it back. What that costs and how to avoid it.
USDT or USDC to family in Lagos can look quick and cheap. The FCA warnings, the missing FOS and FSCS cover, UK bank limits and the tax point to know first.
Taking a pension lump sum and sending it home: the tax already deducted, the evidence providers ask for, and how to move a large sum safely.
Sendwave's UK-to-Nigeria page lists cash pickup at Access, Zenith and Fidelity with an SMS voucher code and a password. How to set it up so it works.
Sendwave shows per-day and per-month limits under My Limits in the app menu, and says they may rise as your account ages. How to read and plan around them.
Sendwave's UK-to-Nigeria page says debit cards only, no credit cards or PayPal. Why your card was refused and what to check before trying again.
Sendwave sends naira from a UK debit card to Nigerian accounts and for cash pickup at three banks. Steps, costs and limits as its own page states.
Starling's international payments cover 34 countries, and Nigeria was not on its fee table in October 2026. What that means and what to use instead.
Starling's international payments page lists 34 countries and Nigeria is not one of them. Why you cannot find it, and the options that do reach Nigeria.
A declined card on Taptap Send is usually your bank, the card type, a name mismatch or an unfinished 3D Secure check. How to tell which and fix it.
Taptap Send pays naira to Nigerian bank accounts and mobile money, funded by a UK debit card. The steps, what its pages say about fees and limits.
A fresh selfie request is part of ongoing monitoring under UK anti-money laundering rules. Why it happens, how to pass it, and how to spot a fake request.
A payslip request is a source-of-funds check required by UK anti-money laundering rules. Here is why it happens and which documents usually clear it.
Your app says paid, but your family sees nothing. Get the reference or NIP session ID, let the recipient's bank trace it, and escalate in the right order.
A transfer to Nigeria stuck on pending usually means a check, a funding problem or a payout query. How to find out which, and how to escalate.
UBA UK serves corporates and institutions, not personal remitters. What its site and March 2026 fee schedule say, and the routes that fit individuals.
The naira figure on your quote is the mid-market rate, minus a margin, after a fee. How each part works, and a worked example you can redo on any app.
Why UK banks question payments to Nigeria, why the true answer protects you, and the evidence that clears a held payment quickly.
Why UK banks stop payments linked to Nigeria, what the fraud team will ask, how to get a real payment released, and when a block is protecting you.
A call about your Nigeria transfer may be your bank or a scammer using its name. How to check safely: hang up, call 159 or the card number, then decide.
Sending a SWIFT payment from a UK bank to Nigeria: the details you need, the OUR, SHA and BEN charge options, and why intermediary fees appear.
Nigeria is off the FATF grey list, yet UK banks still pause payments. The rules, the fraud data and the protections that end at the border explain why.
If a UK transfer firm fails, FSCS does not cover you. Your money should be safeguarded and returned by an administrator, but it can be slow and smaller.
Limits on UK to Nigeria transfers come from providers and banks, not a UK legal cap. How tiered limits work and how to raise yours.
Mother, friend, supplier or someone you met online? Why UK transfer apps ask how you know the recipient and how the answer feeds anti-fraud checks.
Sending taxed income to family in Nigeria is not taxed again, but HMRC cares where the money came from. Gifts, inheritance tax and Nigerian income.
A transfer to Nigeria returned to you usually points to a name mismatch, an invalid or closed account, or a failed compliance check. What to do next.
Where to find the MTCN or app reference, what each tracking status means, and when a UK to Nigeria transfer is late enough to chase.
How Nigeria’s name enquiry check works, why surname order, middle names and nicknames trip it, and what to do when a UK transfer is held or returned.
If cash sent by Western Union from the UK is not collected in Nigeria within 42 days it can be cancelled and refunded in 5 to 7 business days. What to do.
Western Union UK names the provisional licence as accepted ID; others say less. Where a provisional licence works, and when to use a passport instead.
A Western Union transfer to Nigeria showing On hold means checks are under way. What its GB FAQ says, what details to have ready, and how to clear it.
You can pay cash at a UK Western Union agent and have naira collected or paid into a Nigerian account. ID needed, payout options and the rules in Nigeria.
Western Union UK scans your ID at agents from £800 and asks online senders to verify at £800. What it accepts, and why a BRP or eVisa is not on its list.
Western Union online lets you pay by bank, card or Apple Pay and send naira to a Nigerian account. How to do it and how its price is shown before you pay.
Lost the MTCN for a Western Union transfer to Nigeria? Its GB FAQ lets you track by sender phone number or both names plus the date. Steps and limits.
How to find a counter in Cardiff that can send money to Nigeria, check it is a registered agent, and what to bring, as at October 2026.
Finding a counter in Glasgow with official locators, the ID providers accept, and the Scottish holidays that can slow a transfer.
Using official agent locators in Leeds and checking the counter is on the FCA register before you hand over cash for Nigeria.
Yes: Wise sends naira to Nigerian bank accounts from the UK at the mid-market rate plus a shown fee. What its pages say it supports and does not.
WorldRemit's UK FAQ caps card and Apple Pay at £8,000 per transaction and £50,000 a day; bank transfer goes to £100,000. Choosing for a large sum.
WorldRemit pays mobile money to the receiver's registered wallet number. What the receiver needs, how to check Nigeria offers it and what can go wrong.
WorldRemit asked for proof of address? Its UK FAQ accepts UK utility bills and bank statements under six months old. Here is what passes and what fails.
WorldRemit pays naira into Nigerian bank accounts, up to an hour per its page. The steps from the UK, how its fee and rate are shown, and what delays it.
WorldRemit says refunds usually take up to 7 working days after cancellation. Why transfers to Nigeria get cancelled, and how to cancel or chase a refund.
Zenith Bank (UK) publishes no personal tariff for payments to Nigeria. What its site does say, who to ask, and how to price a payment before you send.
You can add the other type later — many of our customers hold both.
The business first, then you. Nothing is submitted until you review it.
Ideal customer profiles
Generated from your website by VerifiedLead.ai
Pick the ones that look right. Your Sales agent works these first, and you can change them at any time after opening.
We ask this because you have not given us a website. It helps us set the right limits from day one.
Which of these represents you?
Officers listed against this company on the UK register.
We have sent a six-digit code to your email address. Enter it below to confirm the address is yours.
Wrong address? Go back and change it — nothing is created until this step passes. We never ask for a code by phone or email; anyone who does is not us.
Last step. Each time you sign in we email you a six-digit code — we never send codes by SMS.