AI agents for business finance: what they can and can't do
What AI agents can do in bookkeeping, close, collections and compliance today, where a person must stay in charge, and how to judge a product.
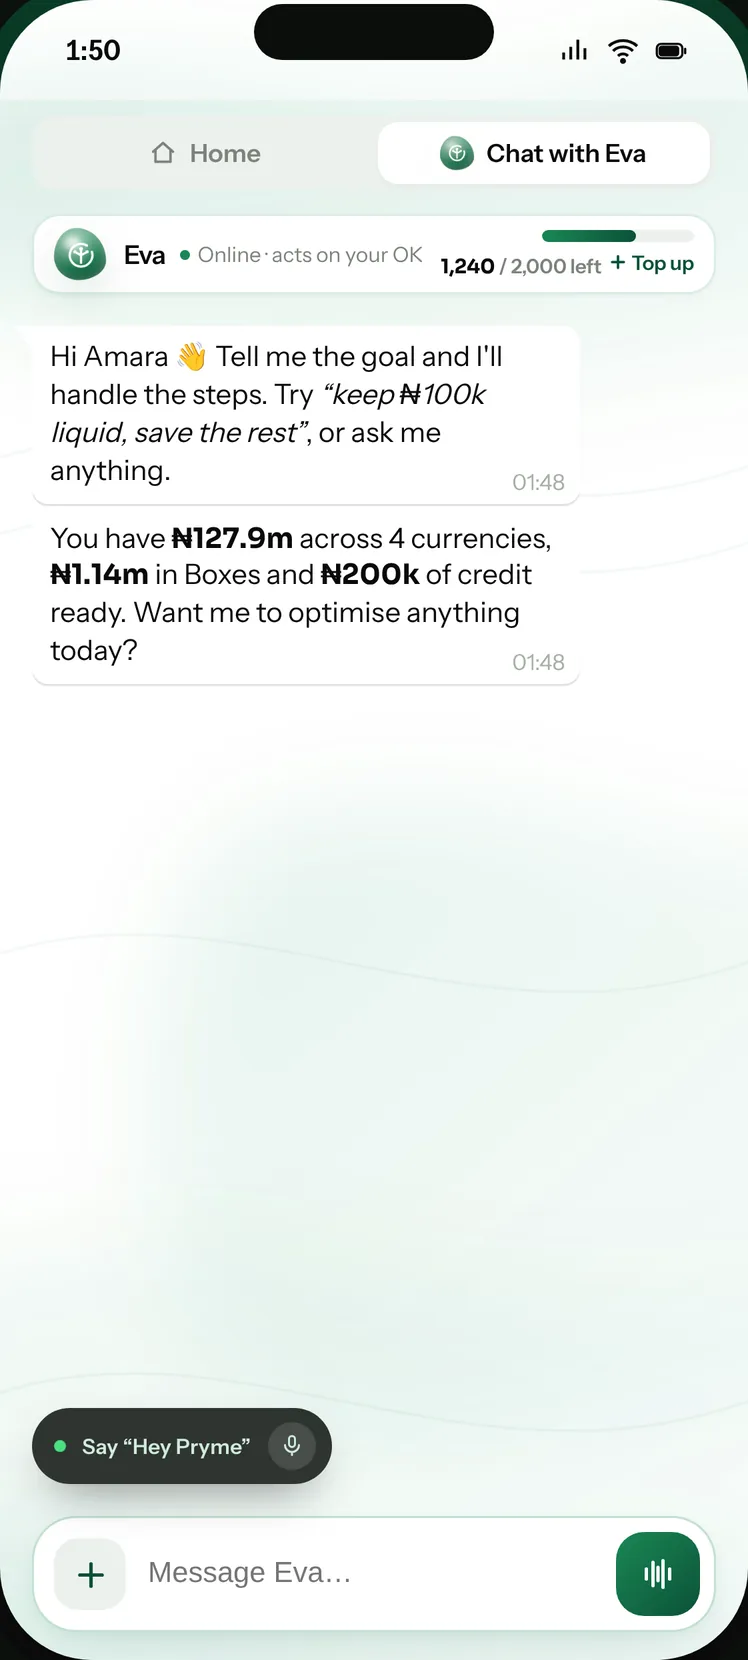
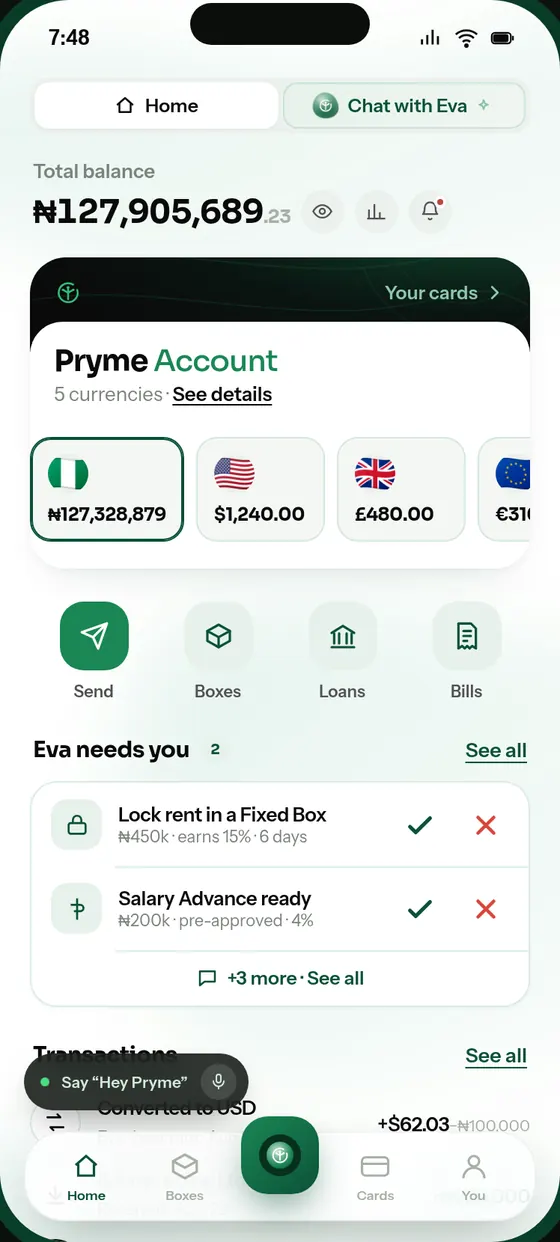
Meet Eva, the assistant inside the Pryme app. She opens accounts, moves money, saves toward your goals and follows up. Nothing leaves your account without your approval.
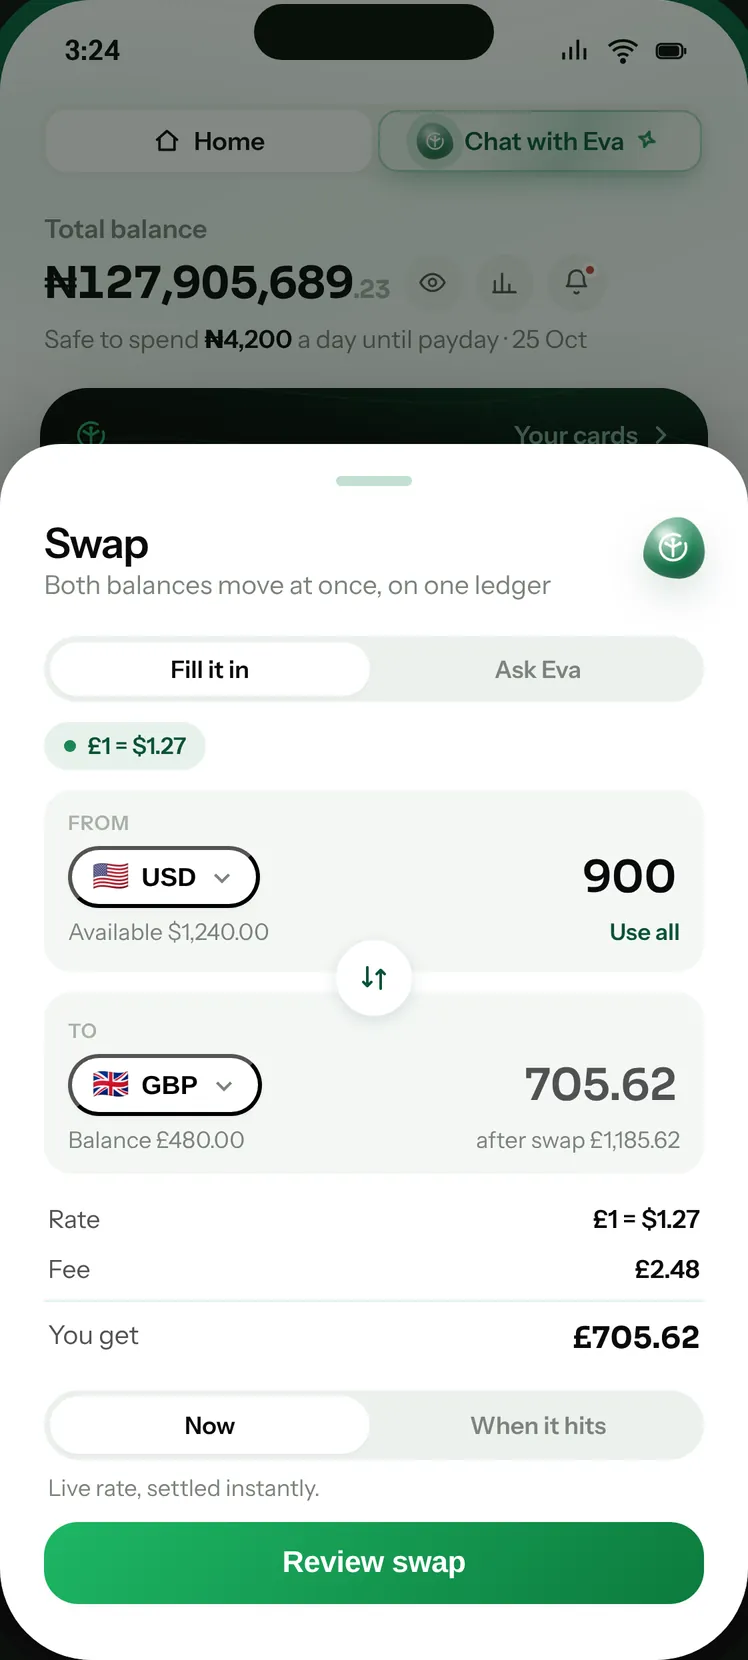
Meet Eva, the assistant inside the Pryme app. She holds dollars, pounds, euros and Naira side by side, swaps at a locked rate, pays bills in any of them and sends anywhere, asking before anything moves.
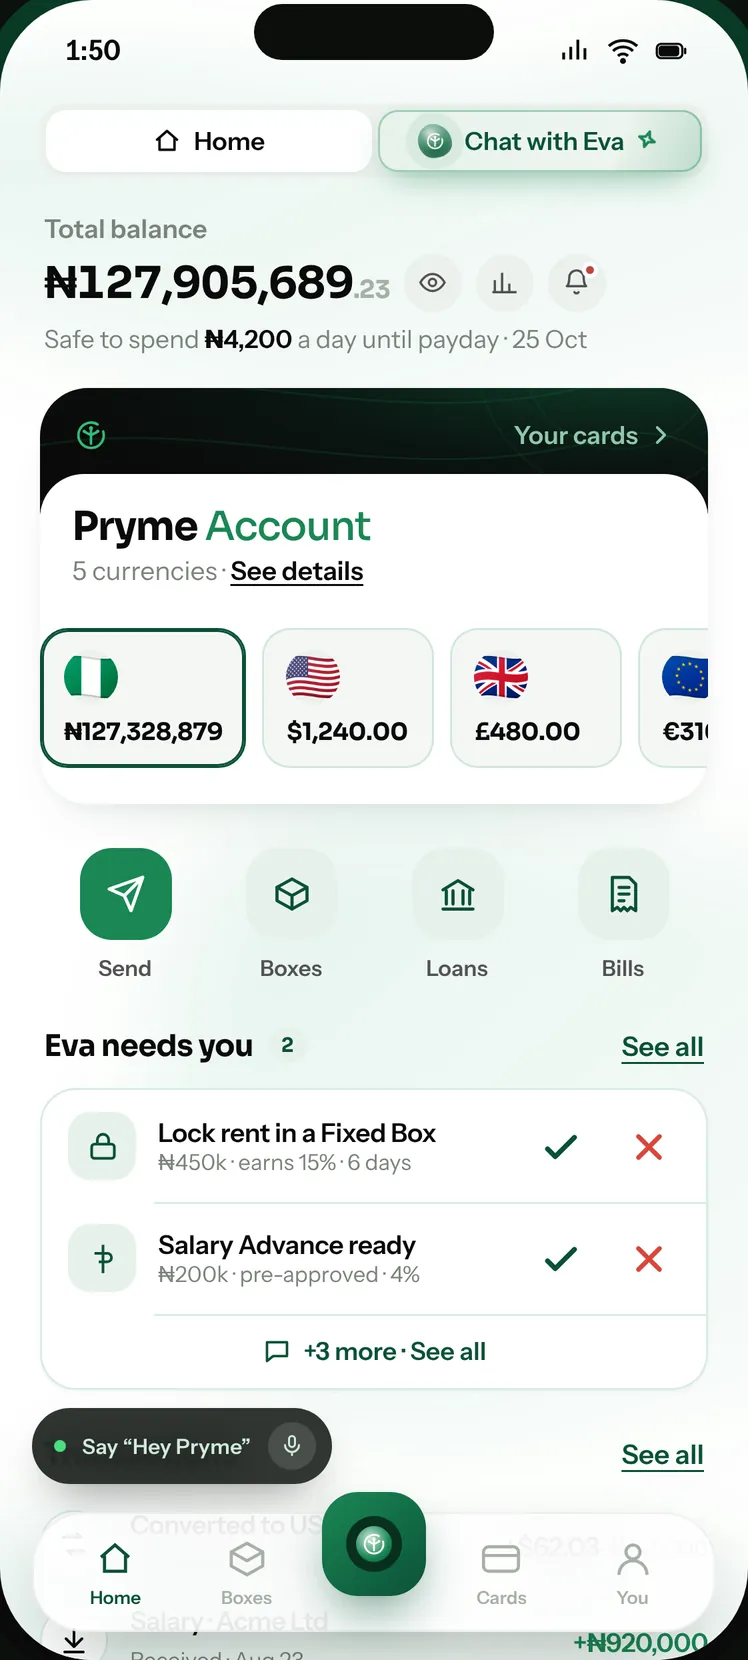
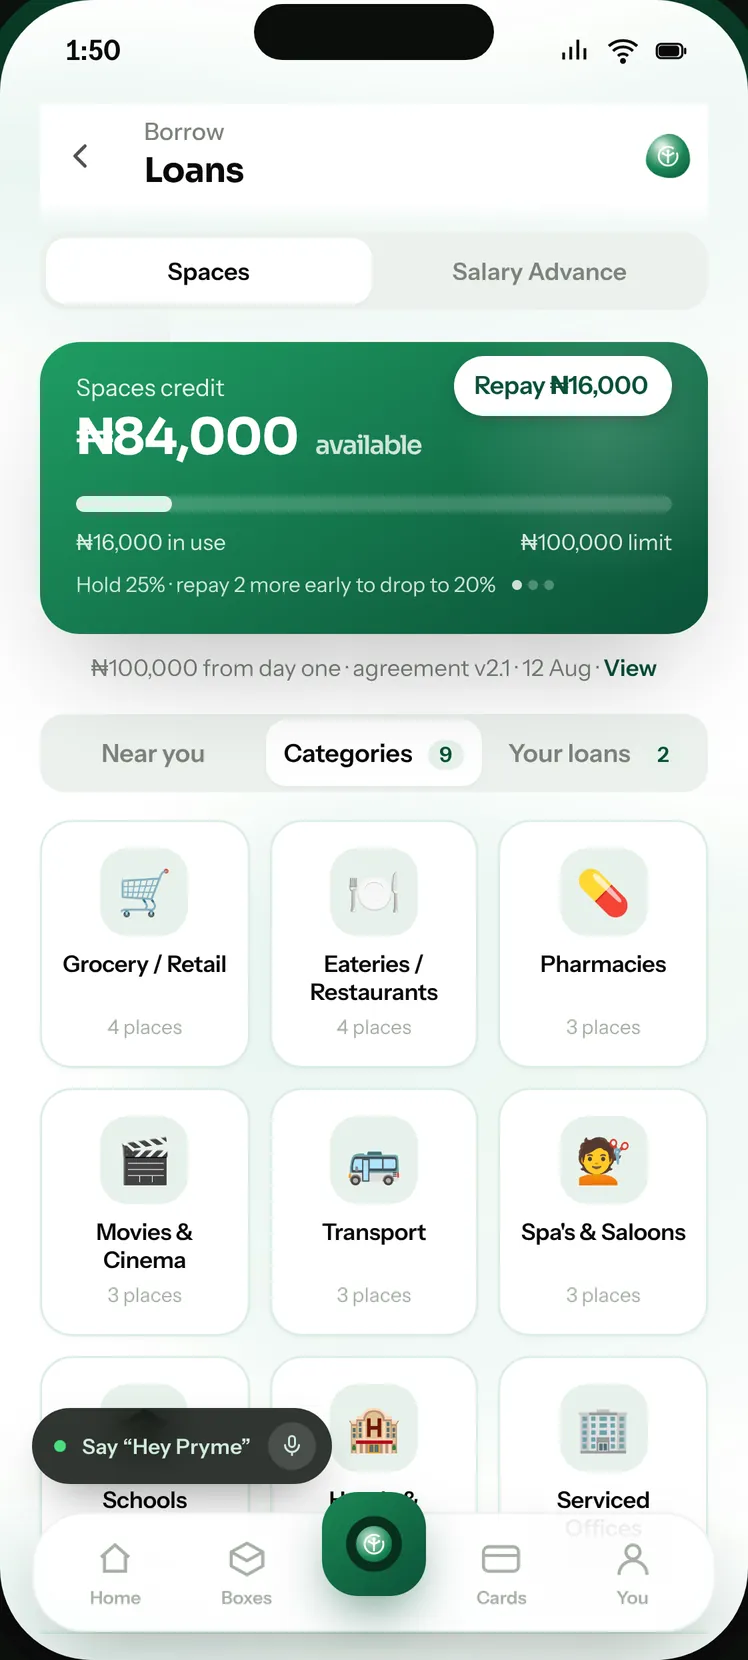
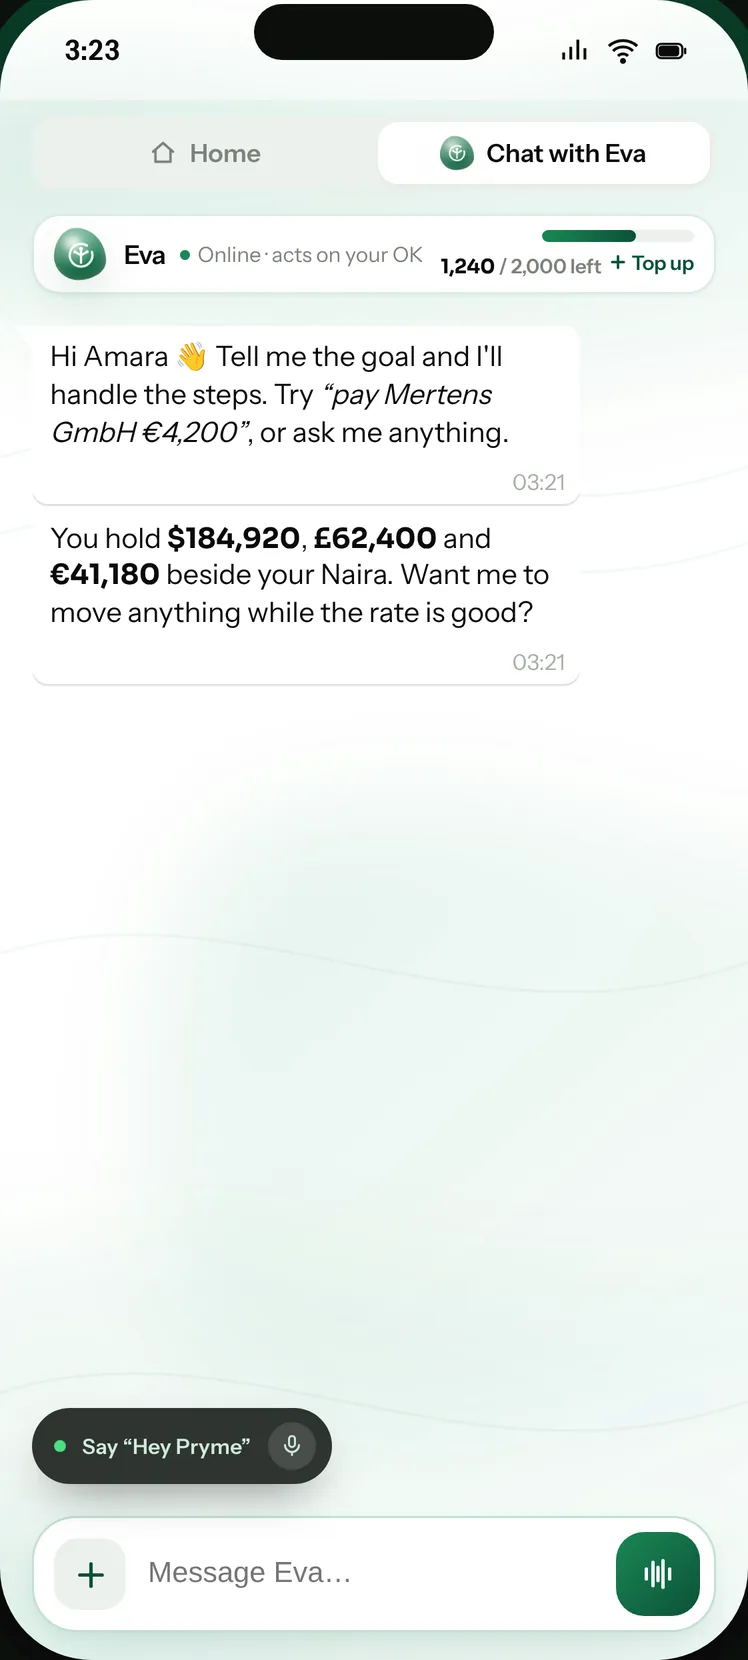
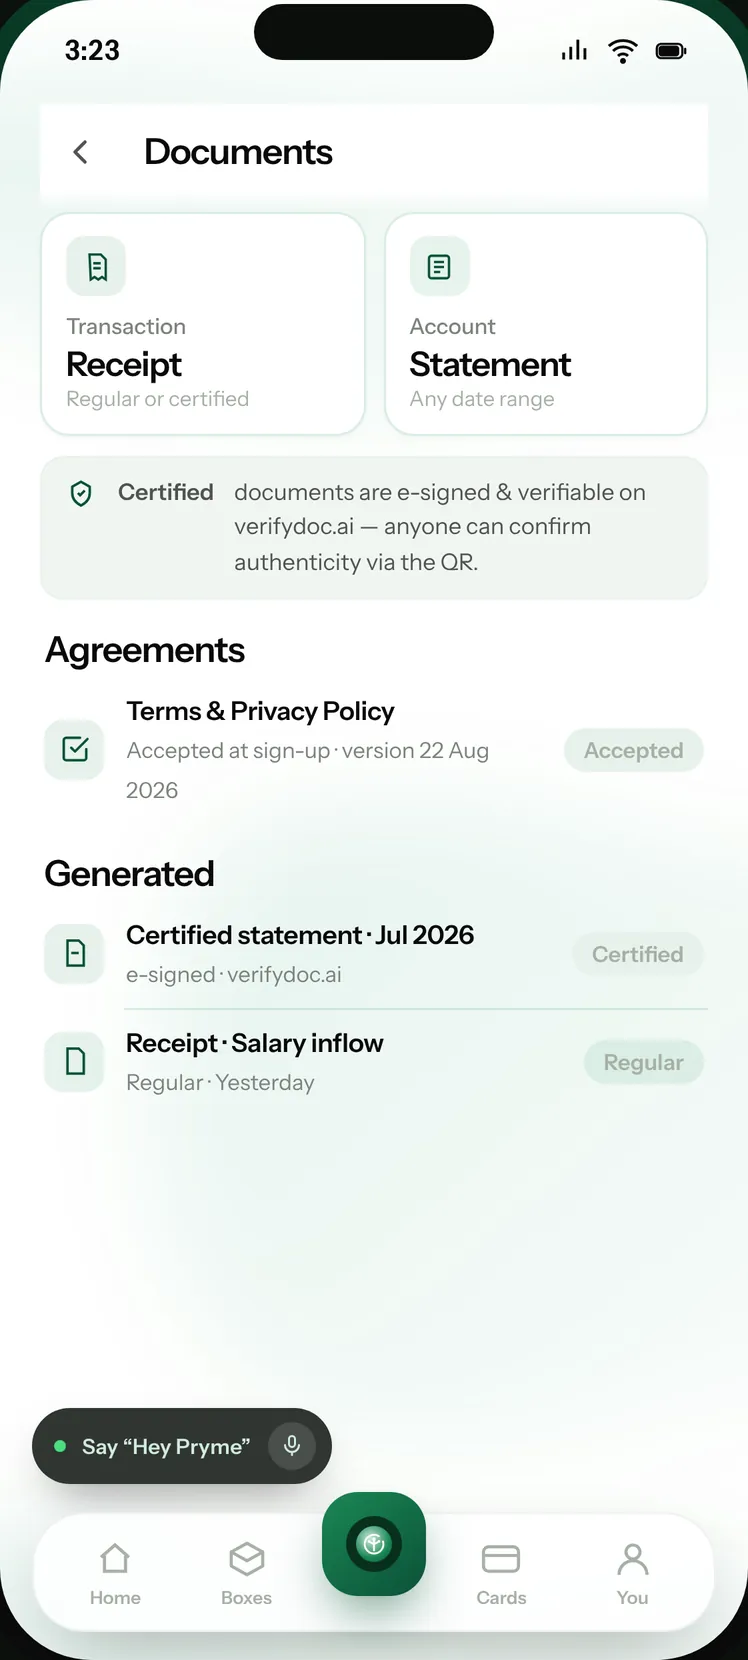
We give you a limit to spend at the shops and services you already use — and an account that works on your month while you get on with it. Dollars, pounds and euros sit beside your Naira, and an assistant handles the running of it, asking you first every single time.
One global account for your money and business. Move across currencies, automate everyday operations and put AI agents to work — with you in control of every important decision.
 Evayour assistant
 DanielChief of Staff
 BenFinance
 BruceCare
Your competitor down the road sells the same thing you sell. The difference is who walks in. We put money in people’s hands that can only be spent in businesses like yours — and then we point them at you.
You are not borrowing. You are selling to somebody who already has the money — and that money can only be spent with a business like yours.
₦100,000 from day one · agreement v2.1 · 12 Aug · View
Eva waits for your rate and asks before she moves anything.
No card, no OTP, nothing for the buyer to type in. They transfer from the bank app they already use, and the money lands in the same account your agents are running — already matched to the order, already in your books.
We give the buyer a one-time account number. They transfer to it from any bank app or by USSD — no card, no OTP, nothing to type in.
Get the account numberTo this account, from any bank app. We watch it, and the page updates itself.
₦26,767.50 from GTBank · John D., matched to order ORD‑1042.
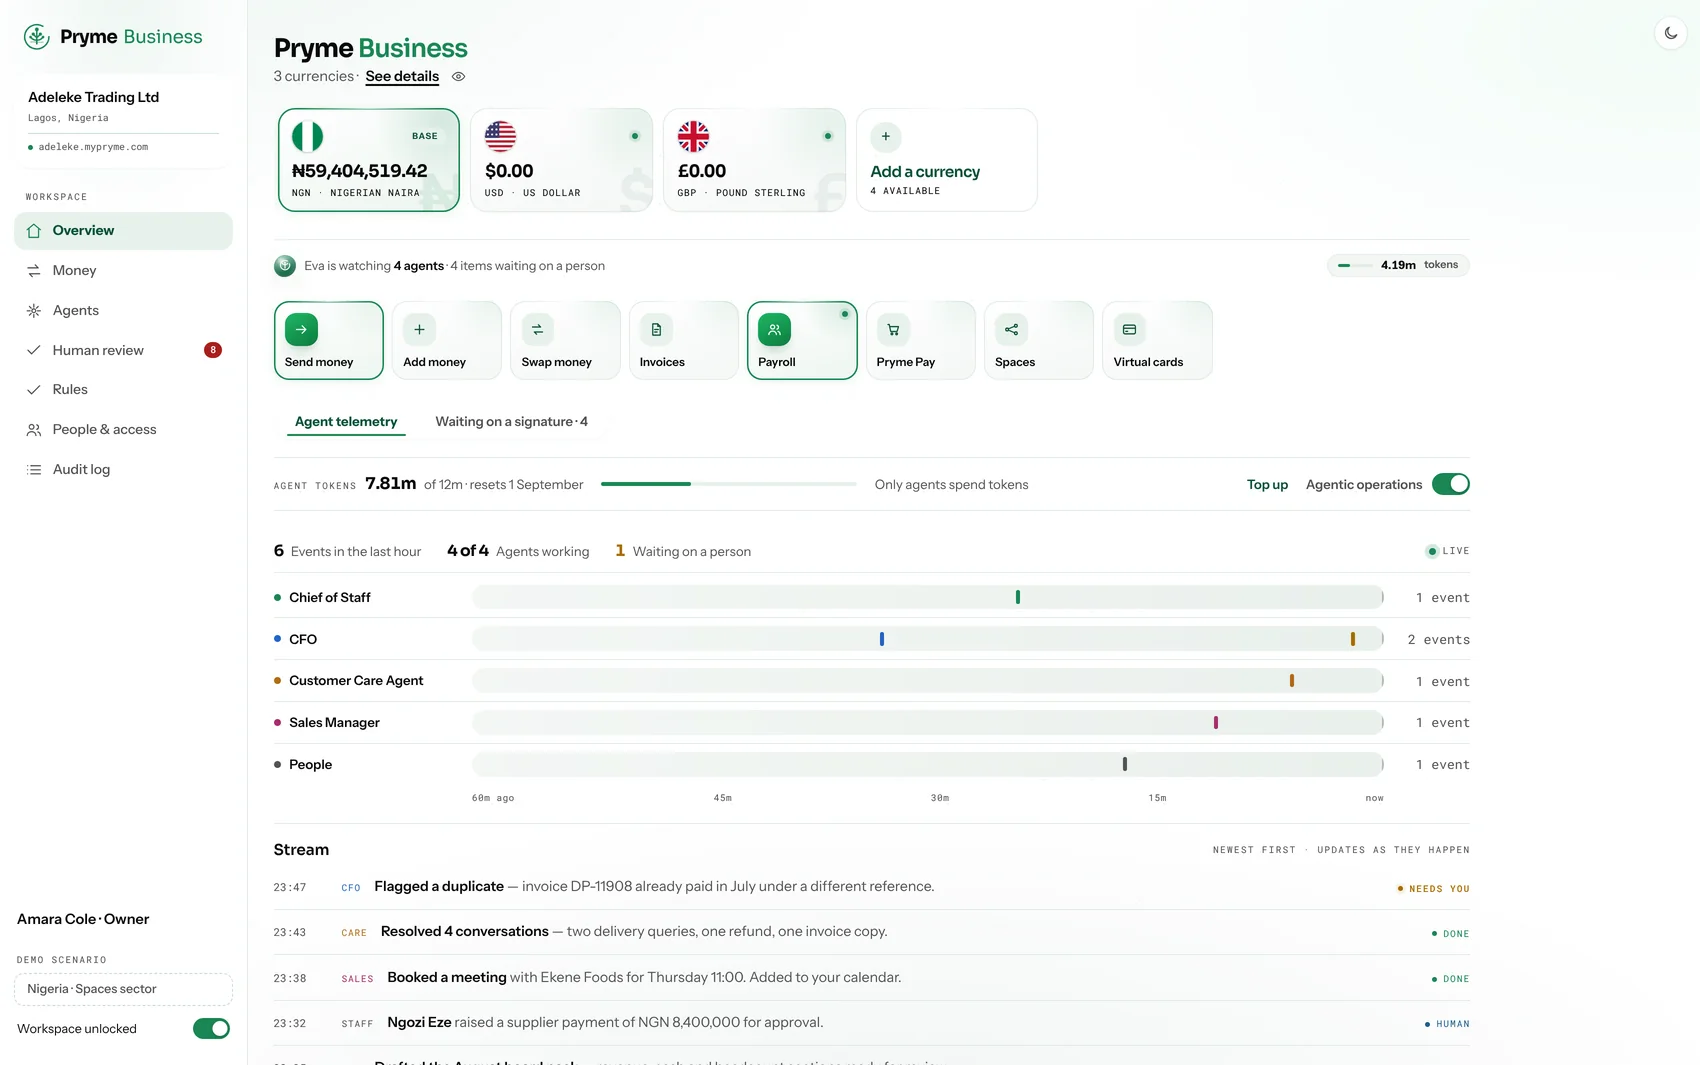
Five agents come with the account. Each one has a job description, a budget and a ceiling you set. They do the work and bring it to you — nothing leaves the account without your signature.
Knows what is stuck, who is waiting and what you promised — and keeps all three moving.
Booked a meeting with John Doe Foods for Thursday 11:00.Keeps the books as you trade and tells you the moment something does not add up.
Flagged a duplicate — invoice DP‑11908 was already paid in July.Holds every filing to its own clock and screens names and payments against your policy — and logs what it refuses.
Screened 412 payments overnight and refused two of them.Goes back to the buyers who went quiet, with the receipt already attached.
Recovered ₦410,000 across three overdue invoices.Replies, follows up on what they asked for and hands you only the ones that need you.
Resolved 4 conversations — two deliveries, one refund.Issue a dedicated Naira account number to each of your own customers, collect into it and reconcile against it. The same rails the Business Account runs on, with the licence behind them.
Dollars, pounds and euros beside a Naira account, on one ledger and one set of books. Five agents come with it and run the account — nothing leaves without your signature.
Five agents come with the account. Each has a job description, a budget and a ceiling you set. They do the work and bring it to you — they propose, you approve.
Knows what is stuck, who is waiting and what you promised, and keeps all three moving.
Booked the quarterly review with your auditor for Thursday.Keeps the books in every currency you hold and flags the moment something does not add up.
Flagged a duplicate — invoice DP‑11908 was already paid in July.Holds every filing to its own clock and screens names and payments against your policy — and logs what it refuses.
Screened 412 payments overnight and refused two of them.Goes back to the buyers who went quiet, with the invoice and the receipt already attached.
Recovered $12,400 across three overdue invoices.Replies, follows up on what they asked for and hands you only the ones that need you.
Resolved 4 conversations — two deliveries, one refund.The business has changed shape four times and never changed what it was rooted in. Each version was built out of what the last one could not do.
An online grocery store, built out of a faulty tab. Selling the food was the easy part — taking the money for it, and moving it, turned out to be the business.
A prepaid card. The first time the company issued rather than resold, and the first time it carried the obligations that come with holding somebody else’s money.
Solid Allianze acquired — an existing bank with an existing licence. The perimeter stopped being someone else’s to draw.
More than one currency on one balance, and the rebrand to Pryme. A Nigerian business could hold dollars without holding a second institution.
Accounts that do the work rather than only hold value. Five agents on the account, inside a policy you write — which is where the new mark starts.
Pryme is a financial technology company. It gives people and businesses in Nigeria one account that holds Naira alongside dollars, pounds and euros, and a set of agents that do the running of it — keeping the books, chasing what is owed, answering customers and paying bills. Nothing leaves an account without the owner’s approval.
Yes. A Pryme account holds Naira, US dollars, pounds sterling and euros side by side on one ledger, each with its own account details — a Nigerian account number, a US account number, a UK sort code and an IBAN for the euro area. You can swap between them at a rate you set, and every currency has its own statement.
Spaces is available in Nigeria. It gives a shopper money to spend that can only be spent with a participating business. The business is paid into its Naira account whether or not the shopper repays, because Pryme carries the credit. For the business it is free to join, there is nothing monthly, and the customer’s identity is never shown — only a reference and what it is worth.
Five agents come with the account. The Chief of Staff runs the week and keeps what is stuck moving. Finance watches the money and keeps the books as you trade. Compliance keeps the filings on time and screens what moves. Sales chases what you are owed. Customer Support answers your customers and follows up. Each has a job description, a budget and a ceiling you set, and each one proposes rather than acts — nothing leaves the account without your signature.
Pryme Pay takes payments on your own site or on a checkout page you control. The buyer is given a one-time account number and transfers to it from any bank app or by USSD — no card, no OTP, nothing to type in. The money lands in the same account your agents are running, already matched to the order and already in your books.
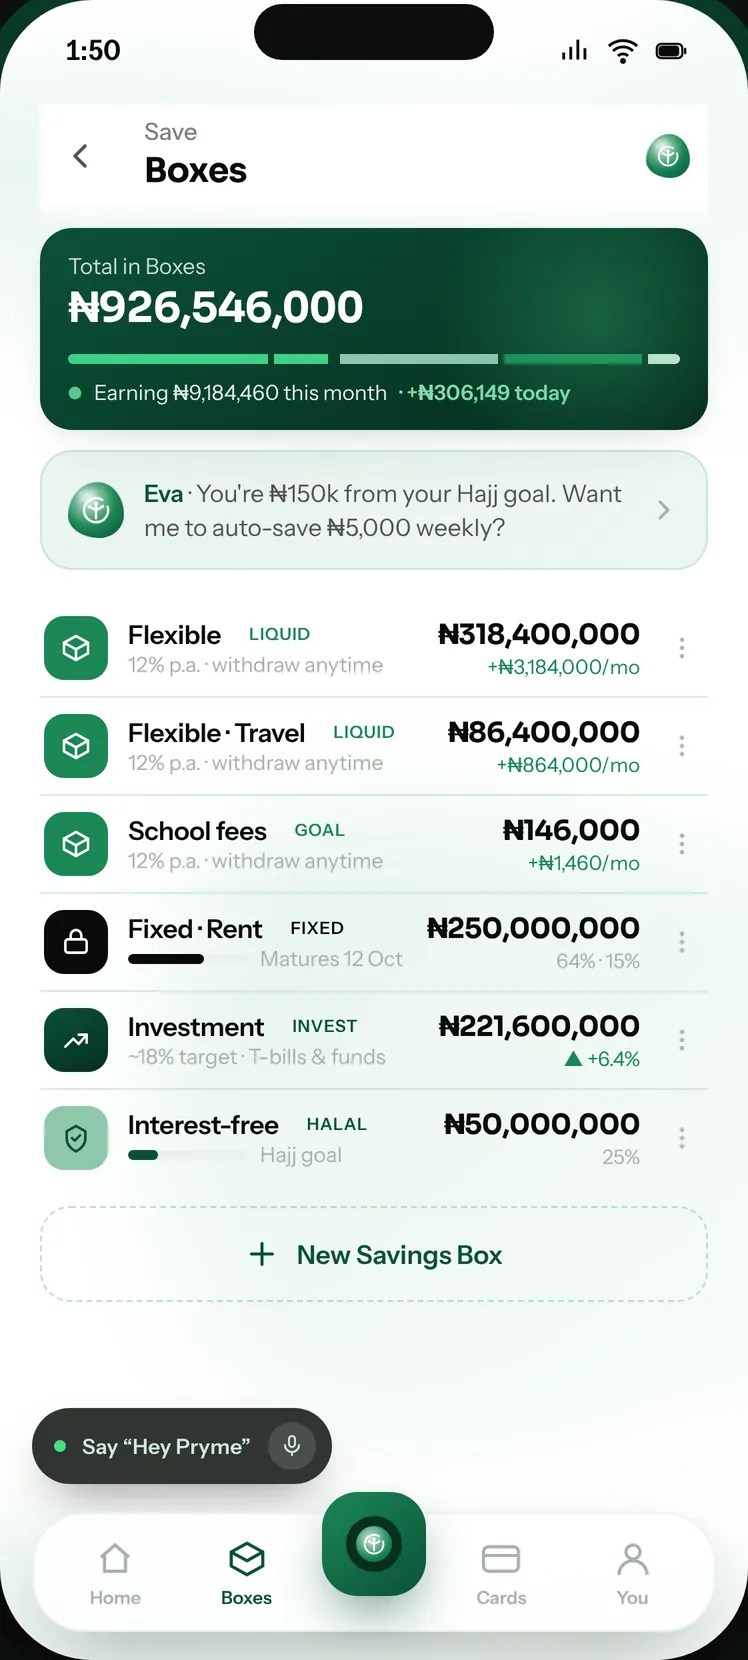
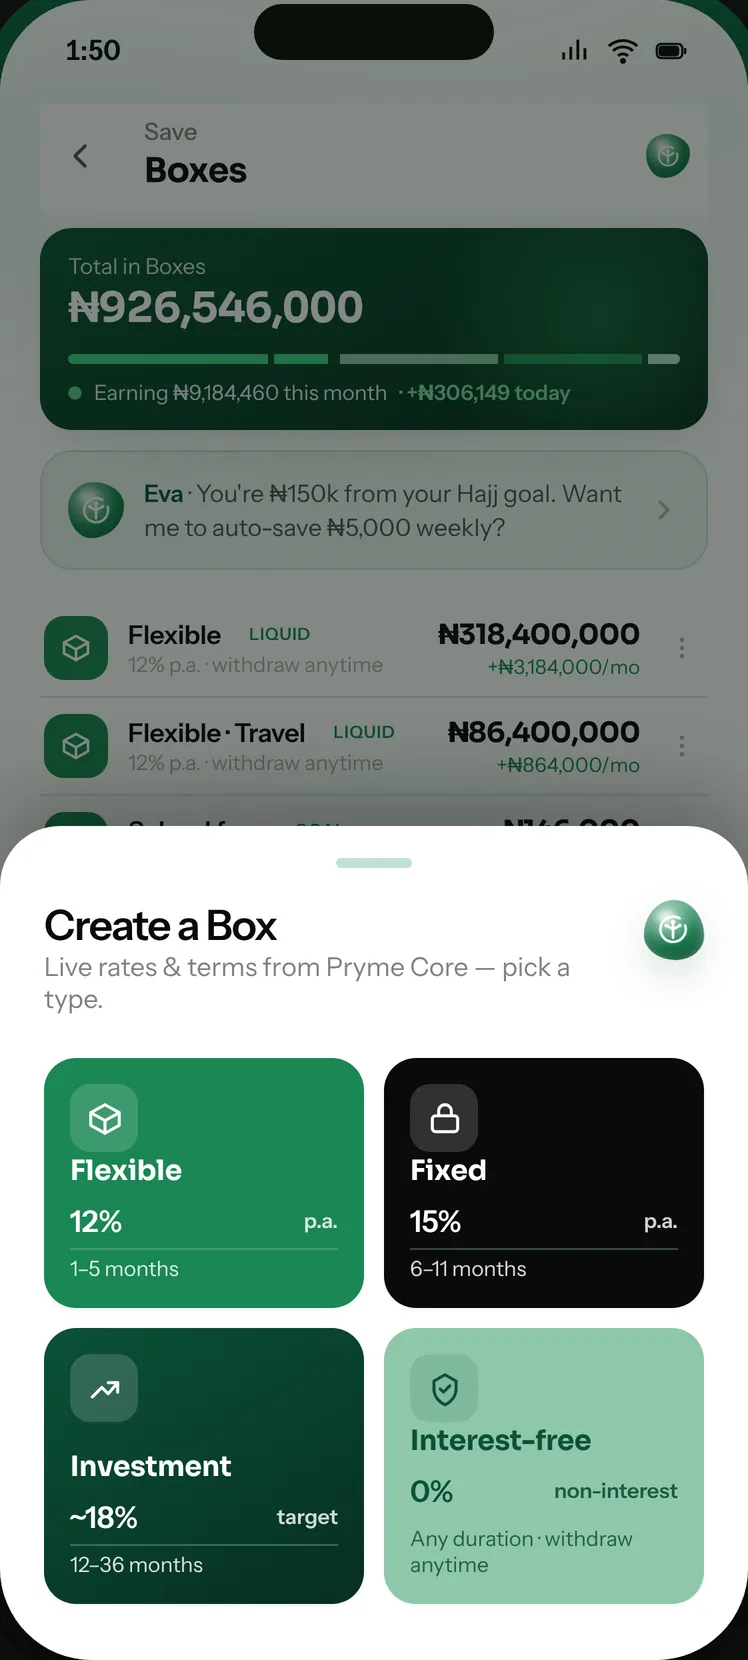
Savings Boxes are separate pots inside a Pryme account, held in Naira. Flexible Boxes can be withdrawn at any time, Fixed Boxes hold to a date, Investment Boxes hold for longer, and Interest-free Boxes earn nothing by design. A business can use them to ring-fence payroll and the tax it withholds, so that money cannot be spent by accident.
Pryme is a financial technology company, not a bank. Accounts and deposits are provided by Solid Allianze Microfinance Bank Limited, which is licensed by the Central Bank of Nigeria and is a member of the Nigeria Deposit Insurance Corporation.
Yes. Pryme Rails lets a platform issue a dedicated Naira account number to each of its own customers, collect into it and reconcile against it, over one API — the same rails the Pryme Business Account runs on.
Pryme is a financial technology company. It gives you one account that holds US dollars, pounds sterling and euros beside Naira, with an assistant that runs the account for you and asks before anything moves. Accounts are provided in Nigeria today, and further markets open as each licence lands.
Accounts are provided in Nigeria today, subject to verification and approval. Foreign-currency balances are held and converted inside that account, so you can hold, receive and swap dollars, pounds and euros wherever you are.
Naira, US dollars, pounds sterling and euros, side by side on one ledger. Each has its own details — a Nigerian account number, a US account number, a UK sort code and an IBAN for the euro area — and each has its own statement.
Swap at a rate you set rather than the rate of the day, then send to any Pryme username or to a Nigerian bank account. There is no fee to send to another Pryme account.
Eva is the assistant inside the Pryme app. She opens accounts, moves money, saves toward your goals, pays what is due and follows up what is owed to you — and asks you before anything moves.
Pryme Rails lets a platform issue a dedicated Naira account number to each of its own customers, collect into it and reconcile against it, over one API — the same rails the Pryme Business Account runs on.
Notes on money that does the work: what we are building, what the regulation actually says, and how we think about letting software act on money. Read the Ledger
What AI agents can do in bookkeeping, close, collections and compliance today, where a person must stay in charge, and how to judge a product.
How multi-currency business accounts work: local details vs SWIFT, payment rails, the real cost of FX, safeguarding vs deposit protection, and hedging.
How UK, US, Canadian and European firms pay Nigerian suppliers and get paid by Nigerian clients: FX, Form A and M, tax, compliance and payout routes.
What it really costs to send money to Nigeria from the UK, US, Canada and Europe: fees, exchange-rate margins, CBN naira rules, BVN, speed and scams.
What AI can and cannot do in day-to-day bookkeeping, how much time it saves on real numbers, and which jobs must stay with you or your accountant.
The signs of a Ponzi or fake investment scheme in Nigeria, lessons from CBEX, how to check SEC registration, and what to do if you have already paid in.
Part of the guideIs your money safe in a Nigerian fintech?
A Nigerian investment scheme is almost certainly a Ponzi if it promises high or guaranteed returns, pays you for recruiting others, is not registered with the SEC, and makes withdrawals harder over time. Before investing, check the platform on the SEC's register and confirm a named custodian holds your assets; under the Investments and Securities Act 2025, running a Ponzi scheme carries at least 10 years in prison.
A Ponzi scheme pays earlier investors with money from newer ones. It looks profitable until new money slows, then it collapses, and most people lose most of what they put in. Nigeria has seen this repeatedly, and the schemes keep changing their costume: crypto trading, forex, agriculture, "cooperative" savings. The pattern underneath stays the same. This article sits under our guide is your money safe in a Nigerian fintech?, which explains how deposits and investments are protected differently.
CBEX began operating in Nigeria in July 2024, promising returns of 100% within 30 days. Users reported withdrawal problems around 10 April 2025, and by 15 April withdrawals were suspended and many balances showed zero. On 14 April, the SEC's Director-General warned that "if a platform is not registered with the SEC, it is illegal". Estimates of total losses varied widely in early reporting, and some published figures were later corrected.
The lesson is in the numbers. Doubling money every month means a ₦100,000 deposit would need to become more than ₦400 million in a year. No legitimate business earns that. Every scheme that offers it is paying early users with later deposits.
Grace is offered 30% a month on ₦500,000, paid monthly, by a "crypto arbitrage" scheme.
| Month | What Grace is promised | What the scheme must find in new money to pay her |
|---|---|---|
| 1 | ₦150,000 | ₦150,000 |
| 3 | ₦450,000 cumulative | ₦450,000 |
| 6 | ₦900,000 cumulative | ₦900,000, plus her ₦500,000 if she withdraws |
| 12 | ₦1,800,000 cumulative | ₦1,800,000, plus her ₦500,000 |
Multiply that by thousands of investors and the scheme must recruit faster each month just to stand still. When recruitment slows, withdrawals are frozen. If Grace was paid ₦150,000 in month 1 and the scheme collapsed in month 2, she would lose ₦350,000 net. Many people re-invest their "profits" and lose everything.
Remember that investments are not deposits, so they are not covered by the NDIC even when they are legitimate. Our explainer on NDIC deposit insurance sets out what is covered.
Under ISA 2025, the SEC can now prosecute Ponzi promoters, seek prison terms of at least 10 years and fines reported at ₦20 million or more, and recover profits. That makes reporting worth doing. Our guide on how to complain about a bank or fintech covers the other escalation routes.
In Nigeria, Pryme's Savings Boxes (Nigeria-only) include Flexible, Fixed, Investment and Interest-free Boxes. Rates are shown in the app before you commit and can change. The Investment Savings Box is the one closest to an investment, so here is plainly how it works. The money in it funds Solid Allianze's lending, including Spaces credit, which is where its return comes from and why it is held to a fixed date. That means the return depends on how the lending book performs, and the money is not available before maturity. Check the terms in the app for how it is protected before you put money in. There is no promised or guaranteed return. Before you put money into any Box, or into any savings or investment product from any provider, read its terms, check whether it is a deposit or an investment, and run the checks above. A rate that can change is normal; a return described as guaranteed and far above Treasury bill yields is the warning sign this article describes.
Whatever you choose, apply the same checks to us as to anyone else. The full checklist is in our guide to whether your money is safe in a Nigerian fintech.
Look for high or guaranteed returns, rewards for recruiting, no SEC registration, payment into personal accounts and withdrawals that become harder over time. Two or more of these together are a strong warning.
Search the company's legal name on the SEC's register of capital market operators and its fintech portal, and confirm it names a registered custodian holding your assets.
Under the Investments and Securities Act 2025, operators and promoters face at least 10 years in prison, substantial fines and recovery of their gains. The SEC can now prosecute them directly.
Sometimes, partly, if regulators or law enforcement freeze and recover assets. Report to the SEC and EFCC with evidence, and never pay a fee to a 'recovery agent'.
Not necessarily. Licensed savings apps earn interest from bank deposits or Treasury bills and can explain where returns come from. Check the deposit holder's licence and any SEC registration and custodian for investment products.
This article is general information, not financial, legal or tax advice. Products described are provided under the terms on this site and are subject to regulation and eligibility.
How CBN licences, NDIC deposit insurance, BVN/NIN rules and data protection work in Nigeria, and how to check any fintech before you trust it.
What the Nigeria Data Protection Act 2023 lets you demand from banks and fintechs: access, correction, deletion, objection and NDPC complaints.
How much the NDIC insures per depositor at banks, microfinance banks, PSBs and MMOs, what counts as a deposit, and how payouts work in 2026.
You can add the other type later — many of our customers hold both.
The business first, then you. Nothing is submitted until you review it.
Ideal customer profiles
Generated from your website by VerifiedLead.ai
Pick the ones that look right. Your Sales agent works these first, and you can change them at any time after opening.
We ask this because you have not given us a website. It helps us set the right limits from day one.
Which of these represents you?
Officers listed against this company on the UK register.
We have sent a six-digit code to your email address. Enter it below to confirm the address is yours.
Wrong address? Go back and change it — nothing is created until this step passes. We never ask for a code by phone or email; anyone who does is not us.
Last step. Each time you sign in we email you a six-digit code — we never send codes by SMS.