AI agents for business finance: what they can and can't do
What AI agents can do in bookkeeping, close, collections and compliance today, where a person must stay in charge, and how to judge a product.
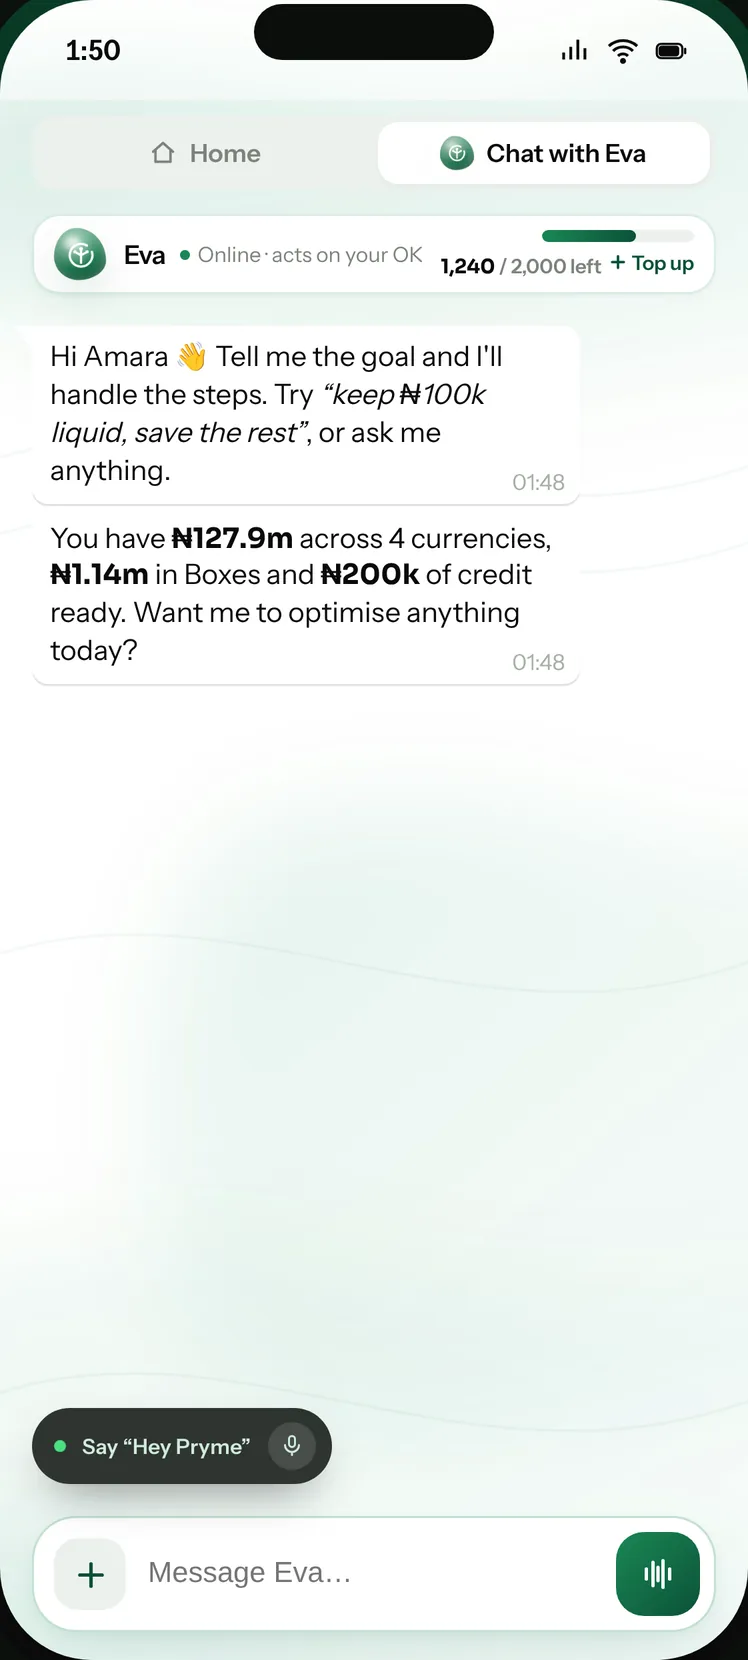
Meet Eva, the assistant inside the Pryme app. She opens accounts, moves money, saves toward your goals and follows up. Nothing leaves your account without your approval.
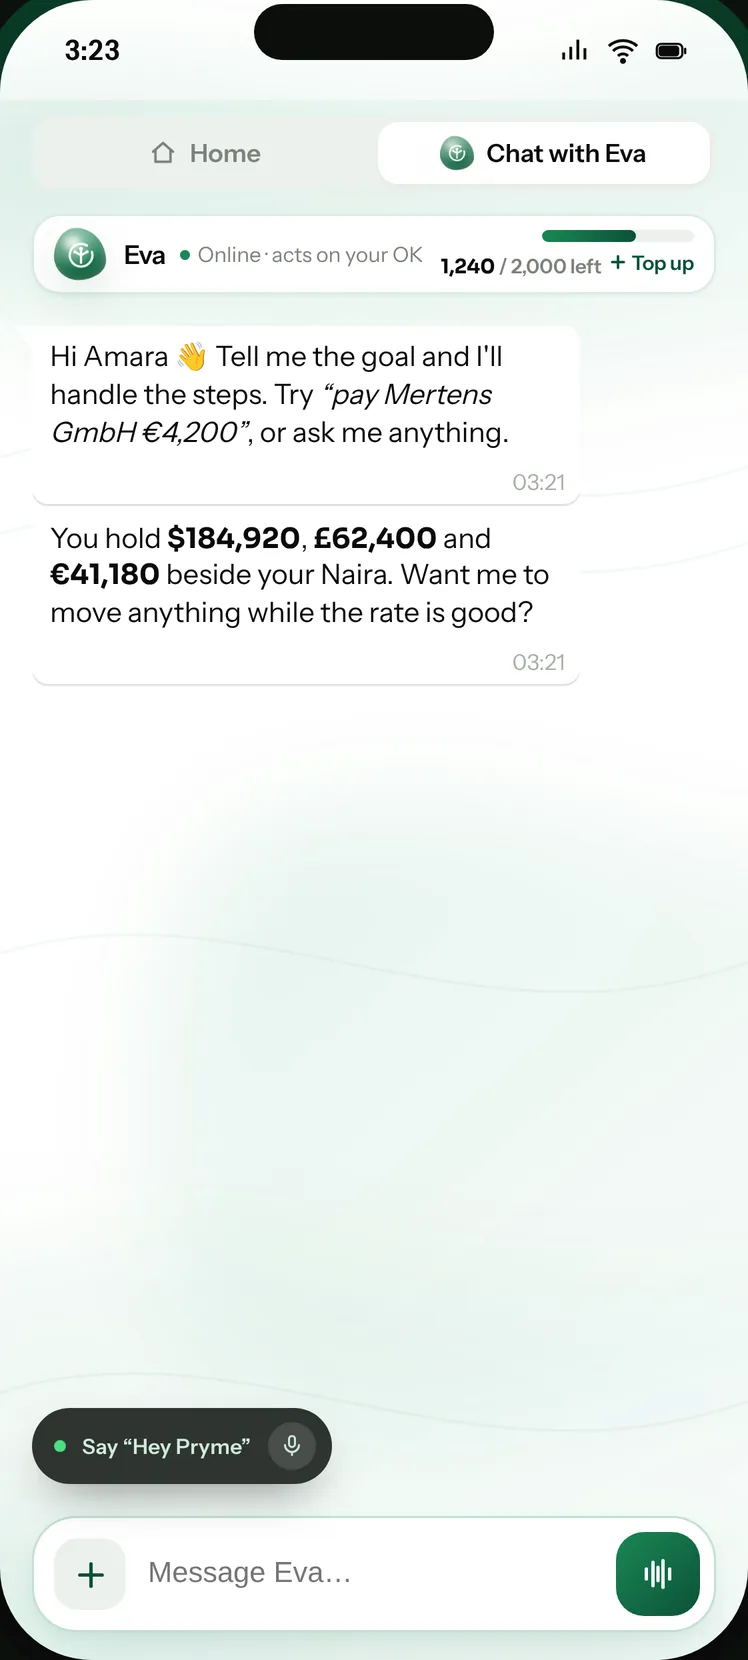
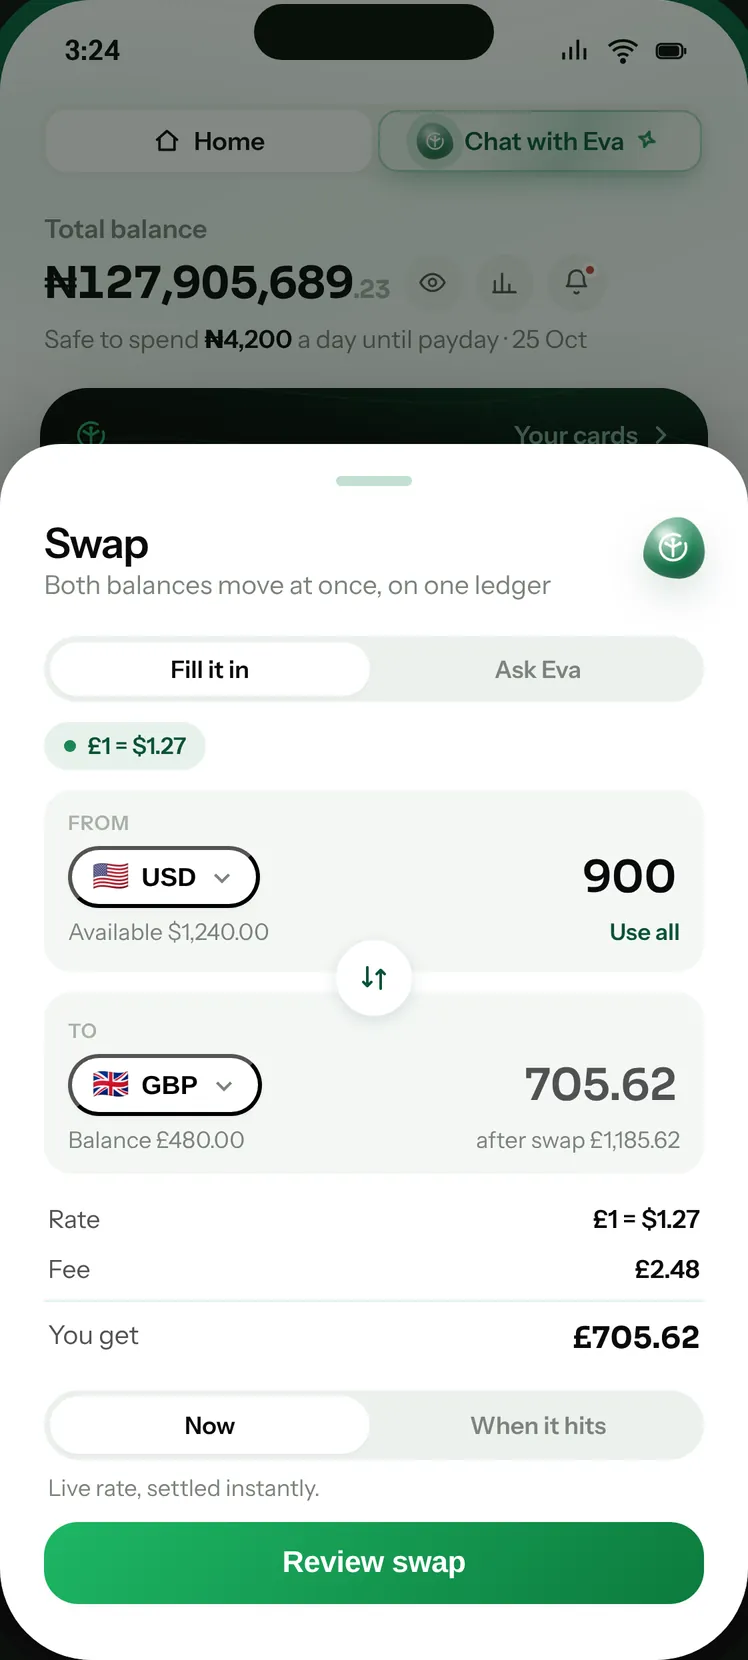
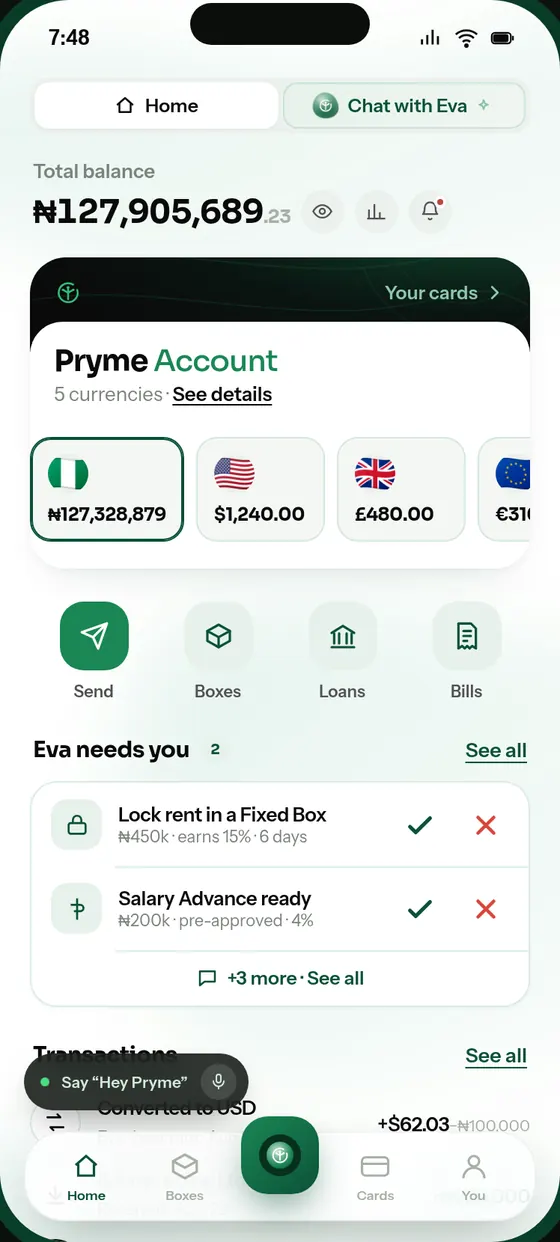
Meet Eva, the assistant inside the Pryme app. She holds dollars, pounds, euros and Naira side by side, swaps at a locked rate, pays bills in any of them and sends anywhere, asking before anything moves.
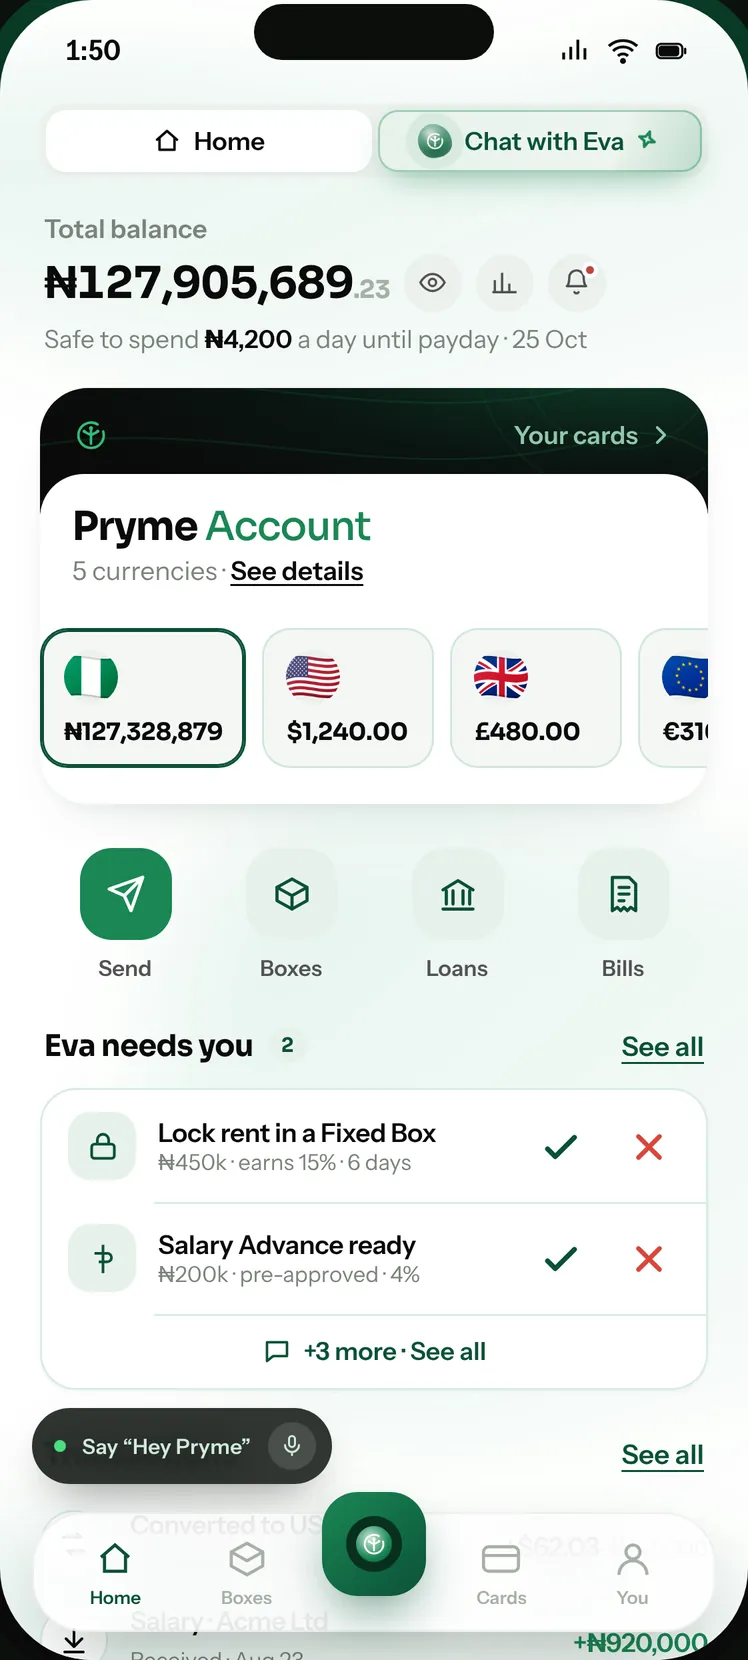
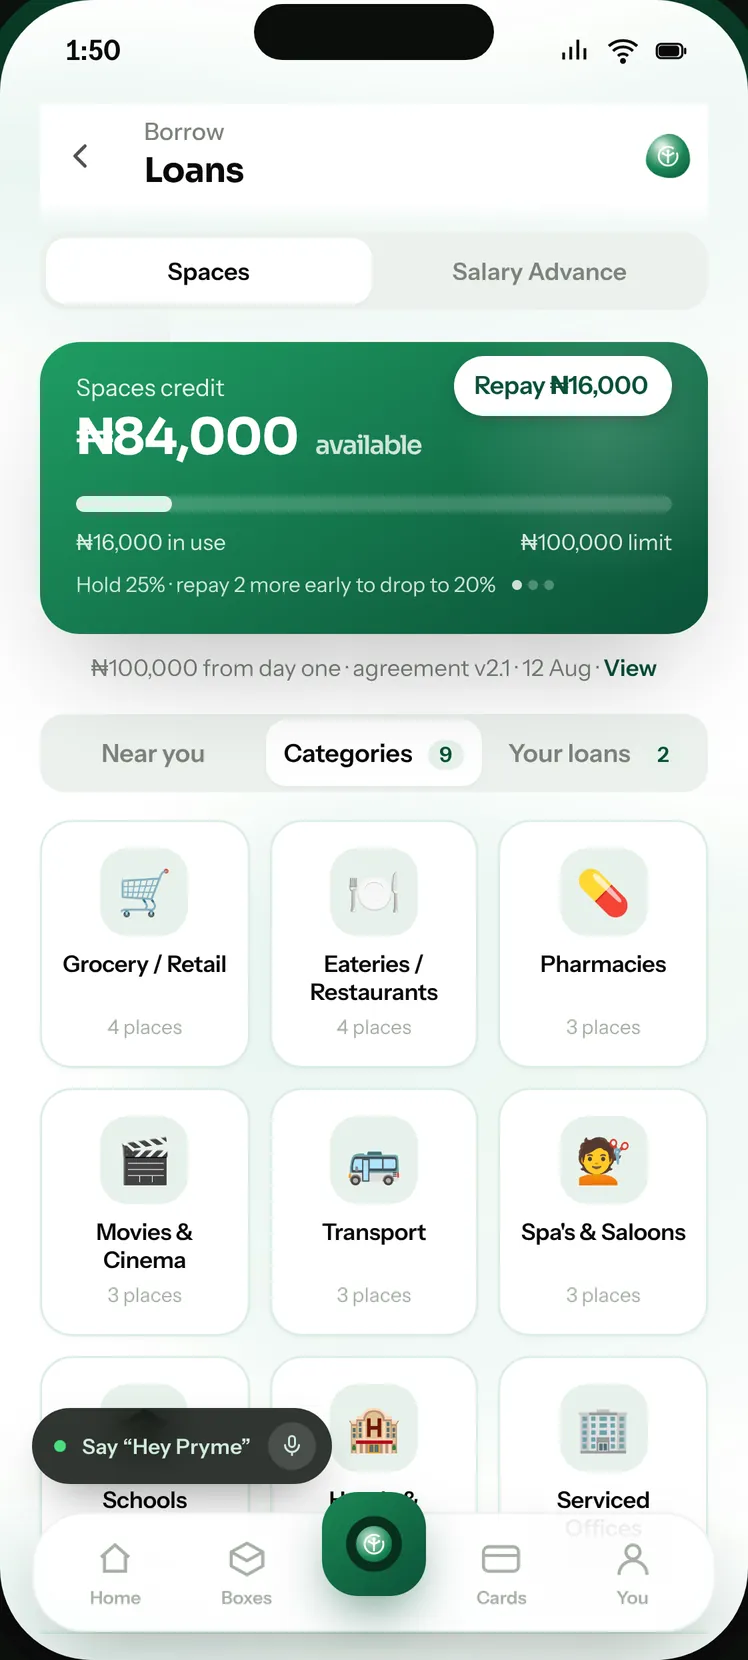
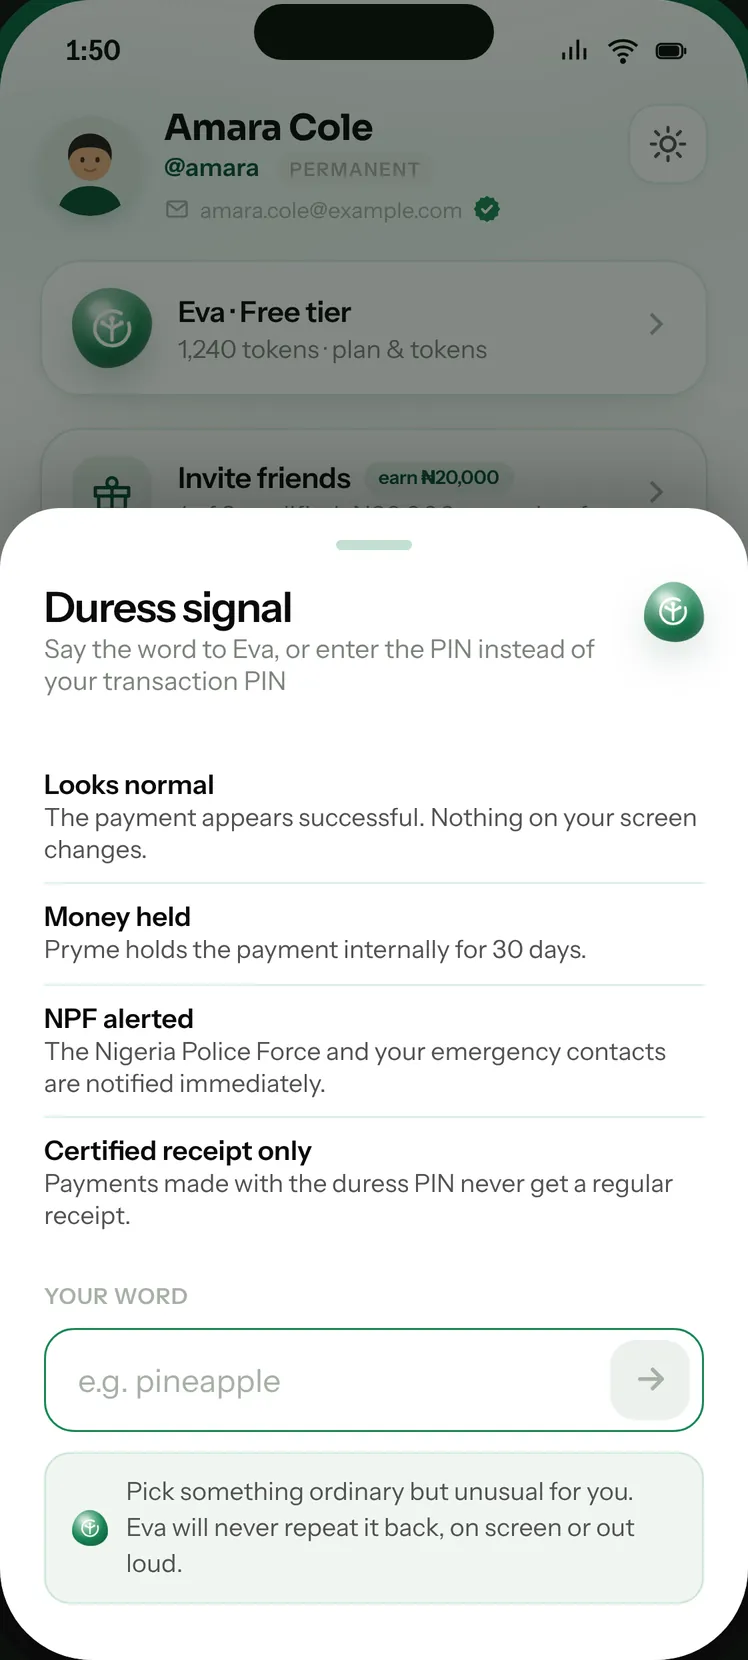
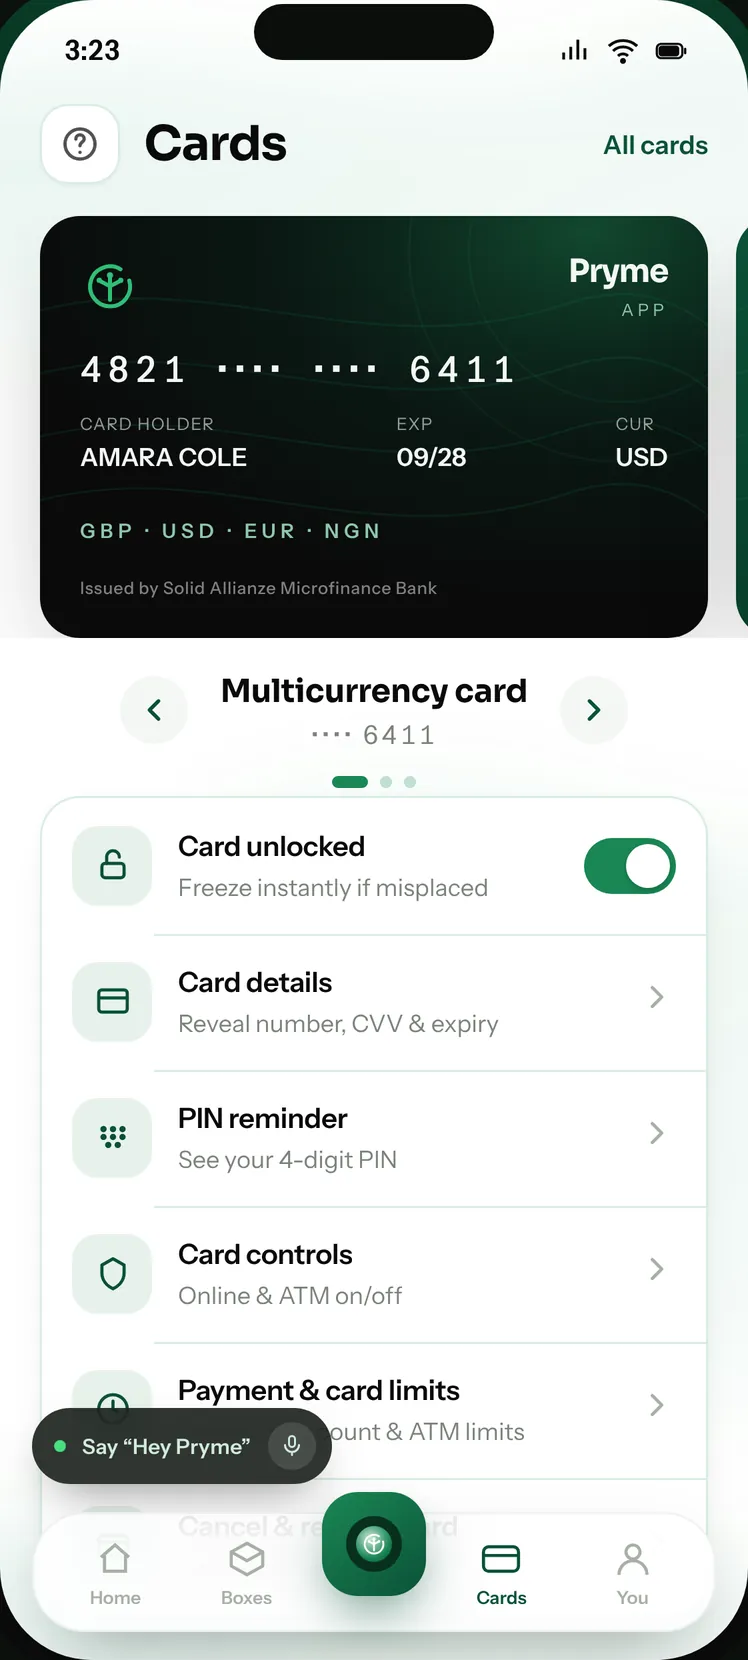
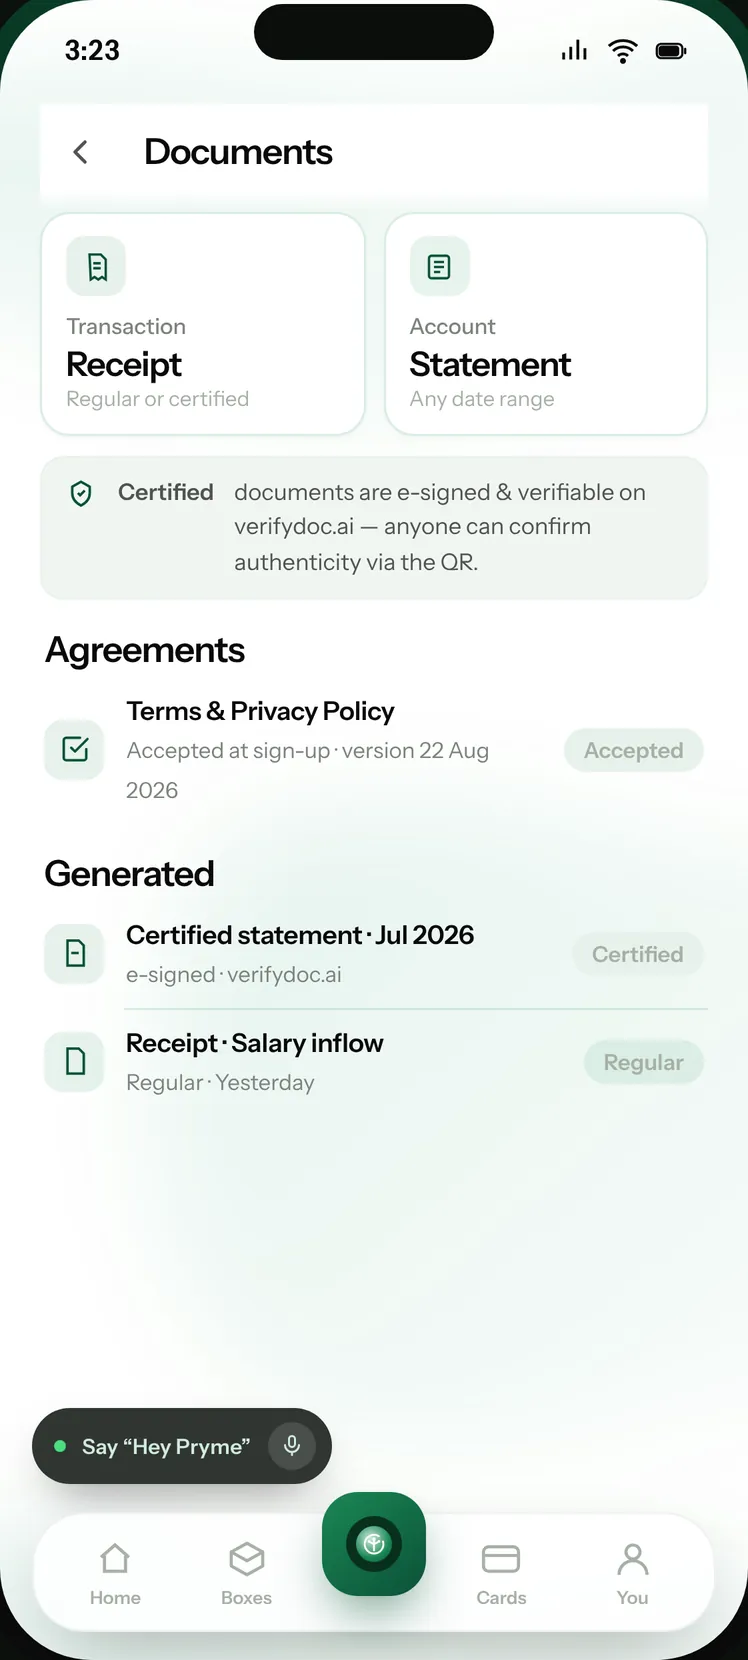
We give you a limit to spend at the shops and services you already use — and an account that works on your month while you get on with it. Dollars, pounds and euros sit beside your Naira, and an assistant handles the running of it, asking you first every single time.
One global account for your money and business. Move across currencies, automate everyday operations and put AI agents to work — with you in control of every important decision.
 Evayour assistant
 DanielChief of Staff
 BenFinance
 BruceCare
Your competitor down the road sells the same thing you sell. The difference is who walks in. We put money in people’s hands that can only be spent in businesses like yours — and then we point them at you.
You are not borrowing. You are selling to somebody who already has the money — and that money can only be spent with a business like yours.
₦100,000 from day one · agreement v2.1 · 12 Aug · View
Eva waits for your rate and asks before she moves anything.
No card, no OTP, nothing for the buyer to type in. They transfer from the bank app they already use, and the money lands in the same account your agents are running — already matched to the order, already in your books.
We give the buyer a one-time account number. They transfer to it from any bank app or by USSD — no card, no OTP, nothing to type in.
Get the account numberTo this account, from any bank app. We watch it, and the page updates itself.
₦26,767.50 from GTBank · John D., matched to order ORD‑1042.
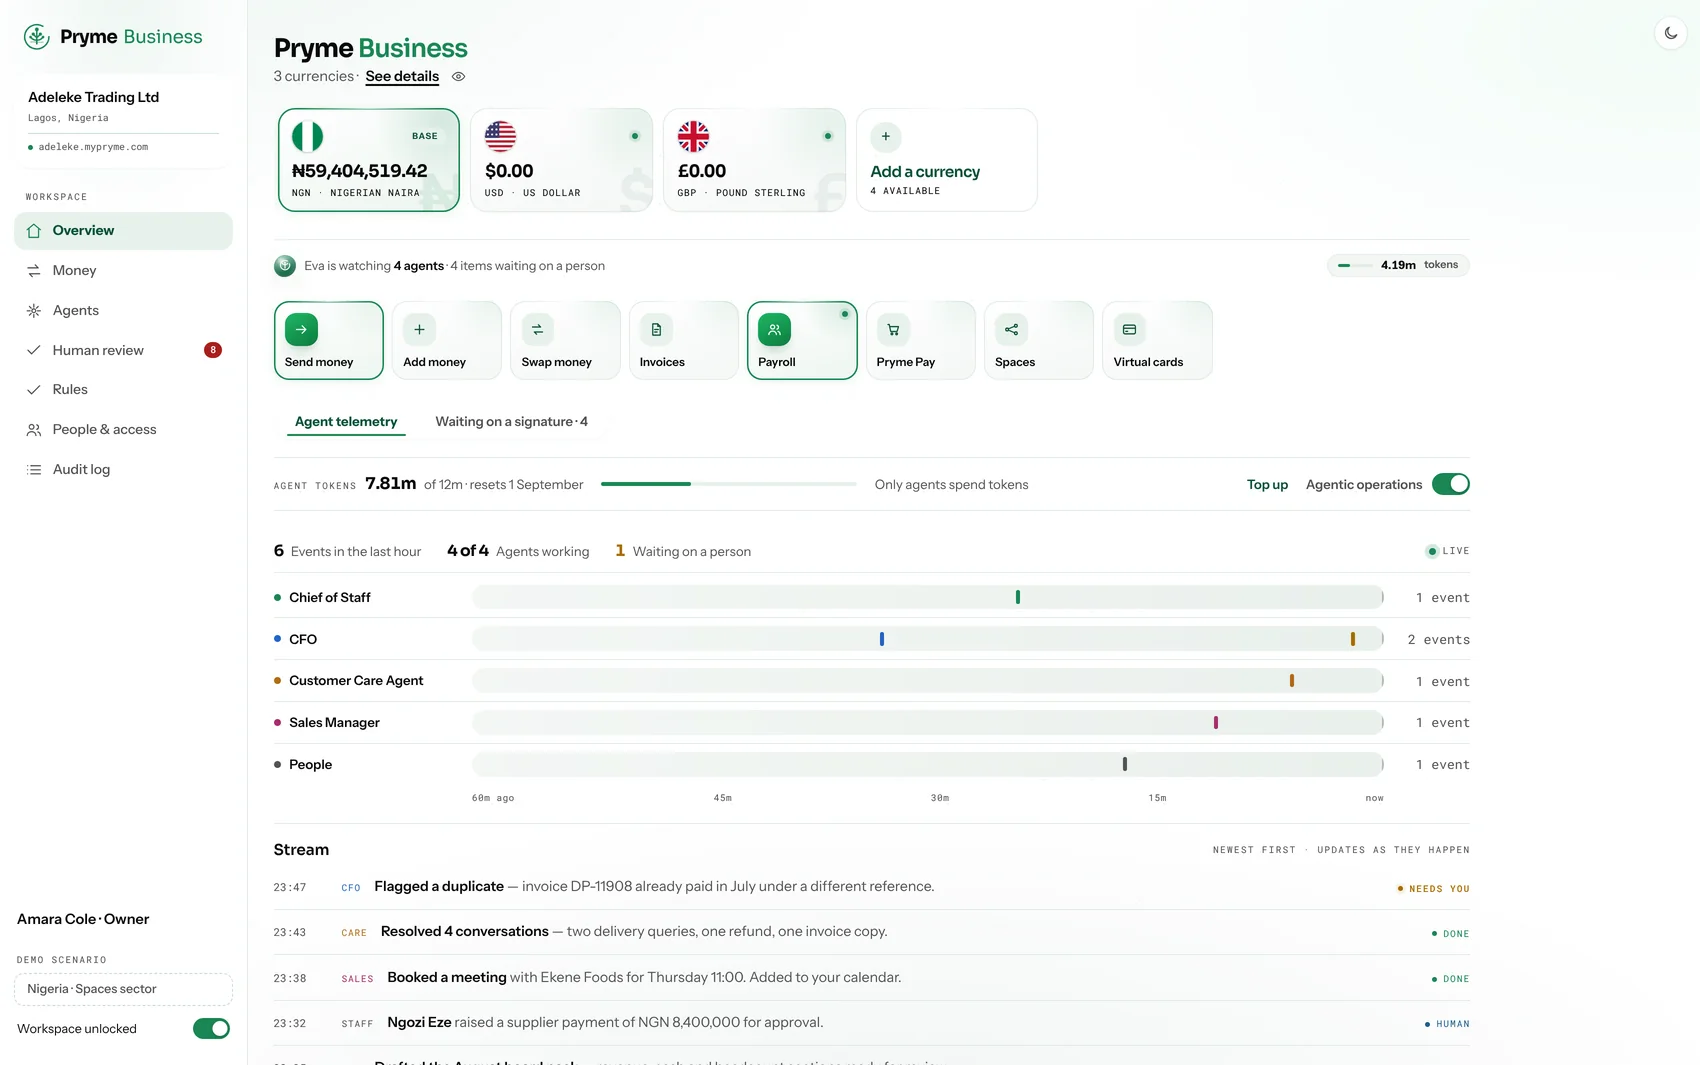
Five agents come with the account. Each one has a job description, a budget and a ceiling you set. They do the work and bring it to you — nothing leaves the account without your signature.
Knows what is stuck, who is waiting and what you promised — and keeps all three moving.
Booked a meeting with John Doe Foods for Thursday 11:00.Keeps the books as you trade and tells you the moment something does not add up.
Flagged a duplicate — invoice DP‑11908 was already paid in July.Holds every filing to its own clock and screens names and payments against your policy — and logs what it refuses.
Screened 412 payments overnight and refused two of them.Goes back to the buyers who went quiet, with the receipt already attached.
Recovered ₦410,000 across three overdue invoices.Replies, follows up on what they asked for and hands you only the ones that need you.
Resolved 4 conversations — two deliveries, one refund.Issue a dedicated Naira account number to each of your own customers, collect into it and reconcile against it. The same rails the Business Account runs on, with the licence behind them.
Dollars, pounds and euros beside a Naira account, on one ledger and one set of books. Five agents come with it and run the account — nothing leaves without your signature.
Five agents come with the account. Each has a job description, a budget and a ceiling you set. They do the work and bring it to you — they propose, you approve.
Knows what is stuck, who is waiting and what you promised, and keeps all three moving.
Booked the quarterly review with your auditor for Thursday.Keeps the books in every currency you hold and flags the moment something does not add up.
Flagged a duplicate — invoice DP‑11908 was already paid in July.Holds every filing to its own clock and screens names and payments against your policy — and logs what it refuses.
Screened 412 payments overnight and refused two of them.Goes back to the buyers who went quiet, with the invoice and the receipt already attached.
Recovered $12,400 across three overdue invoices.Replies, follows up on what they asked for and hands you only the ones that need you.
Resolved 4 conversations — two deliveries, one refund.The business has changed shape four times and never changed what it was rooted in. Each version was built out of what the last one could not do.
An online grocery store, built out of a faulty tab. Selling the food was the easy part — taking the money for it, and moving it, turned out to be the business.
A prepaid card. The first time the company issued rather than resold, and the first time it carried the obligations that come with holding somebody else’s money.
Solid Allianze acquired — an existing bank with an existing licence. The perimeter stopped being someone else’s to draw.
More than one currency on one balance, and the rebrand to Pryme. A Nigerian business could hold dollars without holding a second institution.
Accounts that do the work rather than only hold value. Five agents on the account, inside a policy you write — which is where the new mark starts.
Pryme is a financial technology company. It gives people and businesses in Nigeria one account that holds Naira alongside dollars, pounds and euros, and a set of agents that do the running of it — keeping the books, chasing what is owed, answering customers and paying bills. Nothing leaves an account without the owner’s approval.
Yes. A Pryme account holds Naira, US dollars, pounds sterling and euros side by side on one ledger, each with its own account details — a Nigerian account number, a US account number, a UK sort code and an IBAN for the euro area. You can swap between them at a rate you set, and every currency has its own statement.
Spaces is available in Nigeria. It gives a shopper money to spend that can only be spent with a participating business. The business is paid into its Naira account whether or not the shopper repays, because Pryme carries the credit. For the business it is free to join, there is nothing monthly, and the customer’s identity is never shown — only a reference and what it is worth.
Five agents come with the account. The Chief of Staff runs the week and keeps what is stuck moving. Finance watches the money and keeps the books as you trade. Compliance keeps the filings on time and screens what moves. Sales chases what you are owed. Customer Support answers your customers and follows up. Each has a job description, a budget and a ceiling you set, and each one proposes rather than acts — nothing leaves the account without your signature.
Pryme Pay takes payments on your own site or on a checkout page you control. The buyer is given a one-time account number and transfers to it from any bank app or by USSD — no card, no OTP, nothing to type in. The money lands in the same account your agents are running, already matched to the order and already in your books.
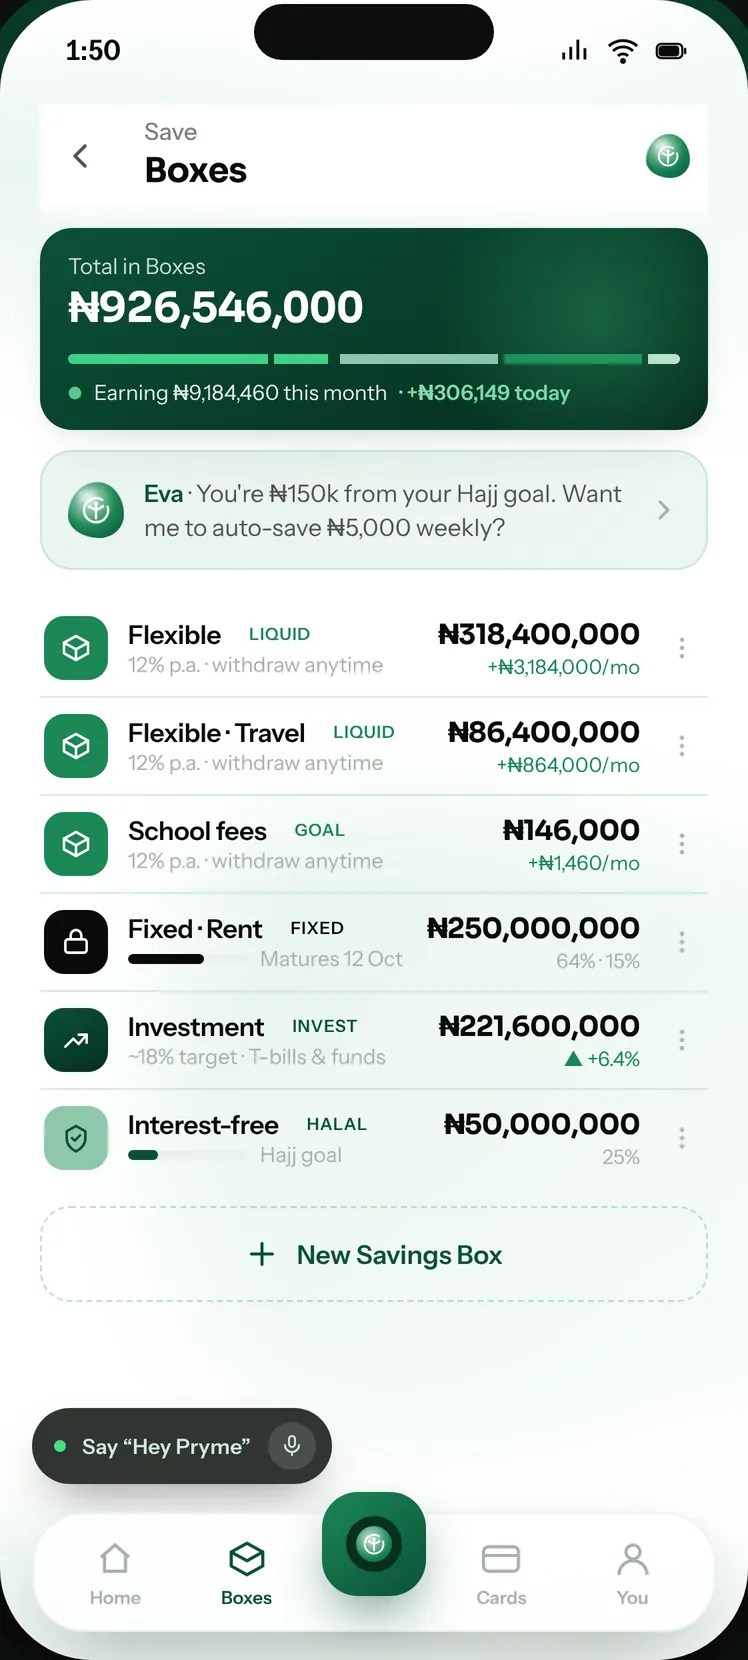
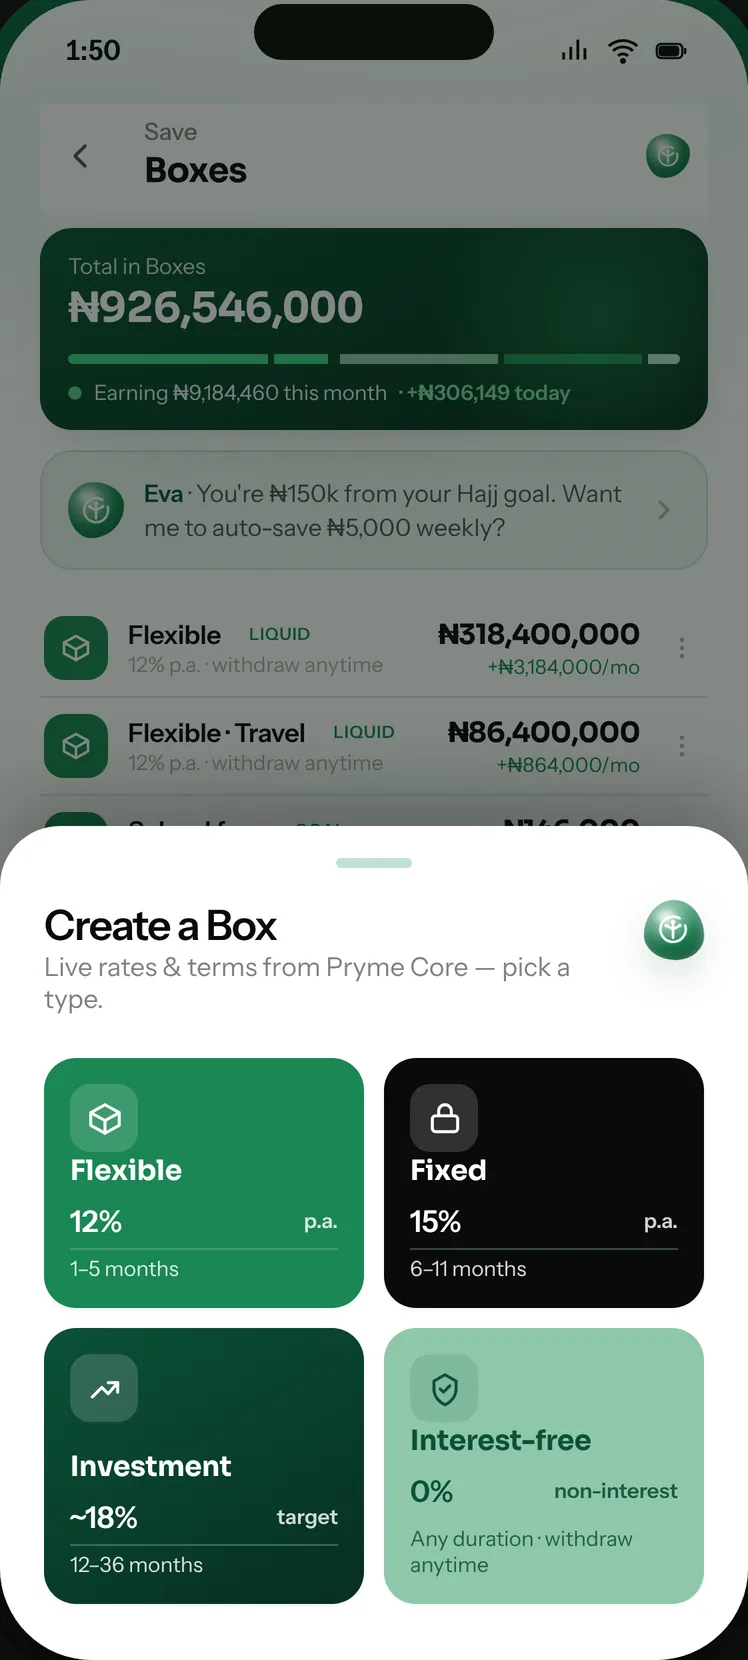
Savings Boxes are separate pots inside a Pryme account, held in Naira. Flexible Boxes can be withdrawn at any time, Fixed Boxes hold to a date, Investment Boxes hold for longer, and Interest-free Boxes earn nothing by design. A business can use them to ring-fence payroll and the tax it withholds, so that money cannot be spent by accident.
Pryme is a financial technology company, not a bank. Accounts and deposits are provided by Solid Allianze Microfinance Bank Limited, which is licensed by the Central Bank of Nigeria and is a member of the Nigeria Deposit Insurance Corporation.
Yes. Pryme Rails lets a platform issue a dedicated Naira account number to each of its own customers, collect into it and reconcile against it, over one API — the same rails the Pryme Business Account runs on.
Pryme is a financial technology company. It gives you one account that holds US dollars, pounds sterling and euros beside Naira, with an assistant that runs the account for you and asks before anything moves. Accounts are provided in Nigeria today, and further markets open as each licence lands.
Accounts are provided in Nigeria today, subject to verification and approval. Foreign-currency balances are held and converted inside that account, so you can hold, receive and swap dollars, pounds and euros wherever you are.
Naira, US dollars, pounds sterling and euros, side by side on one ledger. Each has its own details — a Nigerian account number, a US account number, a UK sort code and an IBAN for the euro area — and each has its own statement.
Swap at a rate you set rather than the rate of the day, then send to any Pryme username or to a Nigerian bank account. There is no fee to send to another Pryme account.
Eva is the assistant inside the Pryme app. She opens accounts, moves money, saves toward your goals, pays what is due and follows up what is owed to you — and asks you before anything moves.
Pryme Rails lets a platform issue a dedicated Naira account number to each of its own customers, collect into it and reconcile against it, over one API — the same rails the Pryme Business Account runs on.
Notes on money that does the work: what we are building, what the regulation actually says, and how we think about letting software act on money. Read the Ledger
What AI agents can do in bookkeeping, close, collections and compliance today, where a person must stay in charge, and how to judge a product.
How multi-currency business accounts work: local details vs SWIFT, payment rails, the real cost of FX, safeguarding vs deposit protection, and hedging.
How UK, US, Canadian and European firms pay Nigerian suppliers and get paid by Nigerian clients: FX, Form A and M, tax, compliance and payout routes.
What it really costs to send money to Nigeria from the UK, US, Canada and Europe: fees, exchange-rate margins, CBN naira rules, BVN, speed and scams.
What AI can and cannot do in day-to-day bookkeeping, how much time it saves on real numbers, and which jobs must stay with you or your accountant.
How Ghana's NHIS is funded through payroll, what we could and could not confirm about cover, and when private insurance makes sense for Nigerians.
Many Nigerians in Ghana keep private cover alongside the National Health Insurance Scheme, because NHIS is a basic public scheme and employers, schools and permit applications can set their own requirements. If you are formally employed, 2.5 percentage points of the 13.5% your employer remits to SSNIT go to the National Health Insurance Authority, but that payment is not the same as an active NHIS membership card, and it does not tell you what is covered.
Health cover is one of those questions that only becomes urgent at the worst moment. For a Nigerian living in Ghana the choice is usually between relying on Ghana's National Health Insurance Scheme, buying private health insurance, or holding both. This article sets out what we could confirm from official and professional sources, what we could not, and how to make the decision without guessing.
If you work for an employer in Ghana, part of your pension deduction funds the health scheme. SSNIT's own FAQ says the worker contributes 5.5% of basic salary and the employer 13%, a total of 18.5%. Of the 13.5% the employer remits to SSNIT, the FAQ says 2.5% goes to the National Health Insurance Authority, and the remaining 5% goes to the mandatory second-tier occupational scheme. PwC's Ghana summary, reviewed in March 2026, gives the same 5.5% and 13% rates.
There is also a 2.5% National Health Insurance Levy (NHIL) on taxable supplies, listed by PwC alongside VAT. You pay that every time you buy standard-rated goods or services from a VAT-registered business, whether or not you are covered.
We set out to source three points and could not do so from pages we opened for this article. Rather than fill the gap from memory, here is what to ask:
Without assuming anything about NHIS benefits, the situations where private health insurance usually earns its cost are predictable:
Private plans in Ghana are sold by insurers and health maintenance-style providers, and they differ in ways that matter more than the headline premium. Ask each provider the same questions and get the answers in writing:
| Question | Why it matters |
|---|---|
| Which hospitals are in network in your city? | A cheap plan is useless if your nearest good hospital is outside it. |
| What is excluded, and what are the waiting periods? | Pre-existing conditions and maternity often have waiting periods. |
| Is there an annual limit per person? | A low cap can run out after one admission. |
| Does it cover treatment or evacuation to Nigeria? | Matters if you would want treatment at home. |
| How are claims paid: direct to hospital or reimbursed? | Reimbursement means you pay first and wait. |
| What happens to cover if you change job or leave Ghana? | Group plans usually end with employment. |
Example only, with made-up numbers: Tolu earns a basic salary of GH¢8,000 a month in Accra. Using SSNIT's stated rates, her employer pays 13% (GH¢1,040) and she pays 5.5% (GH¢440), so GH¢1,480 goes towards social security. Of the employer's remittance to SSNIT, 2.5% of her basic salary (GH¢200) goes to the NHIA. Her employer also offers a private group plan for which she would pay part of the premium. Whether that is worth it depends on the network list and exclusions, not on the NHIA payment, which happens either way.
If you are also paying for parents' care in Nigeria, that is a separate decision under Nigeria's own health insurance system. See health insurance for parents in Nigeria from Ghana and paying a hospital bill in Nigeria from Ghana.
If you pay a premium or a hospital bill in naira for family at home, a Pryme account holds naira alongside dollars, pounds and euros, and Send shows the fee before you approve. A verifiable receipt gives the hospital or insurer proof that the payment is genuine.
SSNIT's FAQ says 2.5% of the employer's 13.5% remittance goes to the National Health Insurance Authority. Your membership and card status are confirmed by the NHIA, not by your payslip.
We could not confirm a general rule. Check your Ghana Immigration Service permit checklist and your employment contract, which can set their own requirements.
The hospital network, exclusions and waiting periods, the annual limit, how claims are paid and whether cover extends to Nigeria.
Many people hold both. Ask your private insurer how it treats care that NHIS also covers.
This article is general information, not financial, legal or tax advice. Products described are provided under the terms on this site and are subject to regulation and eligibility.
What we could confirm about NHIS for non-citizens in Ghana, what an employee already pays towards it, and what to ask an NHIA office before relying on it.
What we could and could not confirm about using a Nigerian licence in Ghana, how DVLA conversion works in outline, and keeping the FRSC licence valid.
Banks in Ghana rely on the Ghana Card, so a Nigerian student usually needs a student permit and non-citizen card first. Documents, steps and costs.
You can add the other type later — many of our customers hold both.
The business first, then you. Nothing is submitted until you review it.
Ideal customer profiles
Generated from your website by VerifiedLead.ai
Pick the ones that look right. Your Sales agent works these first, and you can change them at any time after opening.
We ask this because you have not given us a website. It helps us set the right limits from day one.
Which of these represents you?
Officers listed against this company on the UK register.
We have sent a six-digit code to your email address. Enter it below to confirm the address is yours.
Wrong address? Go back and change it — nothing is created until this step passes. We never ask for a code by phone or email; anyone who does is not us.
Last step. Each time you sign in we email you a six-digit code — we never send codes by SMS.