AI agents for business finance: what they can and can't do
What AI agents can do in bookkeeping, close, collections and compliance today, where a person must stay in charge, and how to judge a product.
Meet Eva, the assistant inside the Pryme app. She opens accounts, moves money, saves toward your goals and follows up. Nothing leaves your account without your approval.
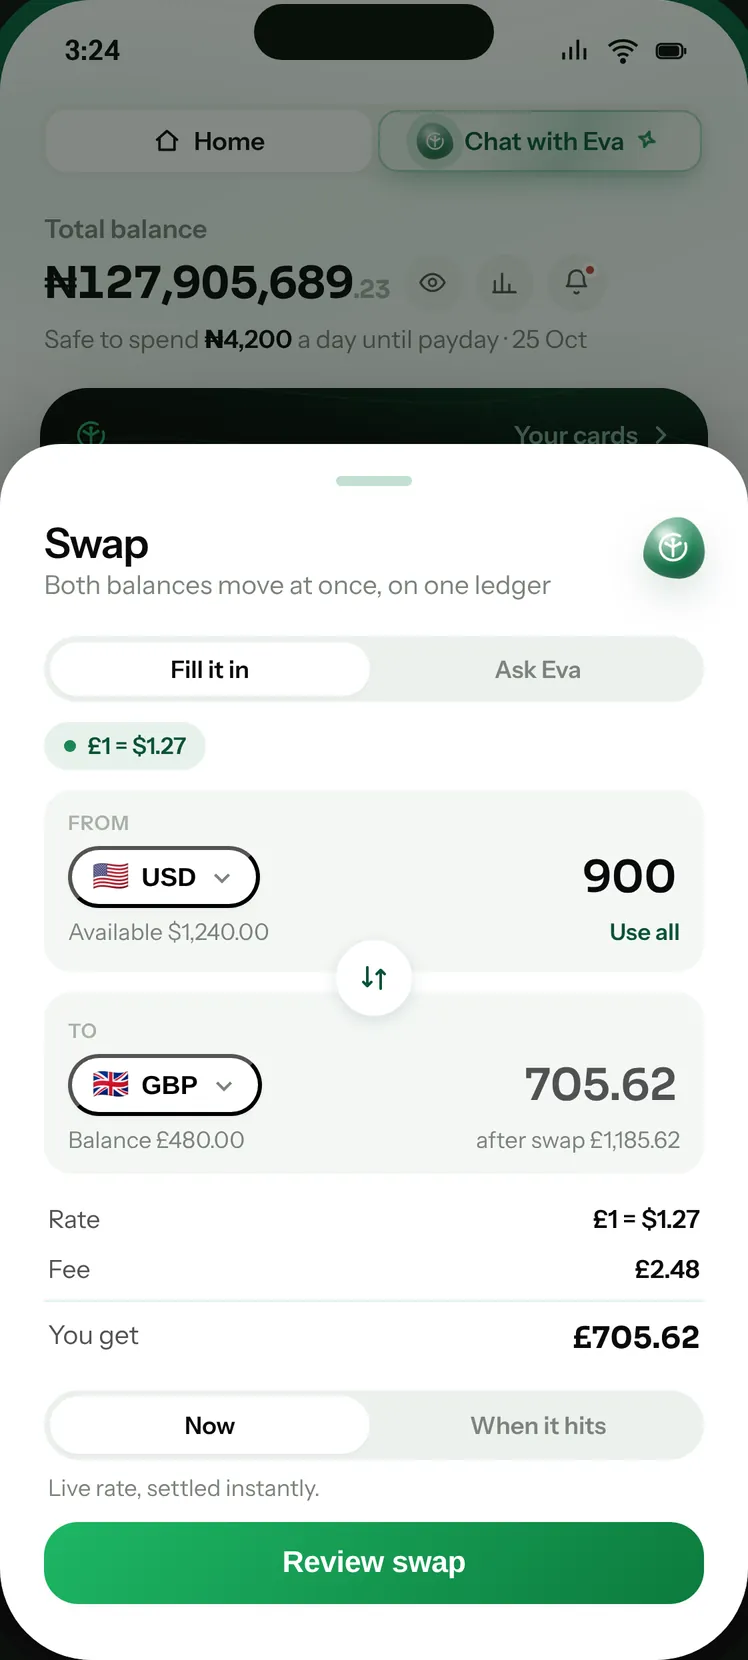
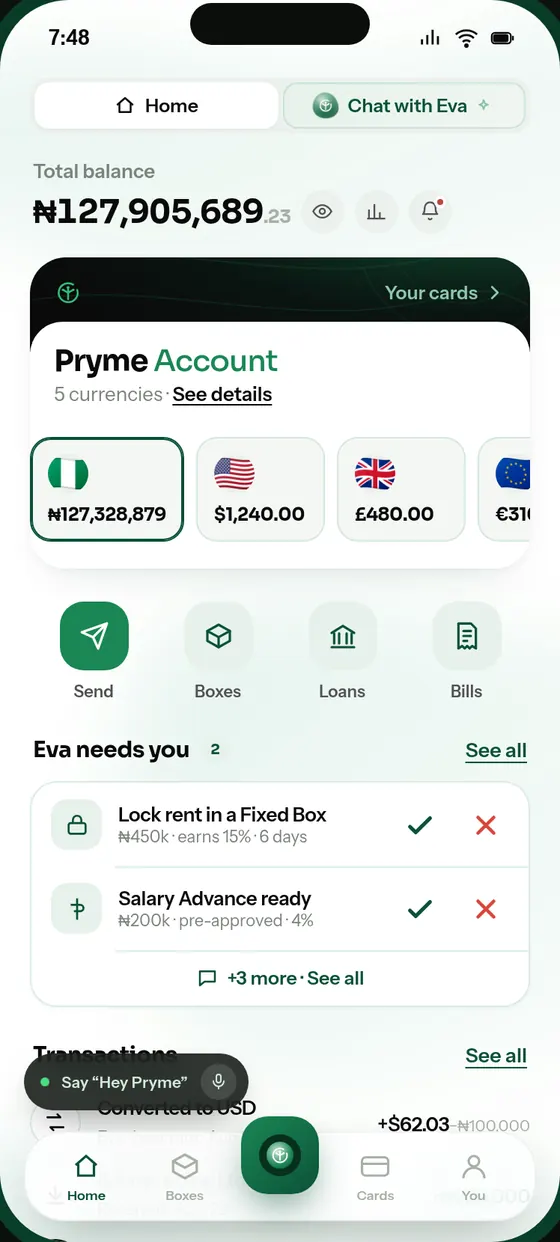
Meet Eva, the assistant inside the Pryme app. She holds dollars, pounds, euros and Naira side by side, swaps at a locked rate, pays bills in any of them and sends anywhere, asking before anything moves.
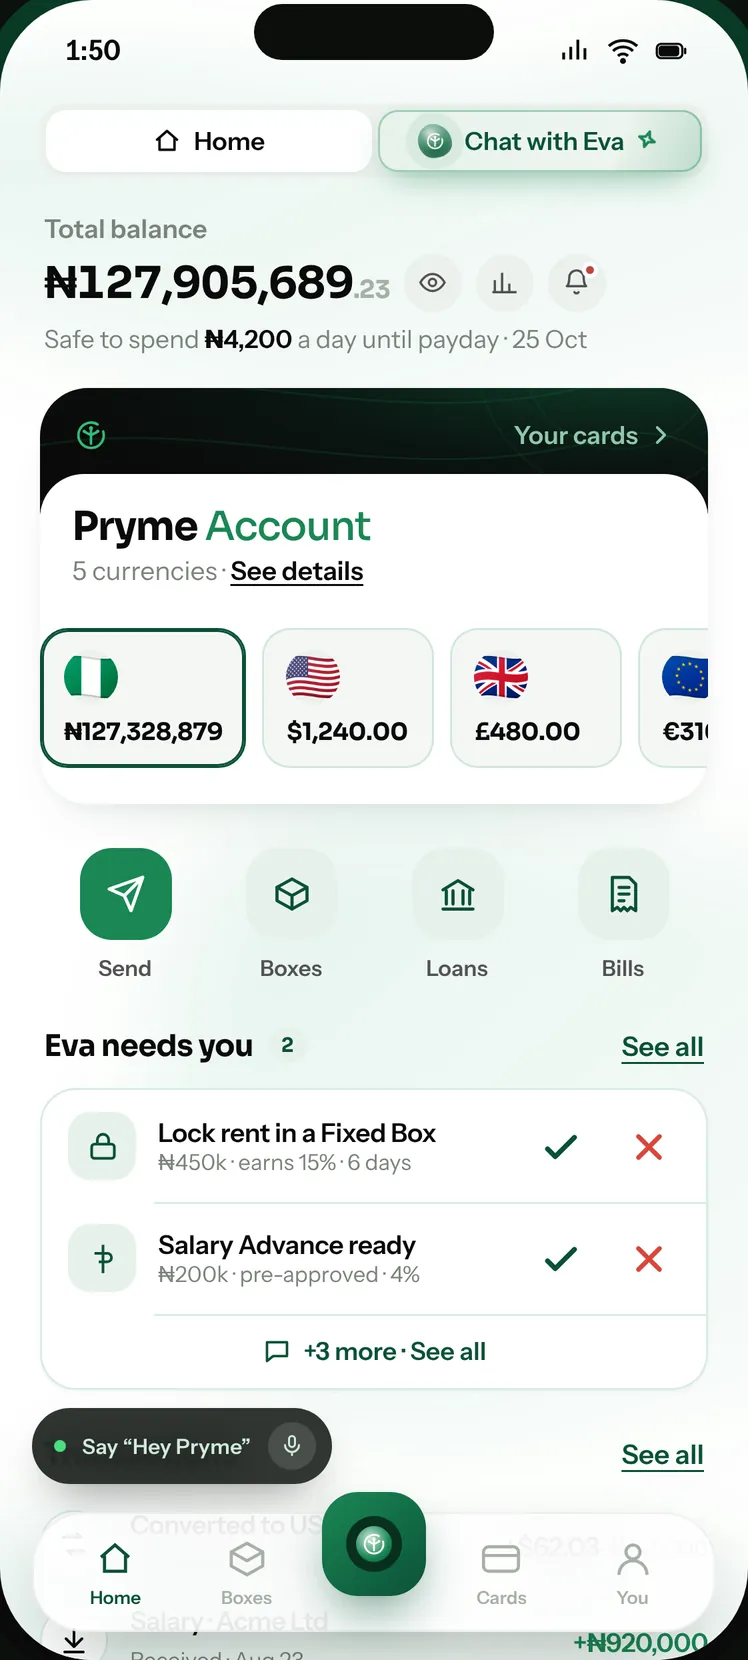
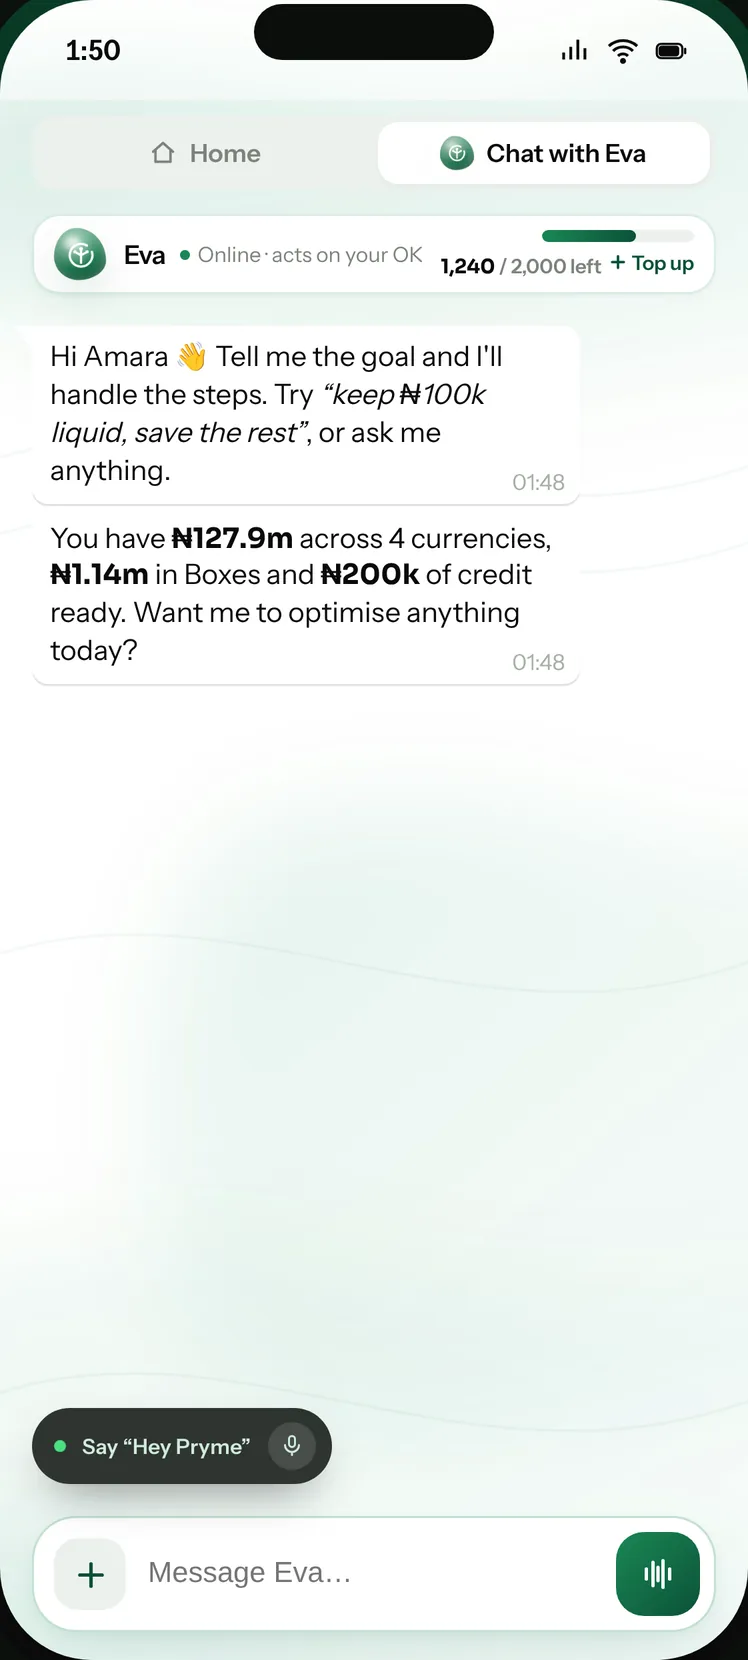
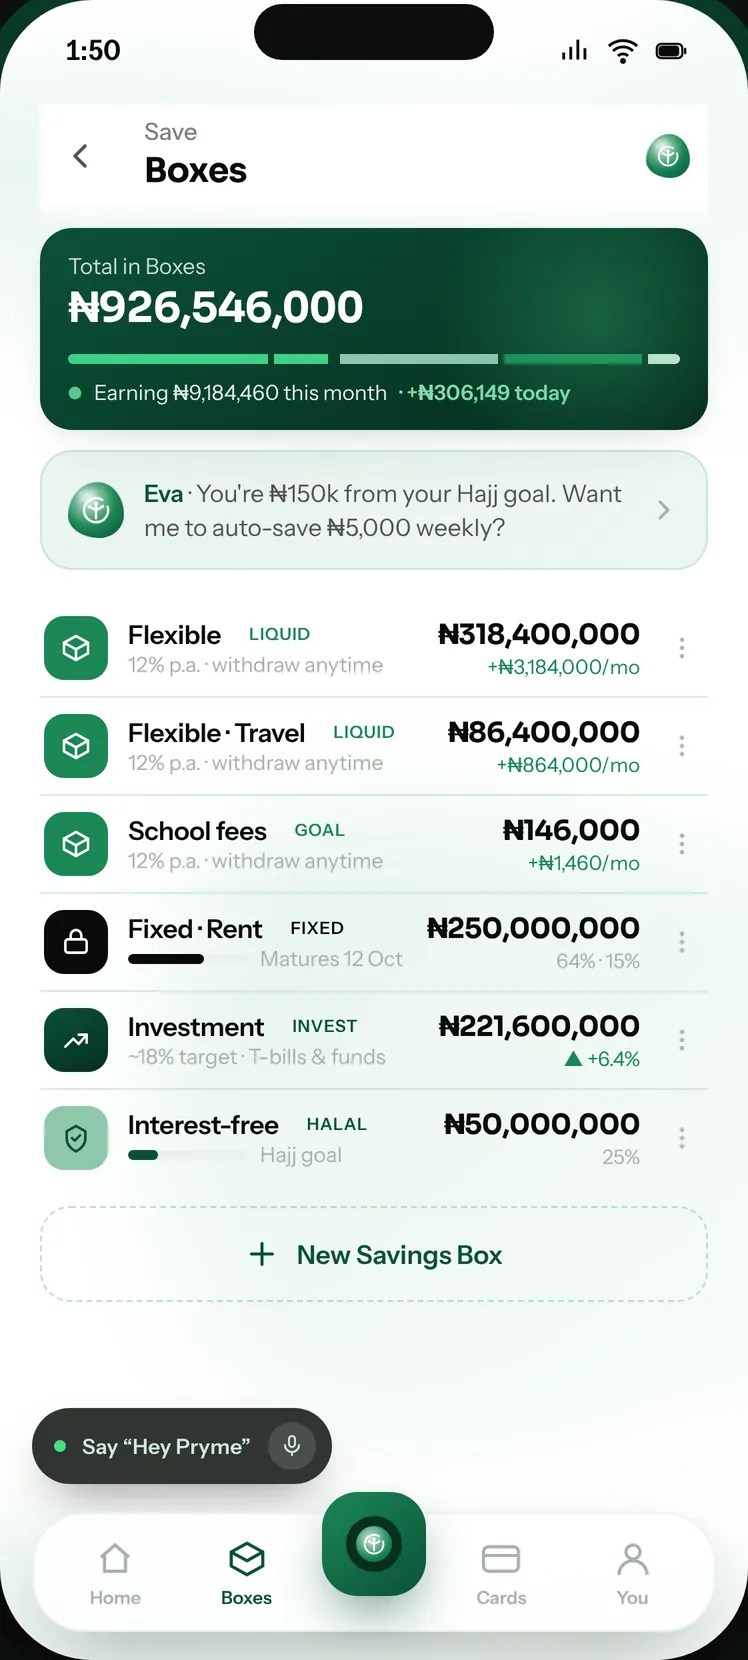
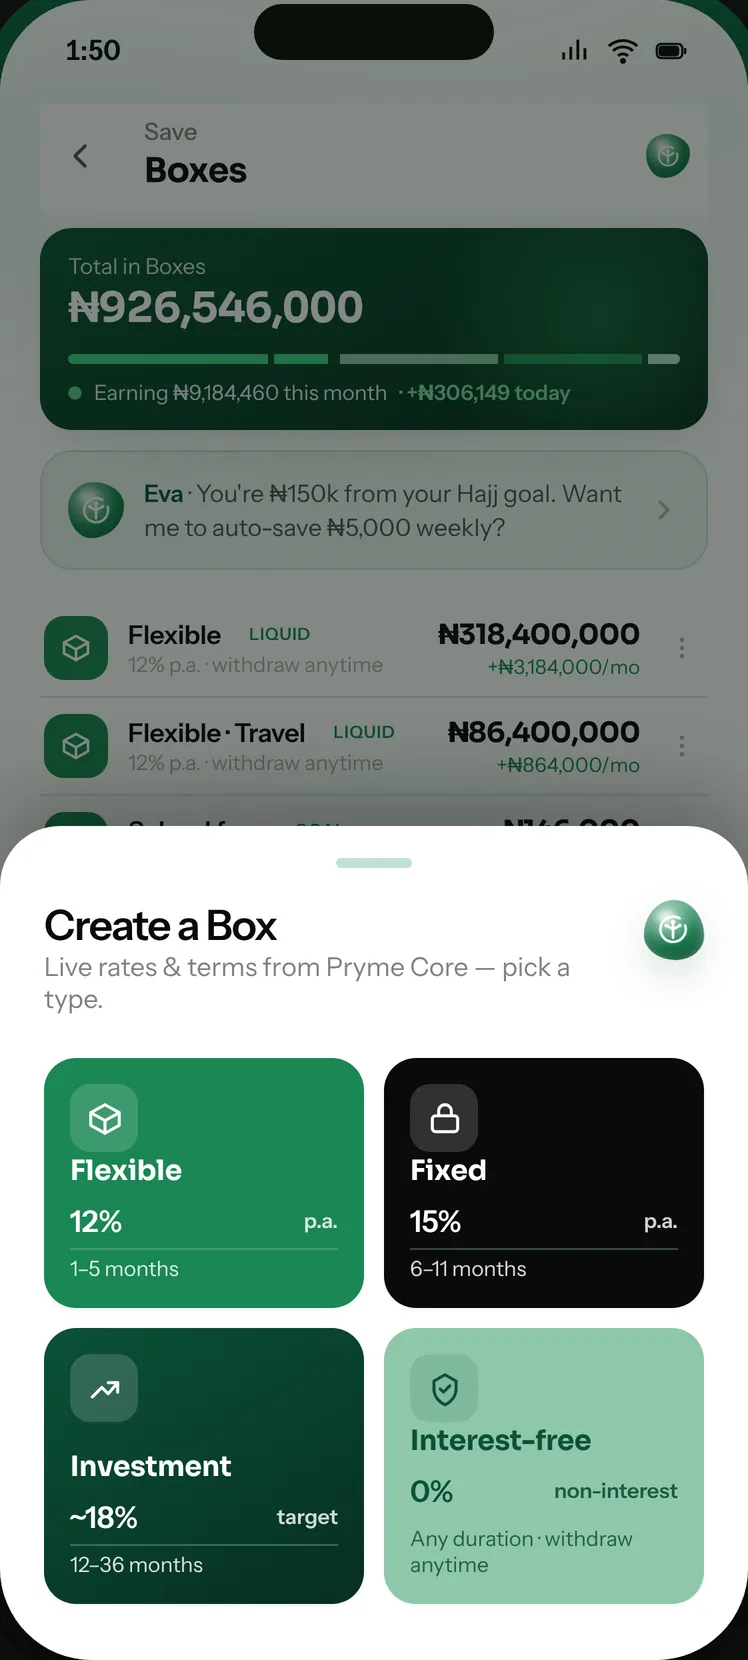
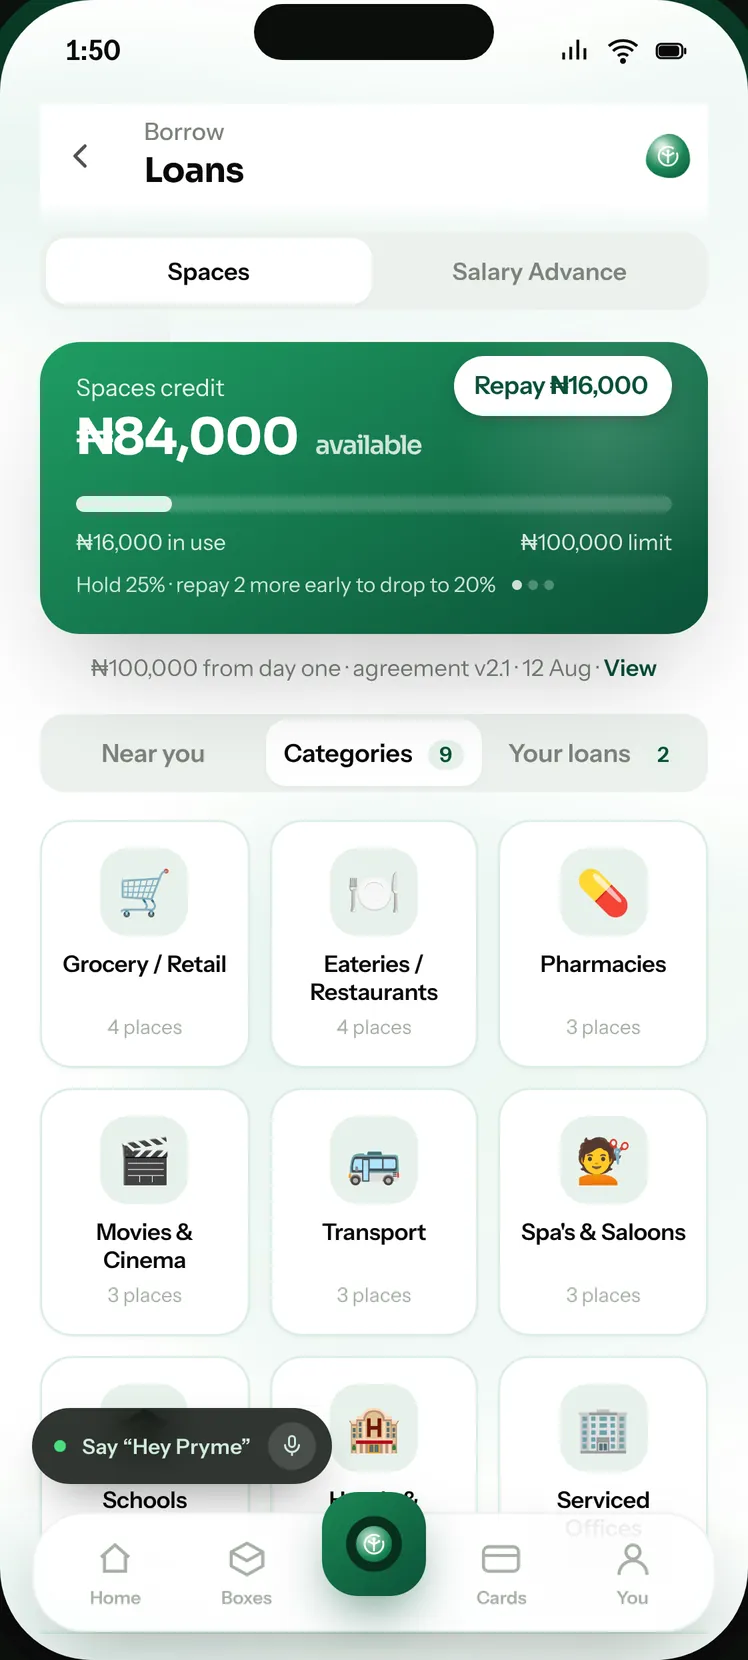
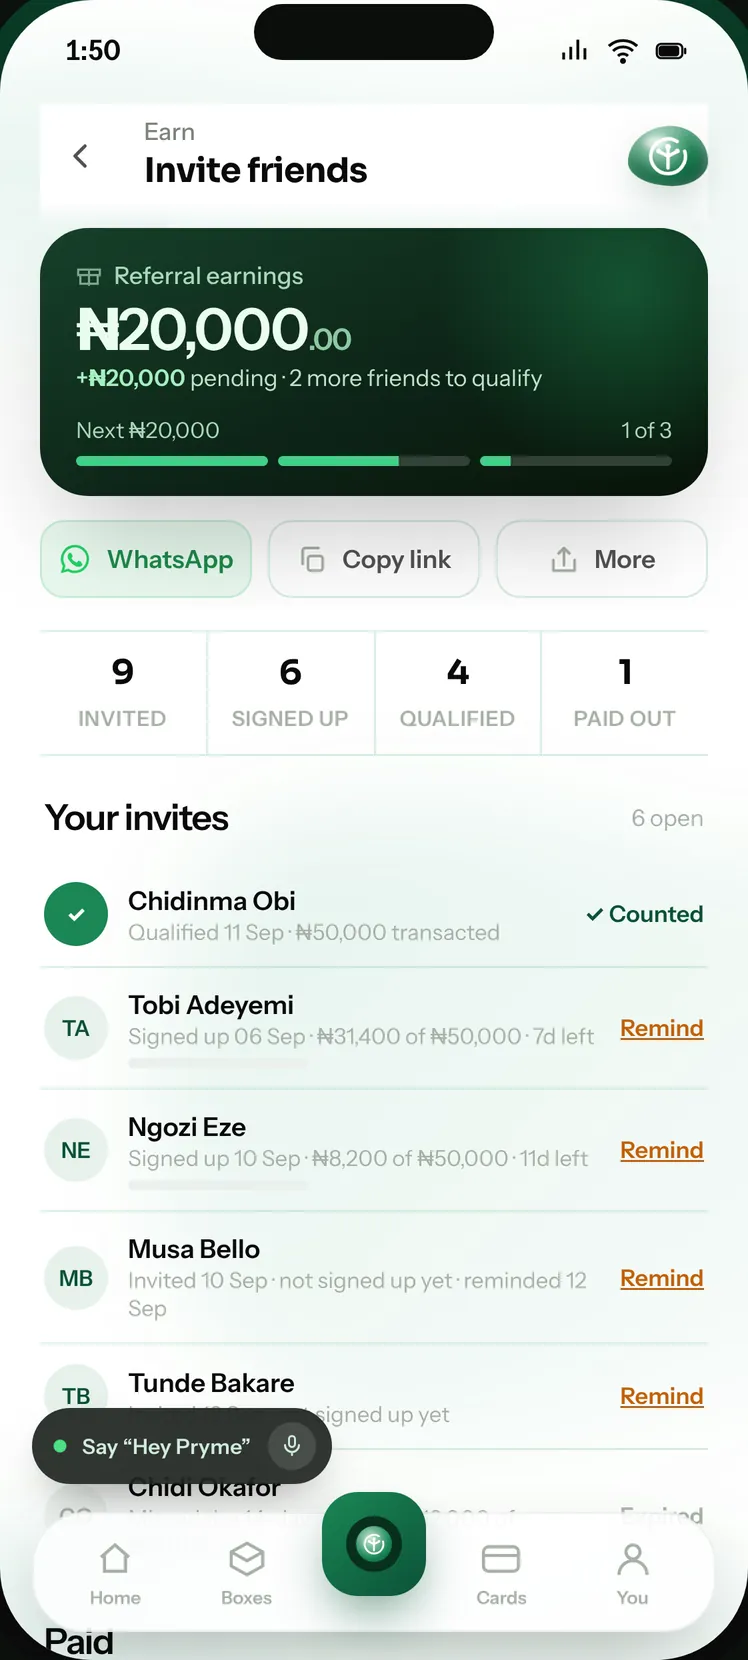
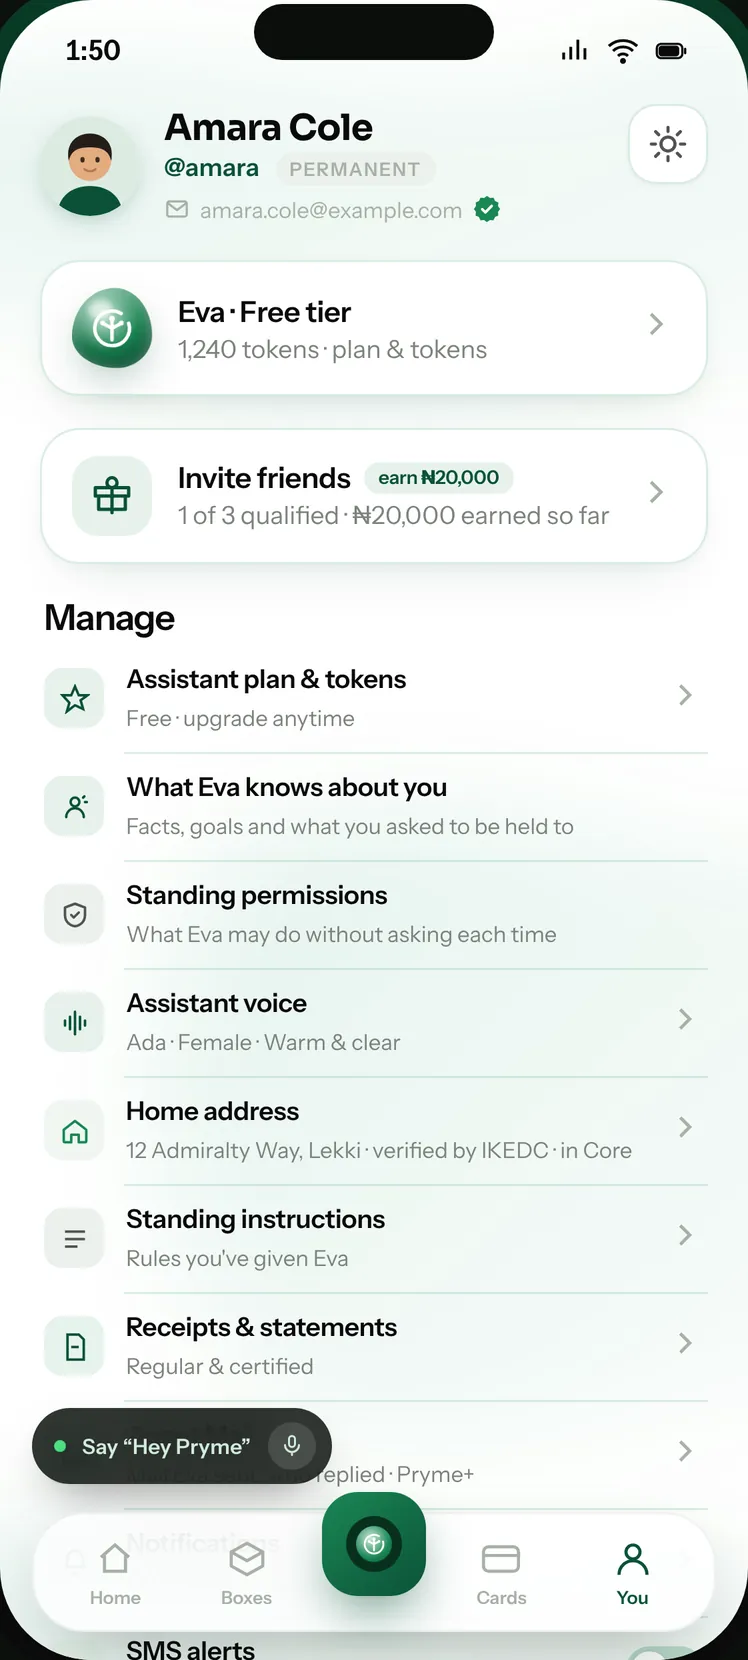
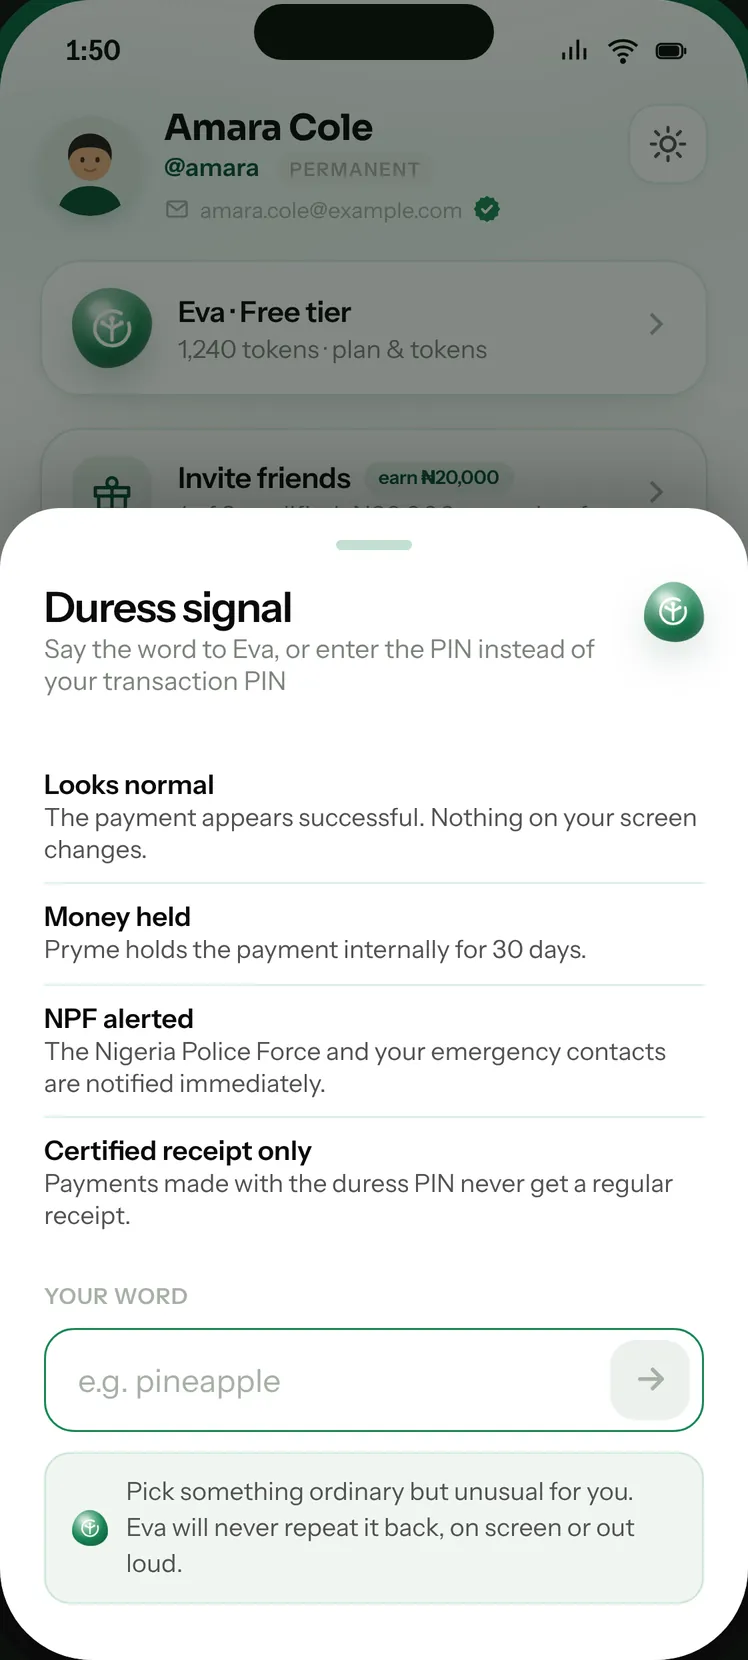
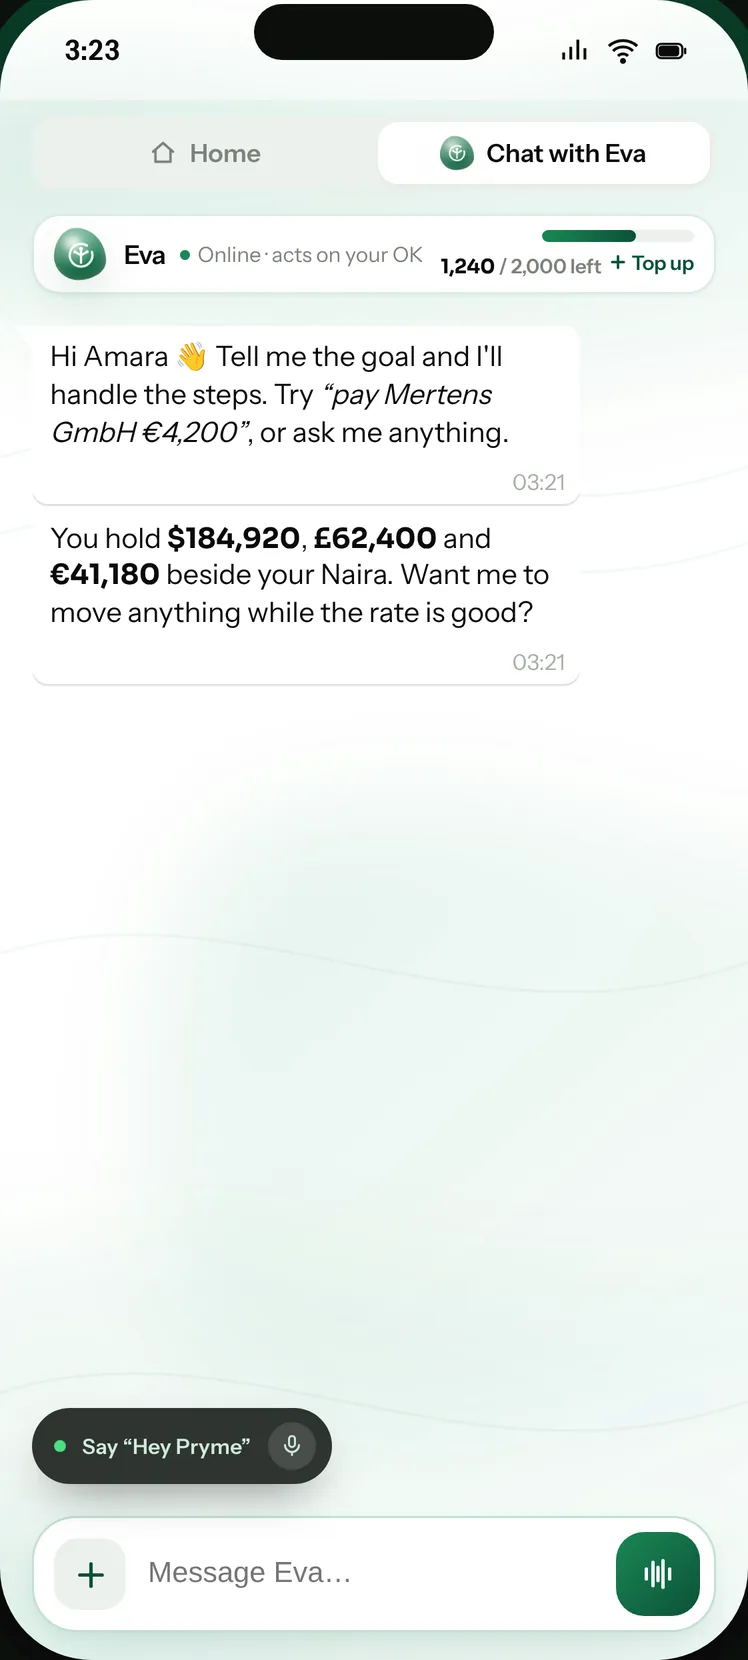
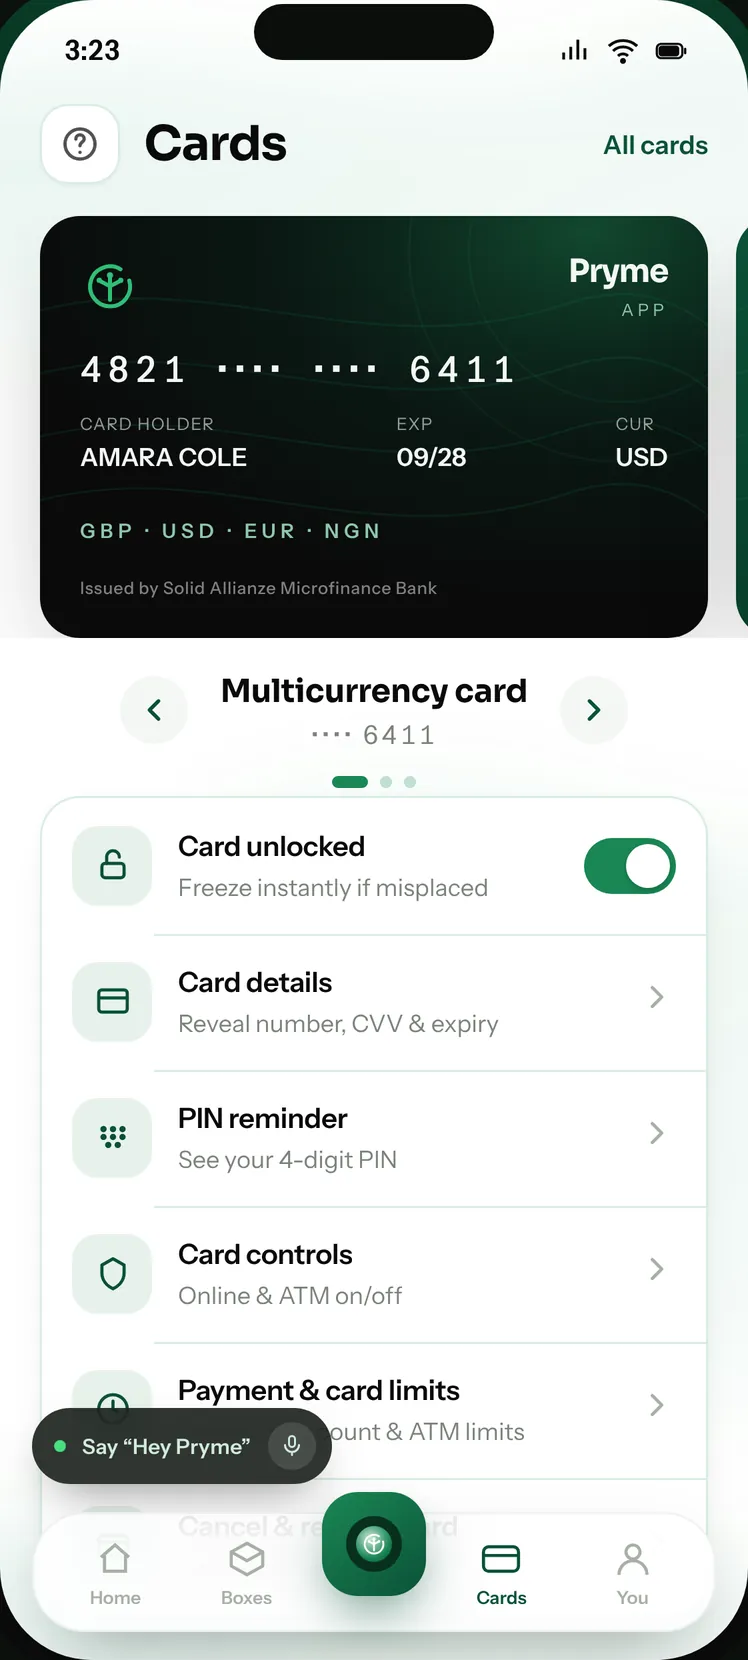
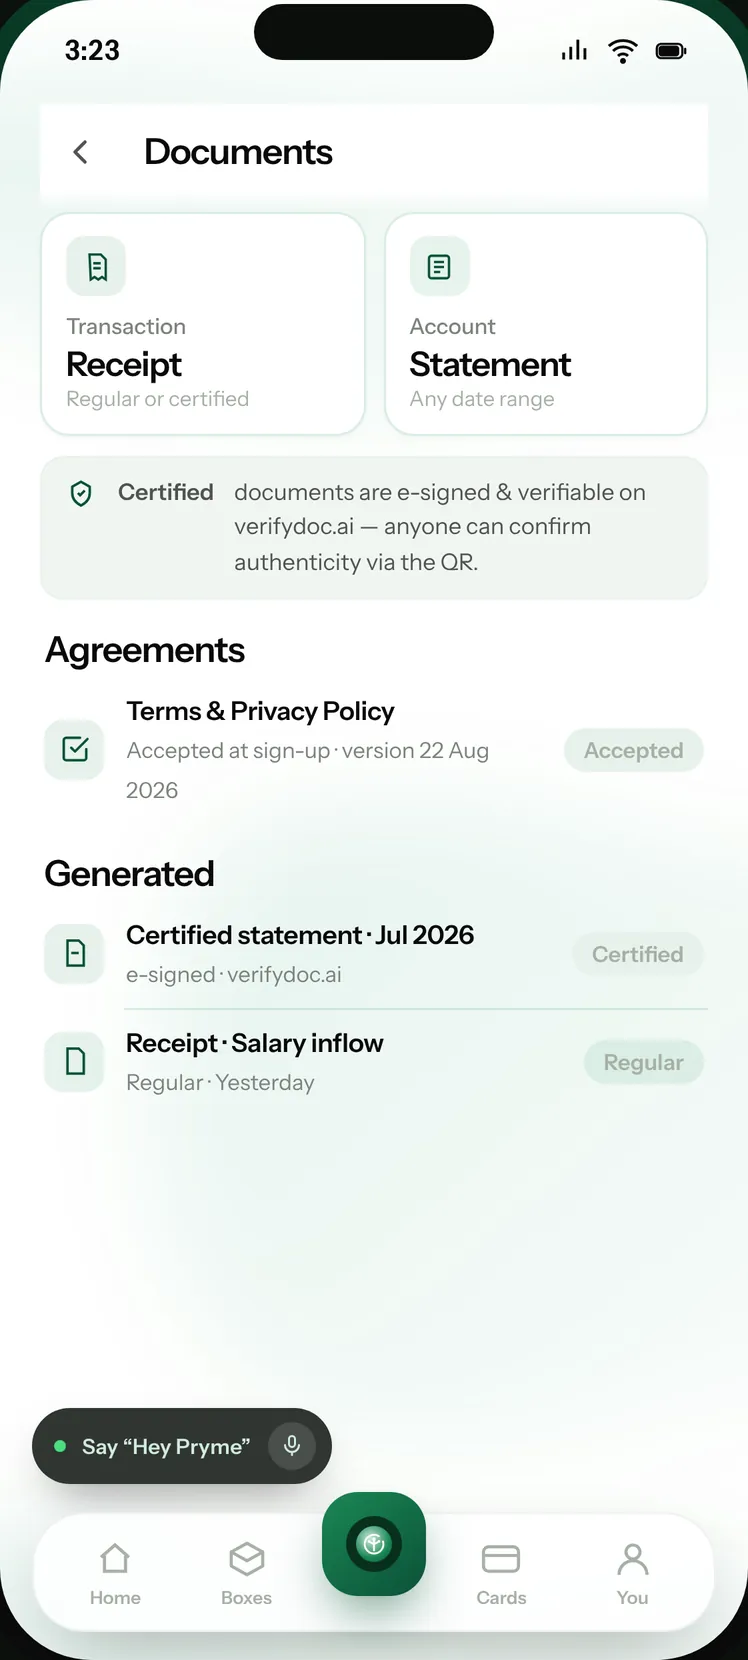
We give you a limit to spend at the shops and services you already use — and an account that works on your month while you get on with it. Dollars, pounds and euros sit beside your Naira, and an assistant handles the running of it, asking you first every single time.
One global account for your money and business. Move across currencies, automate everyday operations and put AI agents to work — with you in control of every important decision.
 Evayour assistant
 DanielChief of Staff
 BenFinance
 BruceCare
Your competitor down the road sells the same thing you sell. The difference is who walks in. We put money in people’s hands that can only be spent in businesses like yours — and then we point them at you.
You are not borrowing. You are selling to somebody who already has the money — and that money can only be spent with a business like yours.
₦100,000 from day one · agreement v2.1 · 12 Aug · View
Eva waits for your rate and asks before she moves anything.
No card, no OTP, nothing for the buyer to type in. They transfer from the bank app they already use, and the money lands in the same account your agents are running — already matched to the order, already in your books.
We give the buyer a one-time account number. They transfer to it from any bank app or by USSD — no card, no OTP, nothing to type in.
Get the account numberTo this account, from any bank app. We watch it, and the page updates itself.
₦26,767.50 from GTBank · John D., matched to order ORD‑1042.
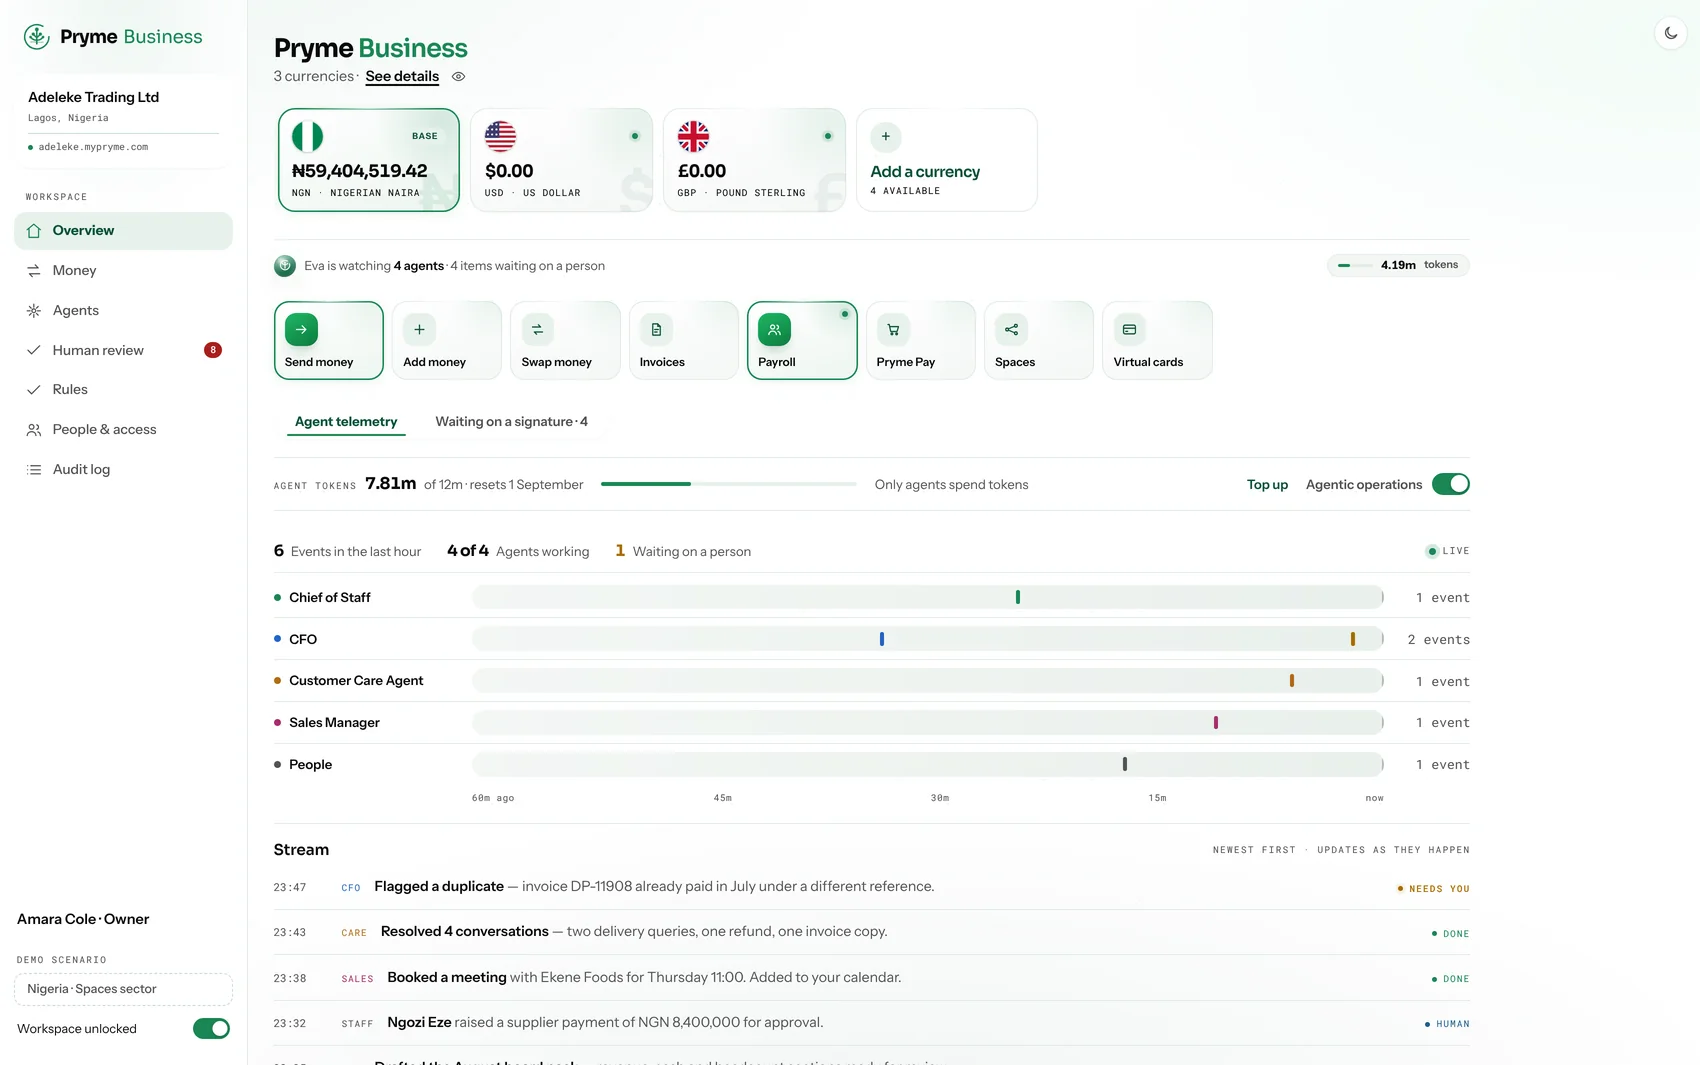
Five agents come with the account. Each one has a job description, a budget and a ceiling you set. They do the work and bring it to you — nothing leaves the account without your signature.
Knows what is stuck, who is waiting and what you promised — and keeps all three moving.
Booked a meeting with John Doe Foods for Thursday 11:00.Keeps the books as you trade and tells you the moment something does not add up.
Flagged a duplicate — invoice DP‑11908 was already paid in July.Holds every filing to its own clock and screens names and payments against your policy — and logs what it refuses.
Screened 412 payments overnight and refused two of them.Goes back to the buyers who went quiet, with the receipt already attached.
Recovered ₦410,000 across three overdue invoices.Replies, follows up on what they asked for and hands you only the ones that need you.
Resolved 4 conversations — two deliveries, one refund.Issue a dedicated Naira account number to each of your own customers, collect into it and reconcile against it. The same rails the Business Account runs on, with the licence behind them.
Dollars, pounds and euros beside a Naira account, on one ledger and one set of books. Five agents come with it and run the account — nothing leaves without your signature.
Five agents come with the account. Each has a job description, a budget and a ceiling you set. They do the work and bring it to you — they propose, you approve.
Knows what is stuck, who is waiting and what you promised, and keeps all three moving.
Booked the quarterly review with your auditor for Thursday.Keeps the books in every currency you hold and flags the moment something does not add up.
Flagged a duplicate — invoice DP‑11908 was already paid in July.Holds every filing to its own clock and screens names and payments against your policy — and logs what it refuses.
Screened 412 payments overnight and refused two of them.Goes back to the buyers who went quiet, with the invoice and the receipt already attached.
Recovered $12,400 across three overdue invoices.Replies, follows up on what they asked for and hands you only the ones that need you.
Resolved 4 conversations — two deliveries, one refund.The business has changed shape four times and never changed what it was rooted in. Each version was built out of what the last one could not do.
An online grocery store, built out of a faulty tab. Selling the food was the easy part — taking the money for it, and moving it, turned out to be the business.
A prepaid card. The first time the company issued rather than resold, and the first time it carried the obligations that come with holding somebody else’s money.
Solid Allianze acquired — an existing bank with an existing licence. The perimeter stopped being someone else’s to draw.
More than one currency on one balance, and the rebrand to Pryme. A Nigerian business could hold dollars without holding a second institution.
Accounts that do the work rather than only hold value. Five agents on the account, inside a policy you write — which is where the new mark starts.
Pryme is a financial technology company. It gives people and businesses in Nigeria one account that holds Naira alongside dollars, pounds and euros, and a set of agents that do the running of it — keeping the books, chasing what is owed, answering customers and paying bills. Nothing leaves an account without the owner’s approval.
Yes. A Pryme account holds Naira, US dollars, pounds sterling and euros side by side on one ledger, each with its own account details — a Nigerian account number, a US account number, a UK sort code and an IBAN for the euro area. You can swap between them at a rate you set, and every currency has its own statement.
Spaces is available in Nigeria. It gives a shopper money to spend that can only be spent with a participating business. The business is paid into its Naira account whether or not the shopper repays, because Pryme carries the credit. For the business it is free to join, there is nothing monthly, and the customer’s identity is never shown — only a reference and what it is worth.
Five agents come with the account. The Chief of Staff runs the week and keeps what is stuck moving. Finance watches the money and keeps the books as you trade. Compliance keeps the filings on time and screens what moves. Sales chases what you are owed. Customer Support answers your customers and follows up. Each has a job description, a budget and a ceiling you set, and each one proposes rather than acts — nothing leaves the account without your signature.
Pryme Pay takes payments on your own site or on a checkout page you control. The buyer is given a one-time account number and transfers to it from any bank app or by USSD — no card, no OTP, nothing to type in. The money lands in the same account your agents are running, already matched to the order and already in your books.
Savings Boxes are separate pots inside a Pryme account, held in Naira. Flexible Boxes can be withdrawn at any time, Fixed Boxes hold to a date, Investment Boxes hold for longer, and Interest-free Boxes earn nothing by design. A business can use them to ring-fence payroll and the tax it withholds, so that money cannot be spent by accident.
Pryme is a financial technology company, not a bank. Accounts and deposits are provided by Solid Allianze Microfinance Bank Limited, which is licensed by the Central Bank of Nigeria and is a member of the Nigeria Deposit Insurance Corporation.
Yes. Pryme Rails lets a platform issue a dedicated Naira account number to each of its own customers, collect into it and reconcile against it, over one API — the same rails the Pryme Business Account runs on.
Pryme is a financial technology company. It gives you one account that holds US dollars, pounds sterling and euros beside Naira, with an assistant that runs the account for you and asks before anything moves. Accounts are provided in Nigeria today, and further markets open as each licence lands.
Accounts are provided in Nigeria today, subject to verification and approval. Foreign-currency balances are held and converted inside that account, so you can hold, receive and swap dollars, pounds and euros wherever you are.
Naira, US dollars, pounds sterling and euros, side by side on one ledger. Each has its own details — a Nigerian account number, a US account number, a UK sort code and an IBAN for the euro area — and each has its own statement.
Swap at a rate you set rather than the rate of the day, then send to any Pryme username or to a Nigerian bank account. There is no fee to send to another Pryme account.
Eva is the assistant inside the Pryme app. She opens accounts, moves money, saves toward your goals, pays what is due and follows up what is owed to you — and asks you before anything moves.
Pryme Rails lets a platform issue a dedicated Naira account number to each of its own customers, collect into it and reconcile against it, over one API — the same rails the Pryme Business Account runs on.
Notes on money that does the work: what we are building, what the regulation actually says, and how we think about letting software act on money. Read the Ledger
What AI agents can do in bookkeeping, close, collections and compliance today, where a person must stay in charge, and how to judge a product.
How multi-currency business accounts work: local details vs SWIFT, payment rails, the real cost of FX, safeguarding vs deposit protection, and hedging.
How UK, US, Canadian and European firms pay Nigerian suppliers and get paid by Nigerian clients: FX, Form A and M, tax, compliance and payout routes.
What it really costs to send money to Nigeria from the UK, US, Canada and Europe: fees, exchange-rate margins, CBN naira rules, BVN, speed and scams.
What AI can and cannot do in day-to-day bookkeeping, how much time it saves on real numbers, and which jobs must stay with you or your accountant.
OPay's Target savings helps you save towards a goal. How to plan the amount and frequency, what OPay leaves to the app, and the rules to check.
OPay Target is a goal-based savings plan in the OPay app, listed by OPay alongside OWealth, Fixed, Spend & Save and SafeBox and powered by OPay Microfinance Bank. You set a goal amount and date and save towards it, manually or on a schedule; OPay does not publish its Target withdrawal rules or rates on its website, so check the plan's terms in the app before you start.
A target plan is built around a number and a date: "₦600,000 for rent by March" or "₦150,000 for a new phone by December". The app holds the money separately from your spending balance, so you are less likely to dip into it, and it tracks progress towards the goal. OPay's App Store listing names Target among its savings products and says they are powered by OPay Microfinance Bank.
Target plans suit people paid irregularly as well as salary earners, because you can usually add money whenever you have it as well as on a fixed schedule. They are a digital cousin of the thrift contributions many Nigerians already know; our article on ajo, esusu and savings apps compares the two.
Example only. Chidi wants ₦500,000 for school fees due in 40 weeks.
| Frequency | Amount each time | Check |
|---|---|---|
| Weekly (40 deposits) | ₦12,500 | ₦12,500 × 40 = ₦500,000 |
| Monthly (about 9 deposits) | ₦55,556 | ₦55,556 × 9 = ₦500,004 |
| Daily (280 days) | ₦1,786 | ₦1,786 × 280 = ₦500,080 |
Any interest earned would be a bonus on top, but plan the deposits to reach the goal without it. If interest is paid only when you complete the target, as some apps do, missing the goal may mean receiving none. For school fees specifically, see our term-by-term plan.
Most target features let you choose whether the app debits your main balance automatically on a schedule. OPay's public pages do not describe the exact setup screens, so follow the prompts in the app. The steps below are what to look for.
OPay does not publish its Target withdrawal rules on its website, and its help pages were not readable when we checked in October 2026. Other apps show how much these rules differ, so read OPay's terms with these in mind (each is that app's own rule, not OPay's):
So the questions for OPay's Target are: can you withdraw part of the balance, does breaking cost a fee as well as interest, what happens if you reach the date without hitting the goal, and can you change the goal amount or date once the plan is running.
Most target plans fail for ordinary reasons: a deposit date that falls before payday, a goal set too high, or a single large expense that tempts you to break the plan. Three habits help. Set the goal slightly above what you need, so a missed week does not derail it. Review the plan monthly and adjust the amount rather than abandoning the goal. And keep a small emergency balance outside the target, so the plan is not the first place you look when something goes wrong.
If you share a goal with a spouse or relative, check whether the app allows group or shared targets; OPay's public pages do not mention one, so for a family goal you may need separate plans and a clear agreement about who pays in what.
OPay's website carries the statement "Licensed by CBN and Insured by NDIC", and the CBN lists OPay Digital Services Limited as a mobile money operator. Savings are described as powered by OPay Microfinance Bank. NDIC cover for microfinance bank deposits rose to ₦2,000,000 per depositor in May 2024, according to Arise News. See which savings apps are NDIC-insured for how cover works across apps.
Finally, note the date your target ends and what happens to the money then. Some apps move a completed target back to your main balance; others leave it in the plan until you act. If the money is earmarked for a payment such as rent or fees, plan to make that payment within a few days of maturity, so the sum does not drift back into everyday spending.
Pryme's naira Savings Boxes let you keep a separate Box for each goal, and the Personal Assistant can remind you when a deposit is due; it prepares, and nothing moves until you approve.
Open savings in the OPay app, choose Target, enter the goal amount, date and saving frequency, choose whether to save automatically, read the terms and confirm.
OPay does not publish the rule on its website. The plan's terms in the app say whether early withdrawal is allowed and what it costs.
OPay does not publish Target rates on its website. Any rate is shown in the app when you set up the plan.
Check the plan's terms. Some apps, such as PiggyVest, pay no interest if you miss the target by maturity; OPay's rule is shown in the app.
This article is general information, not financial, legal or tax advice. Products described are provided under the terms on this site and are subject to regulation and eligibility.
You open a CSCS account and get a Clearing House Number through an accredited stockbroker. What to bring, what it costs and why you need one CHN.
The usual in-app steps for a fixed deposit or locked savings plan in Nigeria, and the five details to check before you tap confirm.
What Nigerians abroad need to place a naira fixed deposit: a BVN or NRBVN, a Nigerian account, certified documents, and the currency question.
You can add the other type later — many of our customers hold both.
The business first, then you. Nothing is submitted until you review it.
Ideal customer profiles
Generated from your website by VerifiedLead.ai
Pick the ones that look right. Your Sales agent works these first, and you can change them at any time after opening.
We ask this because you have not given us a website. It helps us set the right limits from day one.
Which of these represents you?
Officers listed against this company on the UK register.
We have sent a six-digit code to your email address. Enter it below to confirm the address is yours.
Wrong address? Go back and change it — nothing is created until this step passes. We never ask for a code by phone or email; anyone who does is not us.
Last step. Each time you sign in we email you a six-digit code — we never send codes by SMS.