AI agents for business finance: what they can and can't do
What AI agents can do in bookkeeping, close, collections and compliance today, where a person must stay in charge, and how to judge a product.
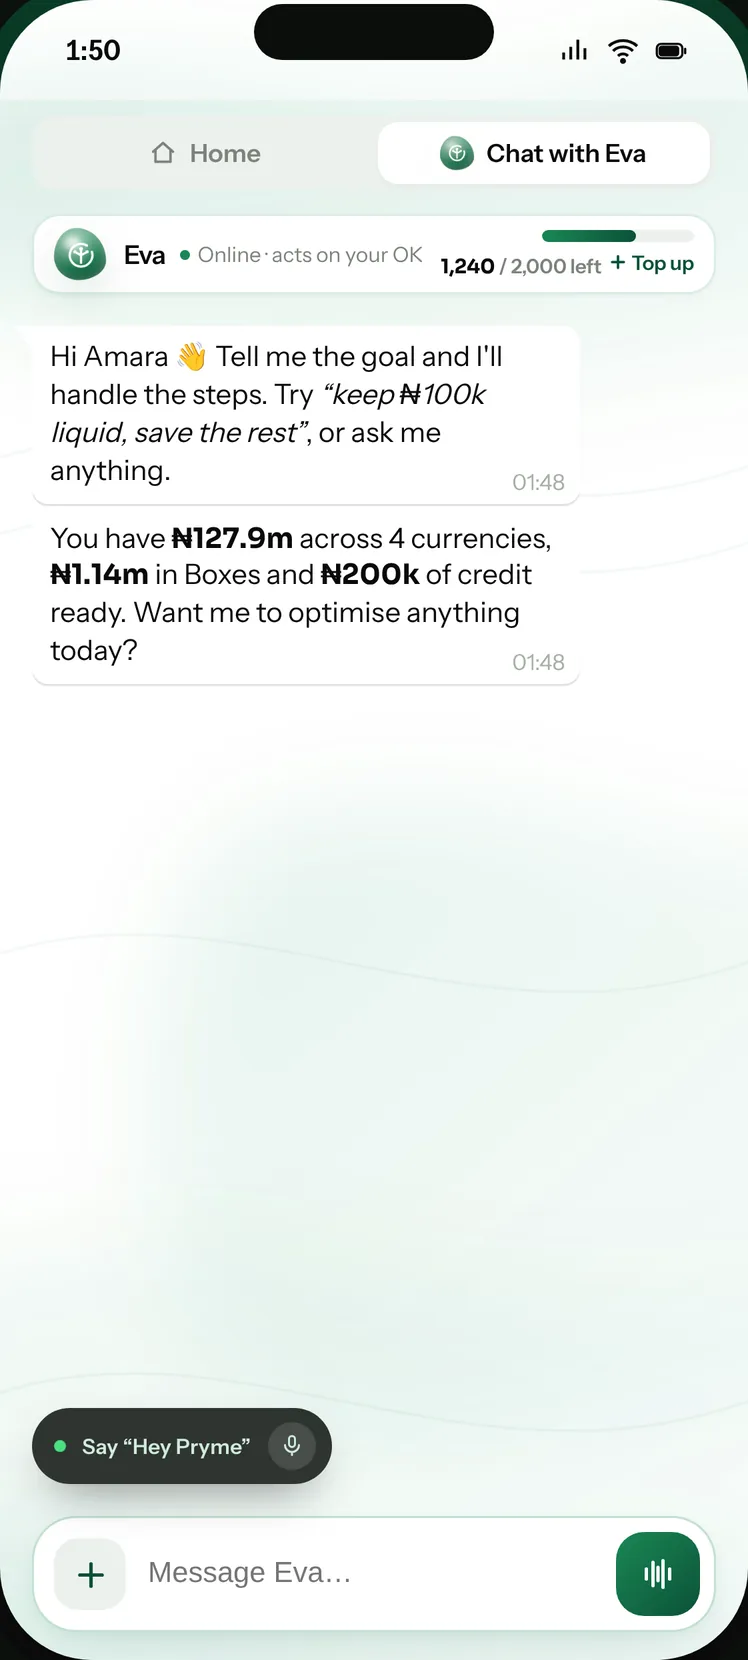
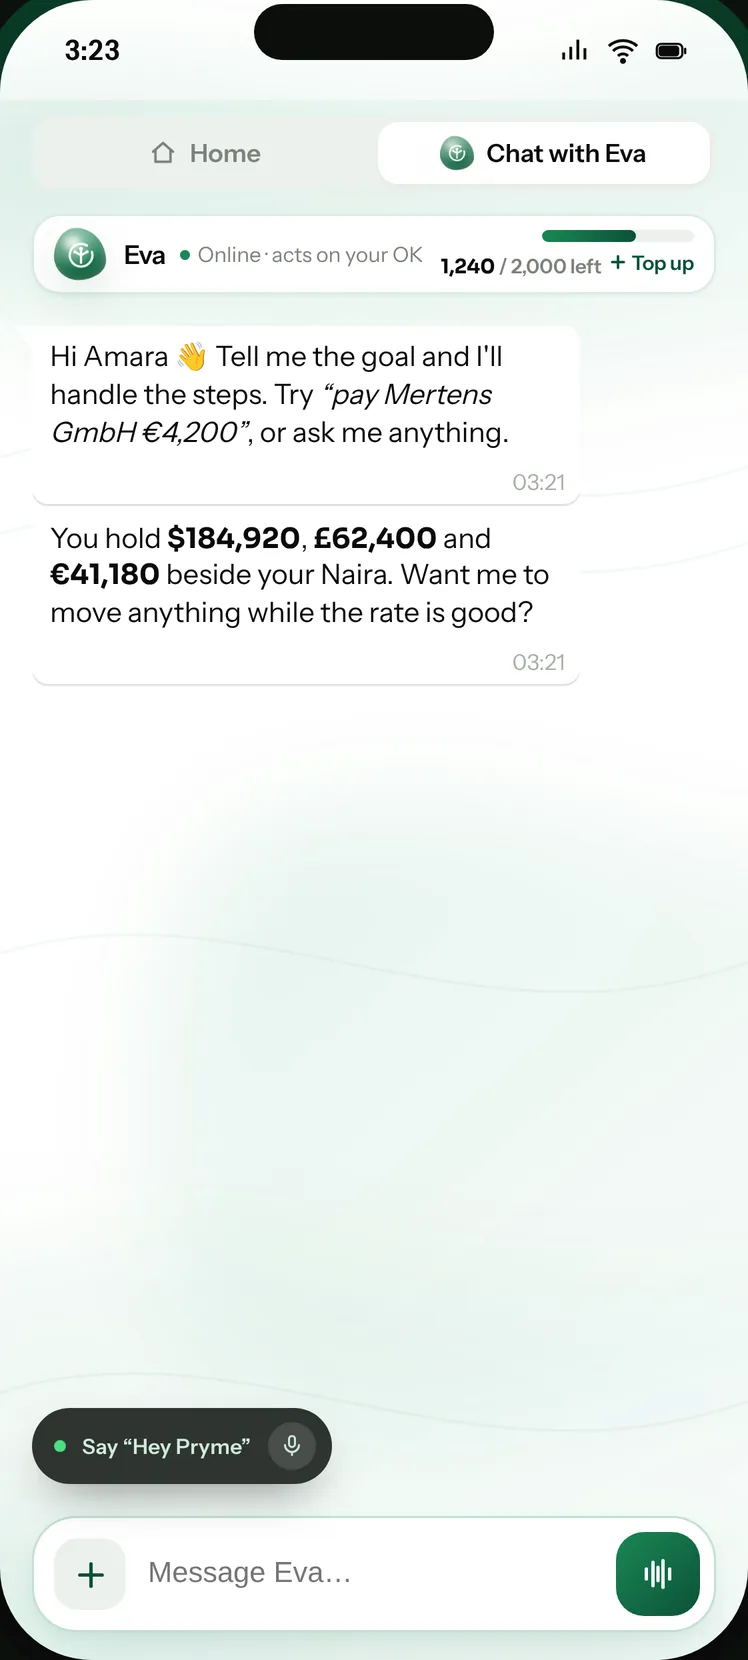
Meet Eva, the assistant inside the Pryme app. She opens accounts, moves money, saves toward your goals and follows up. Nothing leaves your account without your approval.
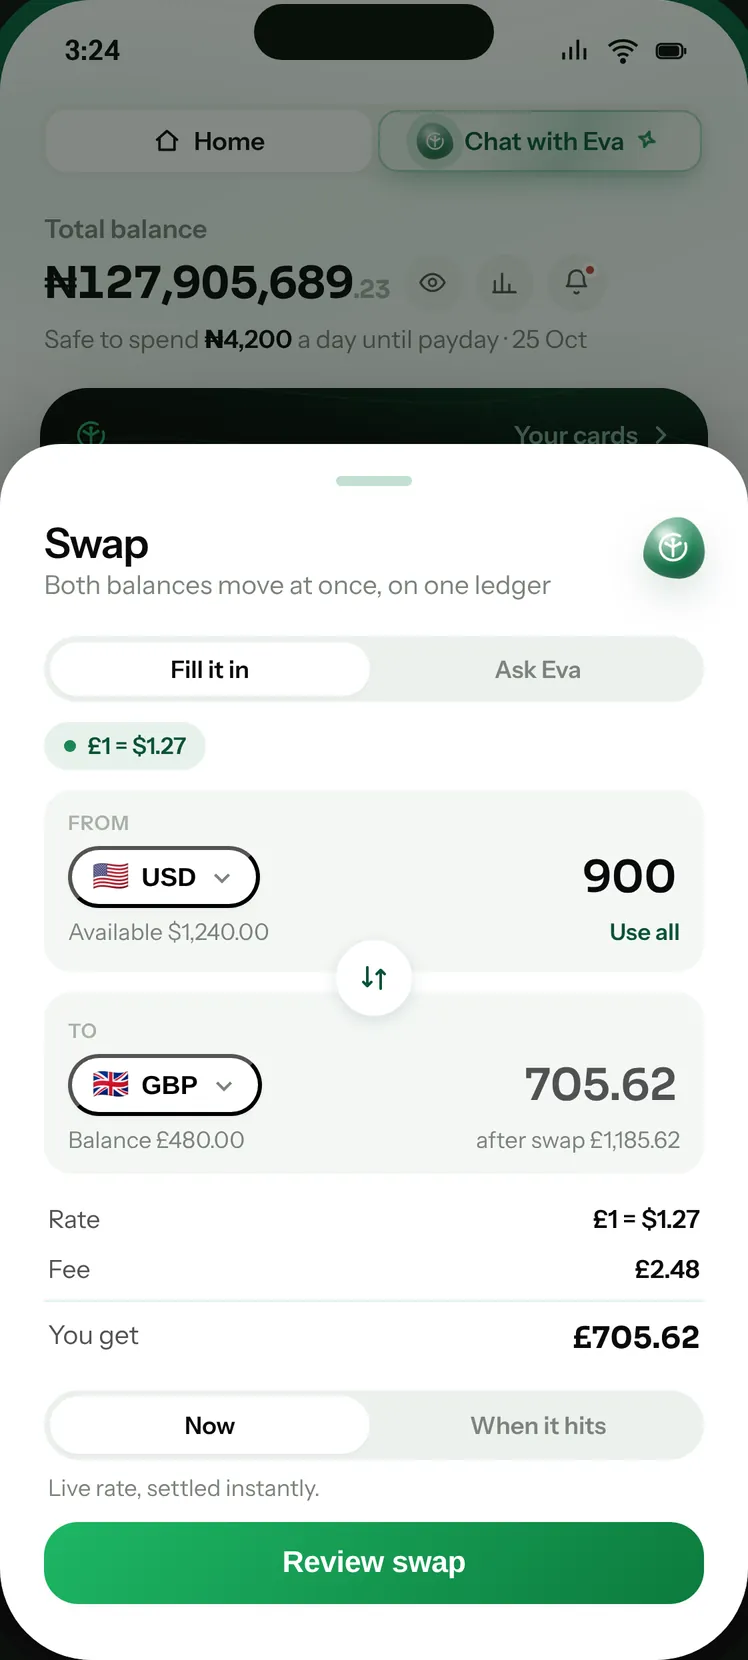
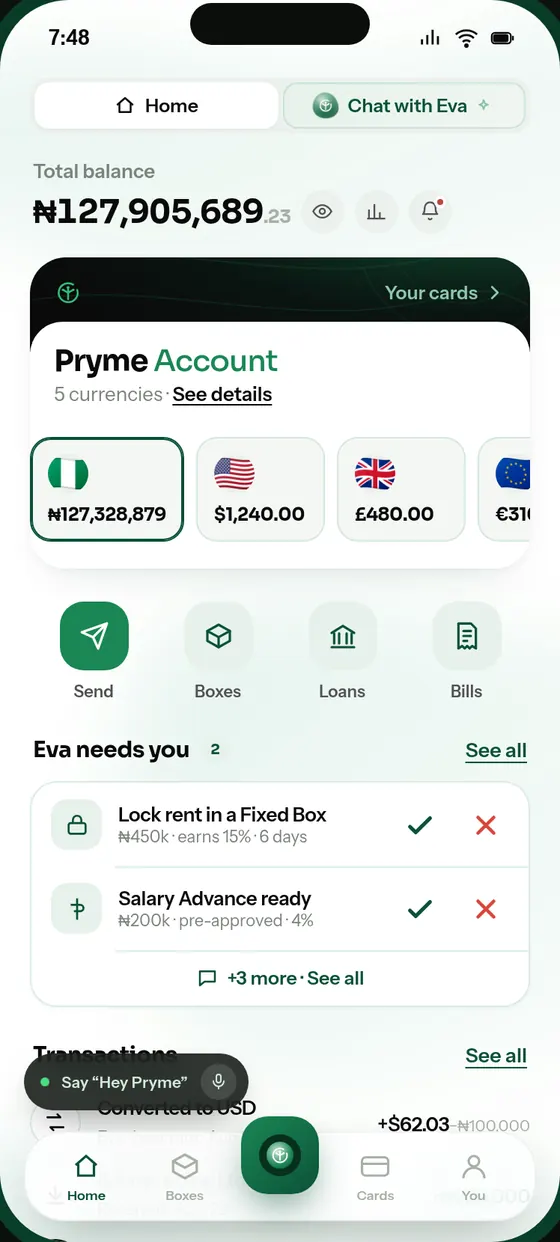
Meet Eva, the assistant inside the Pryme app. She holds dollars, pounds, euros and Naira side by side, swaps at a locked rate, pays bills in any of them and sends anywhere, asking before anything moves.
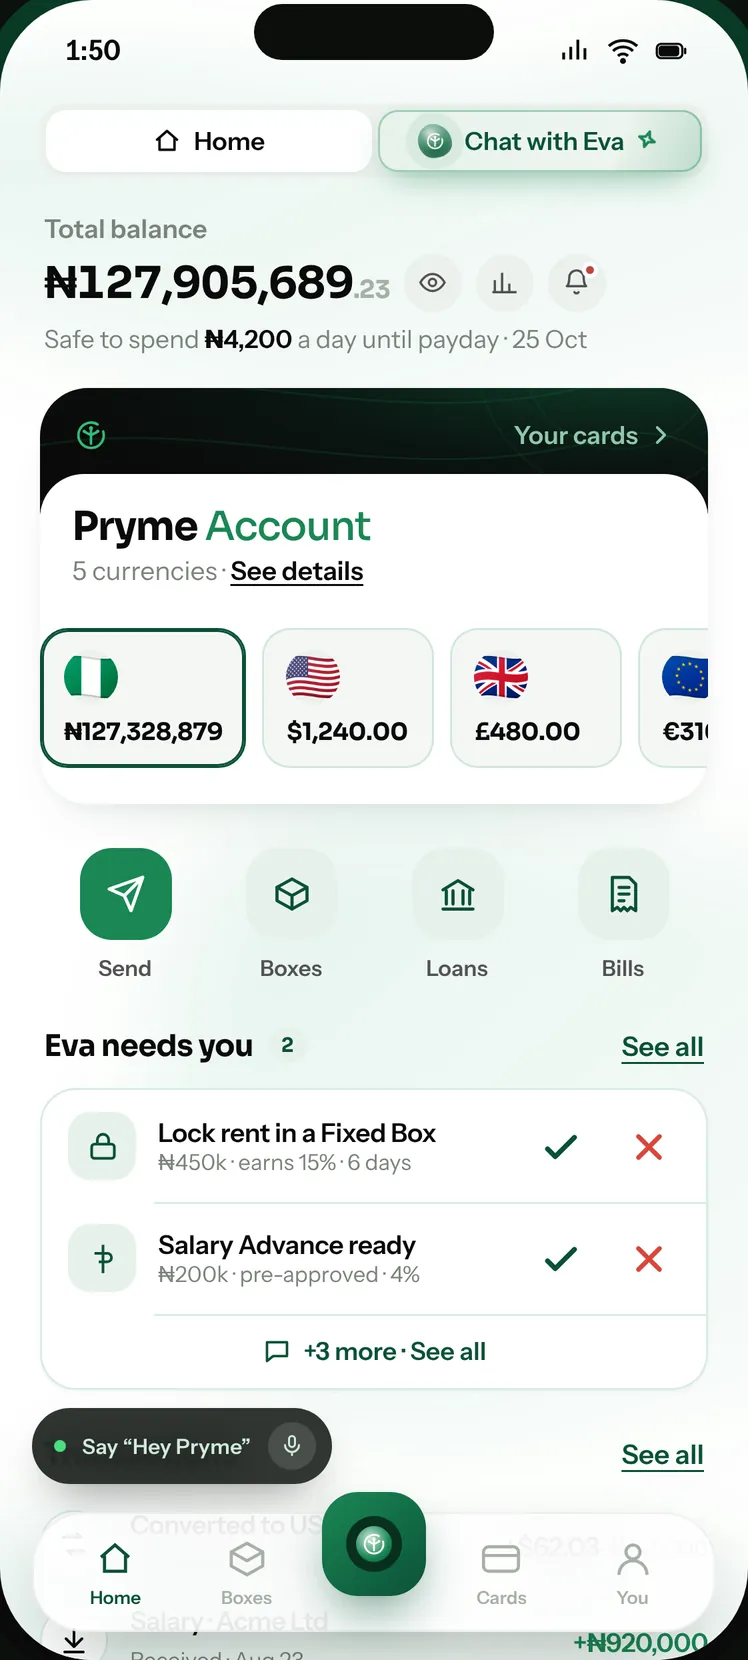
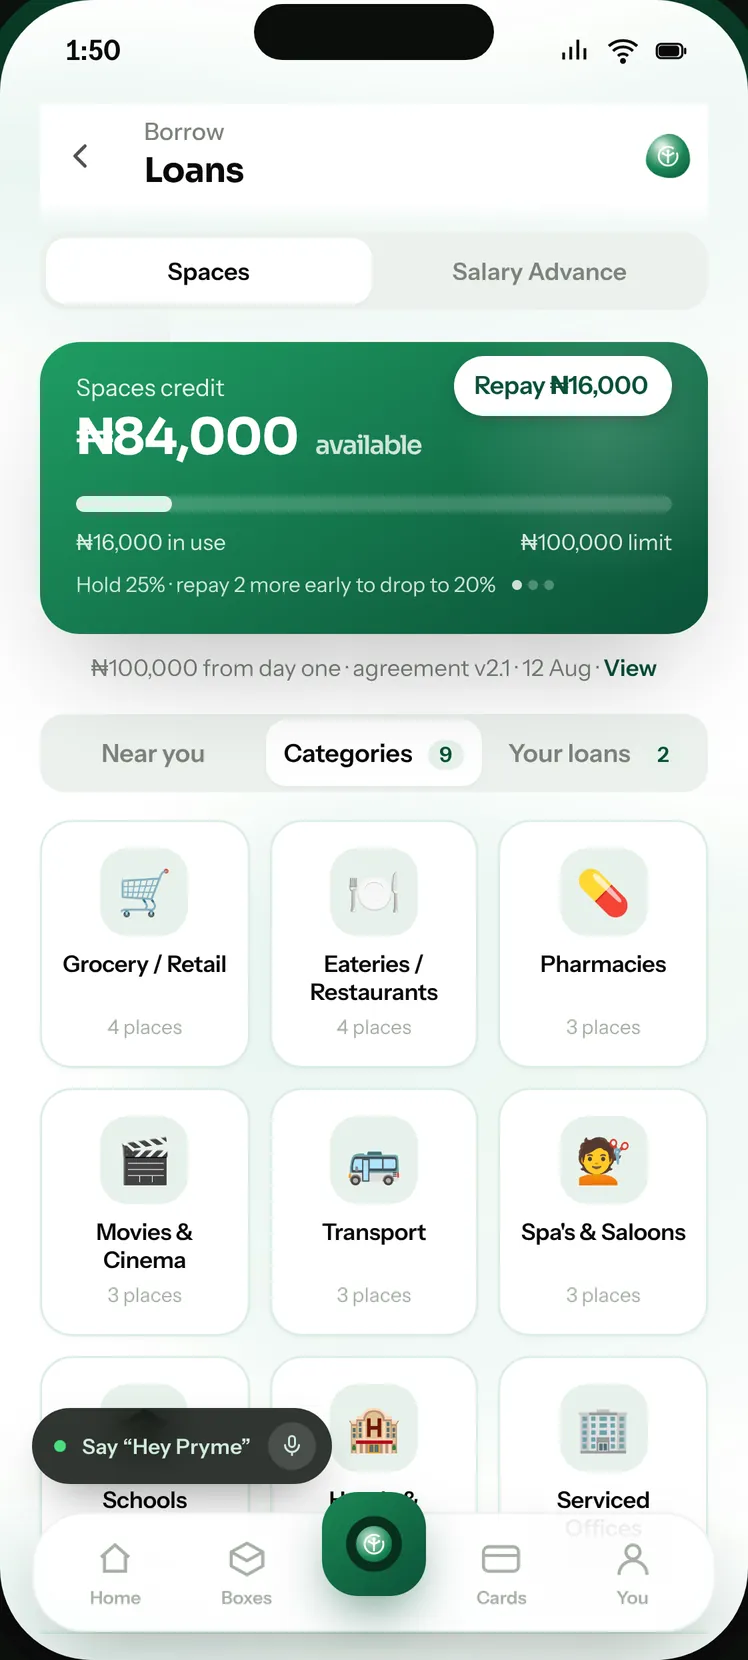
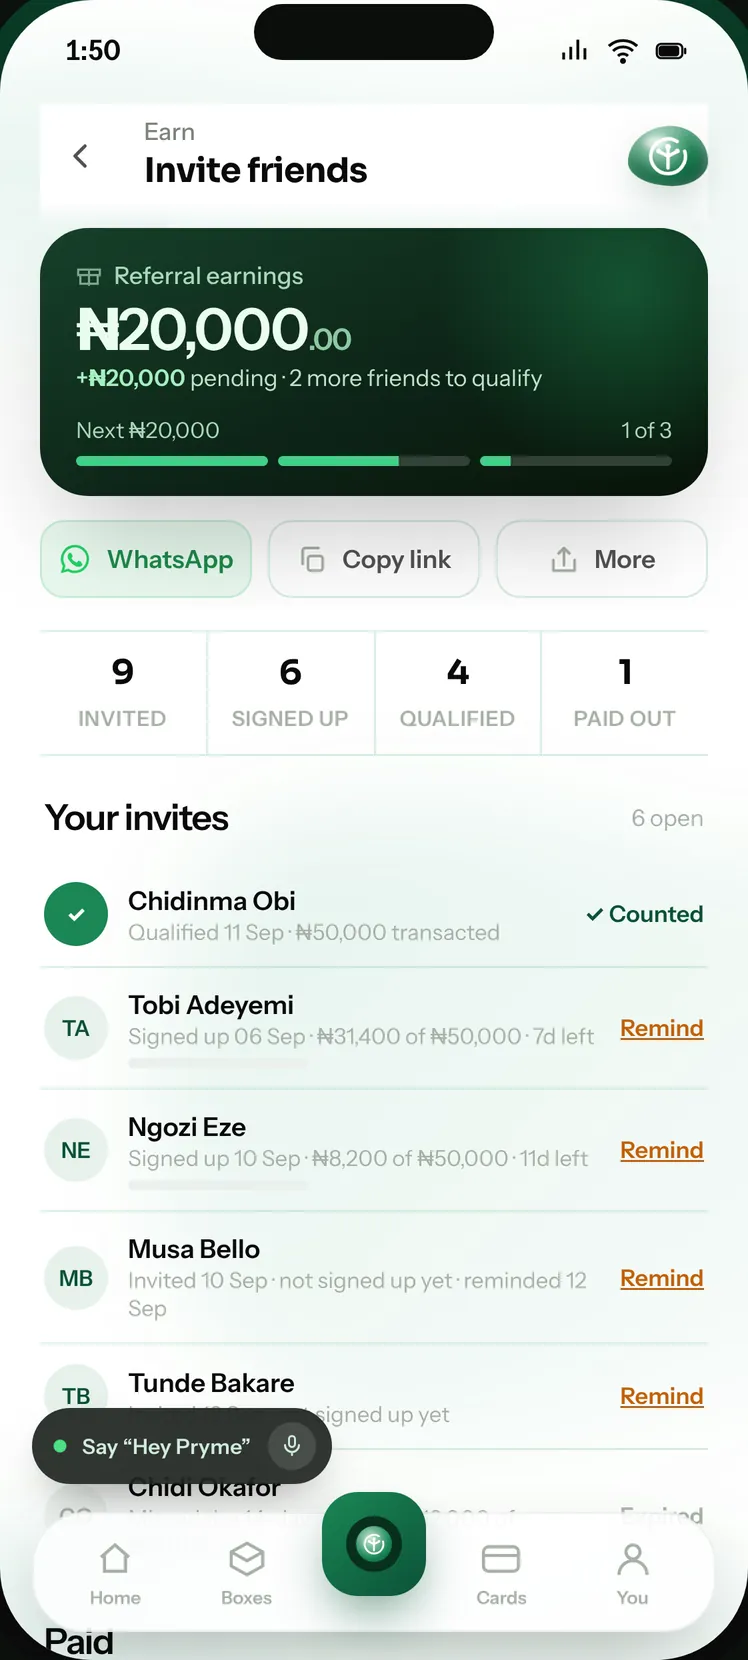
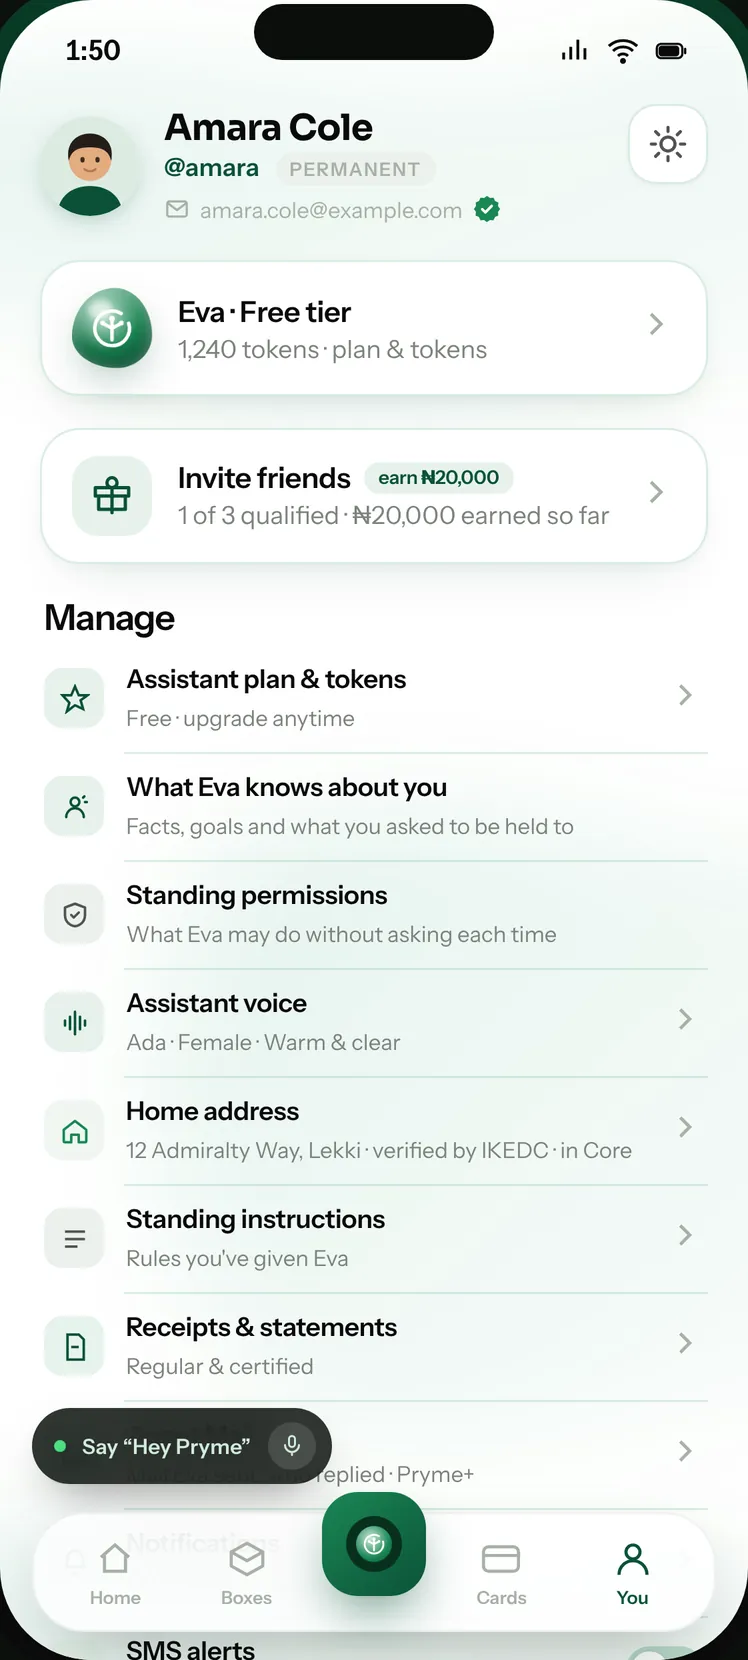
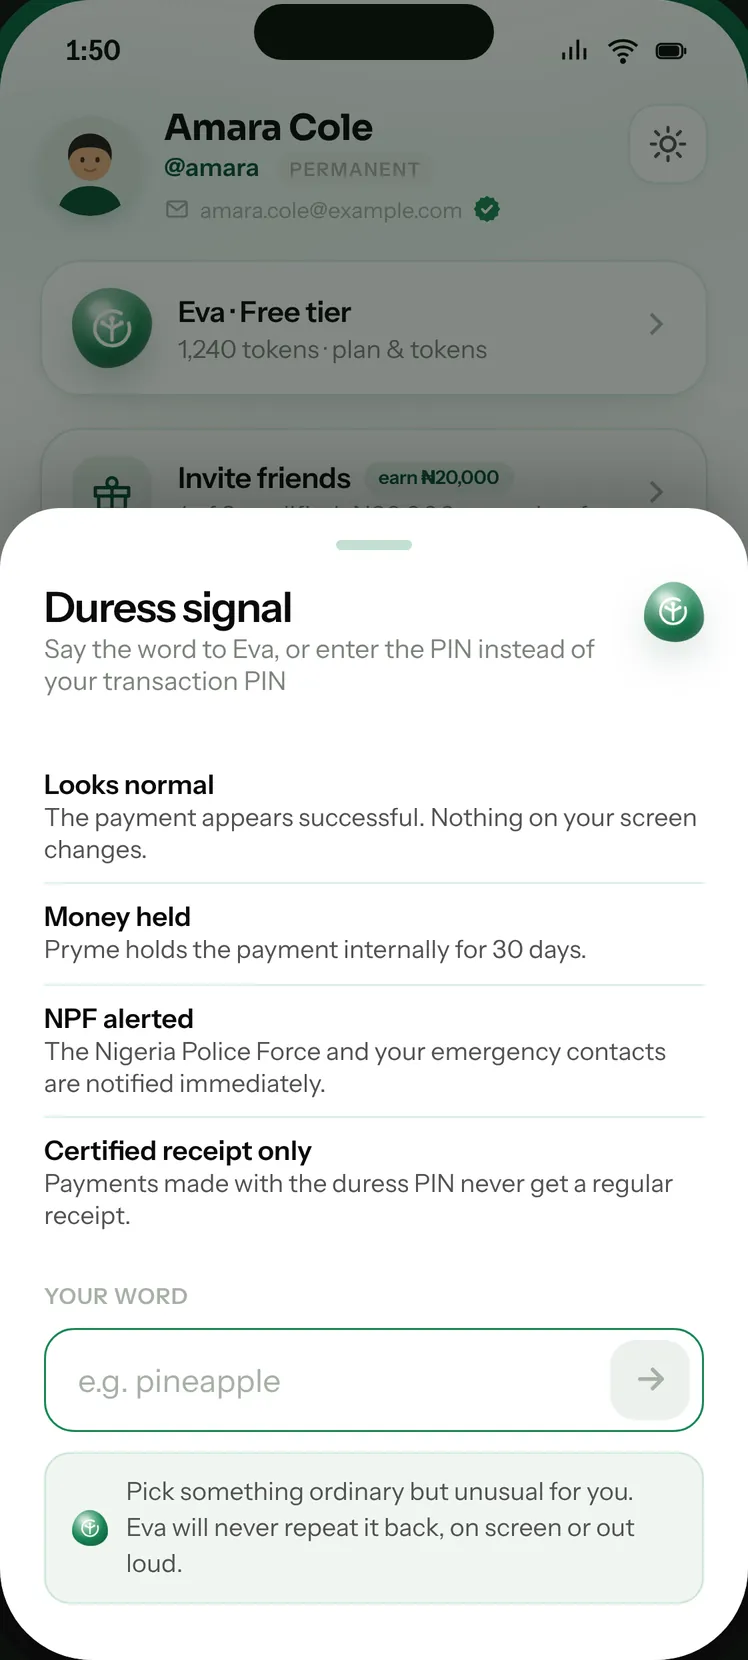
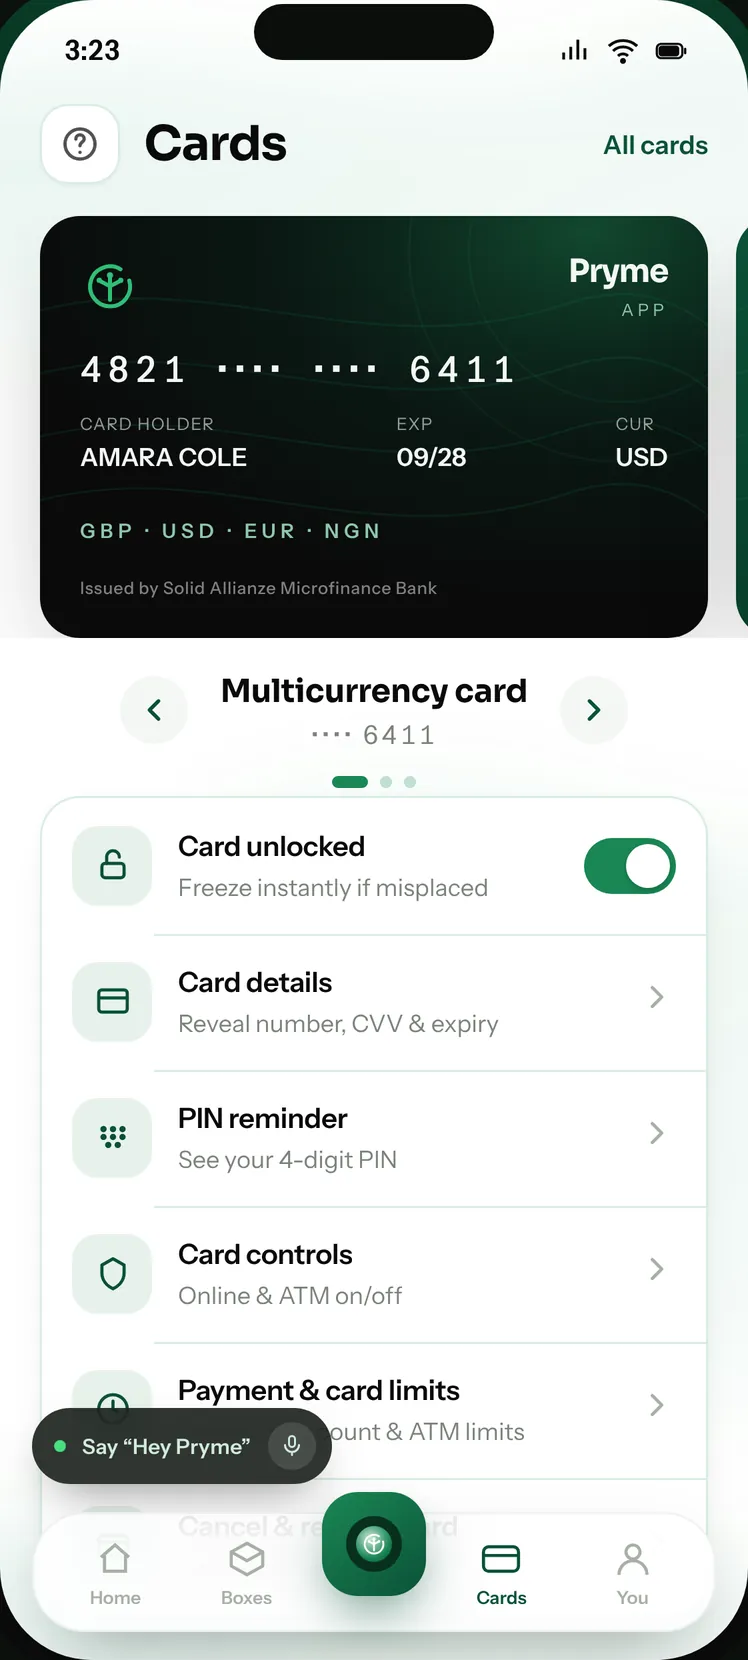
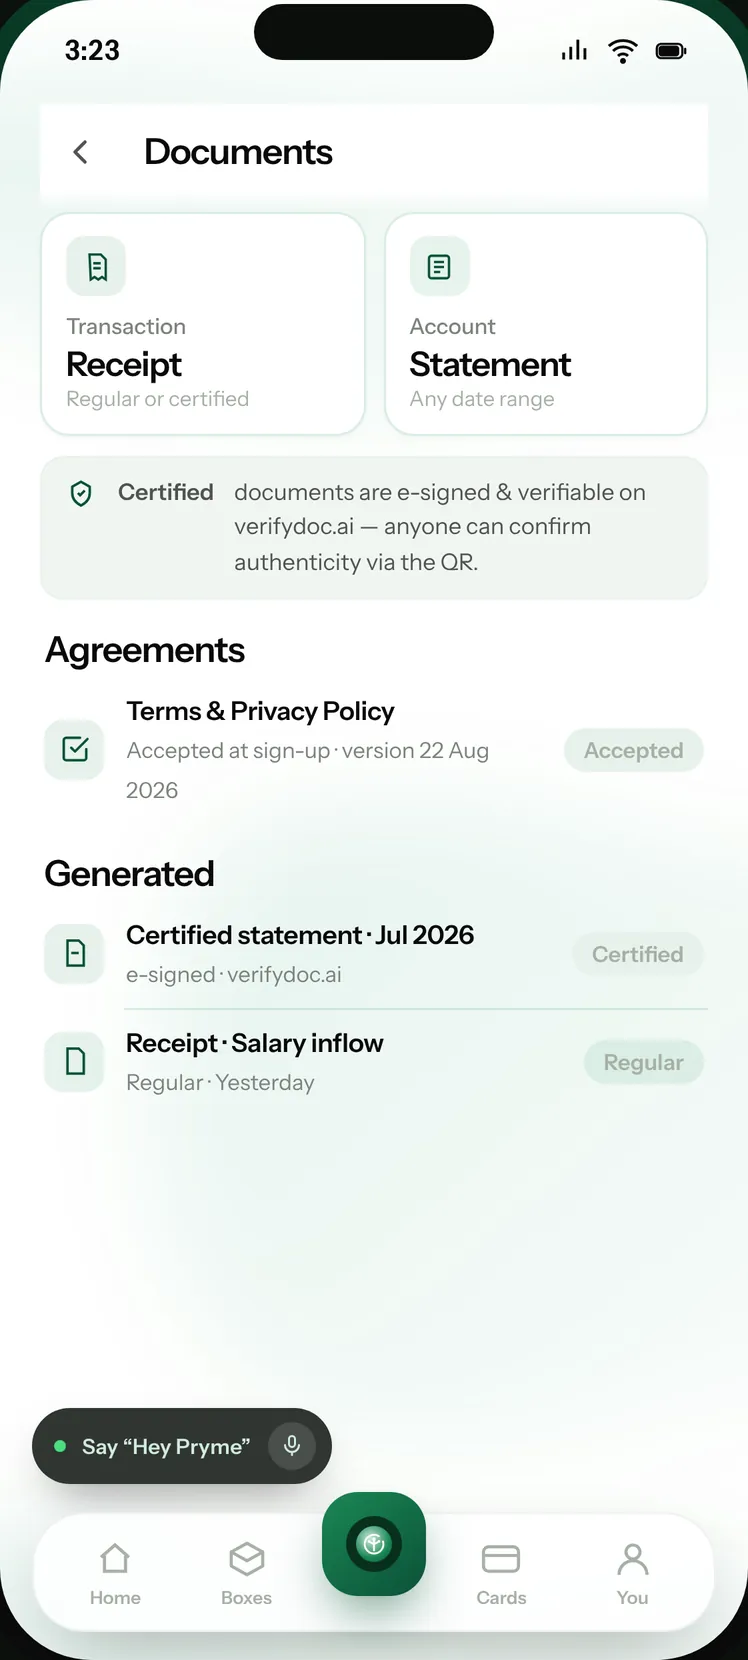
We give you a limit to spend at the shops and services you already use — and an account that works on your month while you get on with it. Dollars, pounds and euros sit beside your Naira, and an assistant handles the running of it, asking you first every single time.
One global account for your money and business. Move across currencies, automate everyday operations and put AI agents to work — with you in control of every important decision.
 Evayour assistant
 DanielChief of Staff
 BenFinance
 BruceCare
Your competitor down the road sells the same thing you sell. The difference is who walks in. We put money in people’s hands that can only be spent in businesses like yours — and then we point them at you.
You are not borrowing. You are selling to somebody who already has the money — and that money can only be spent with a business like yours.
₦100,000 from day one · agreement v2.1 · 12 Aug · View
Eva waits for your rate and asks before she moves anything.
No card, no OTP, nothing for the buyer to type in. They transfer from the bank app they already use, and the money lands in the same account your agents are running — already matched to the order, already in your books.
We give the buyer a one-time account number. They transfer to it from any bank app or by USSD — no card, no OTP, nothing to type in.
Get the account numberTo this account, from any bank app. We watch it, and the page updates itself.
₦26,767.50 from GTBank · John D., matched to order ORD‑1042.
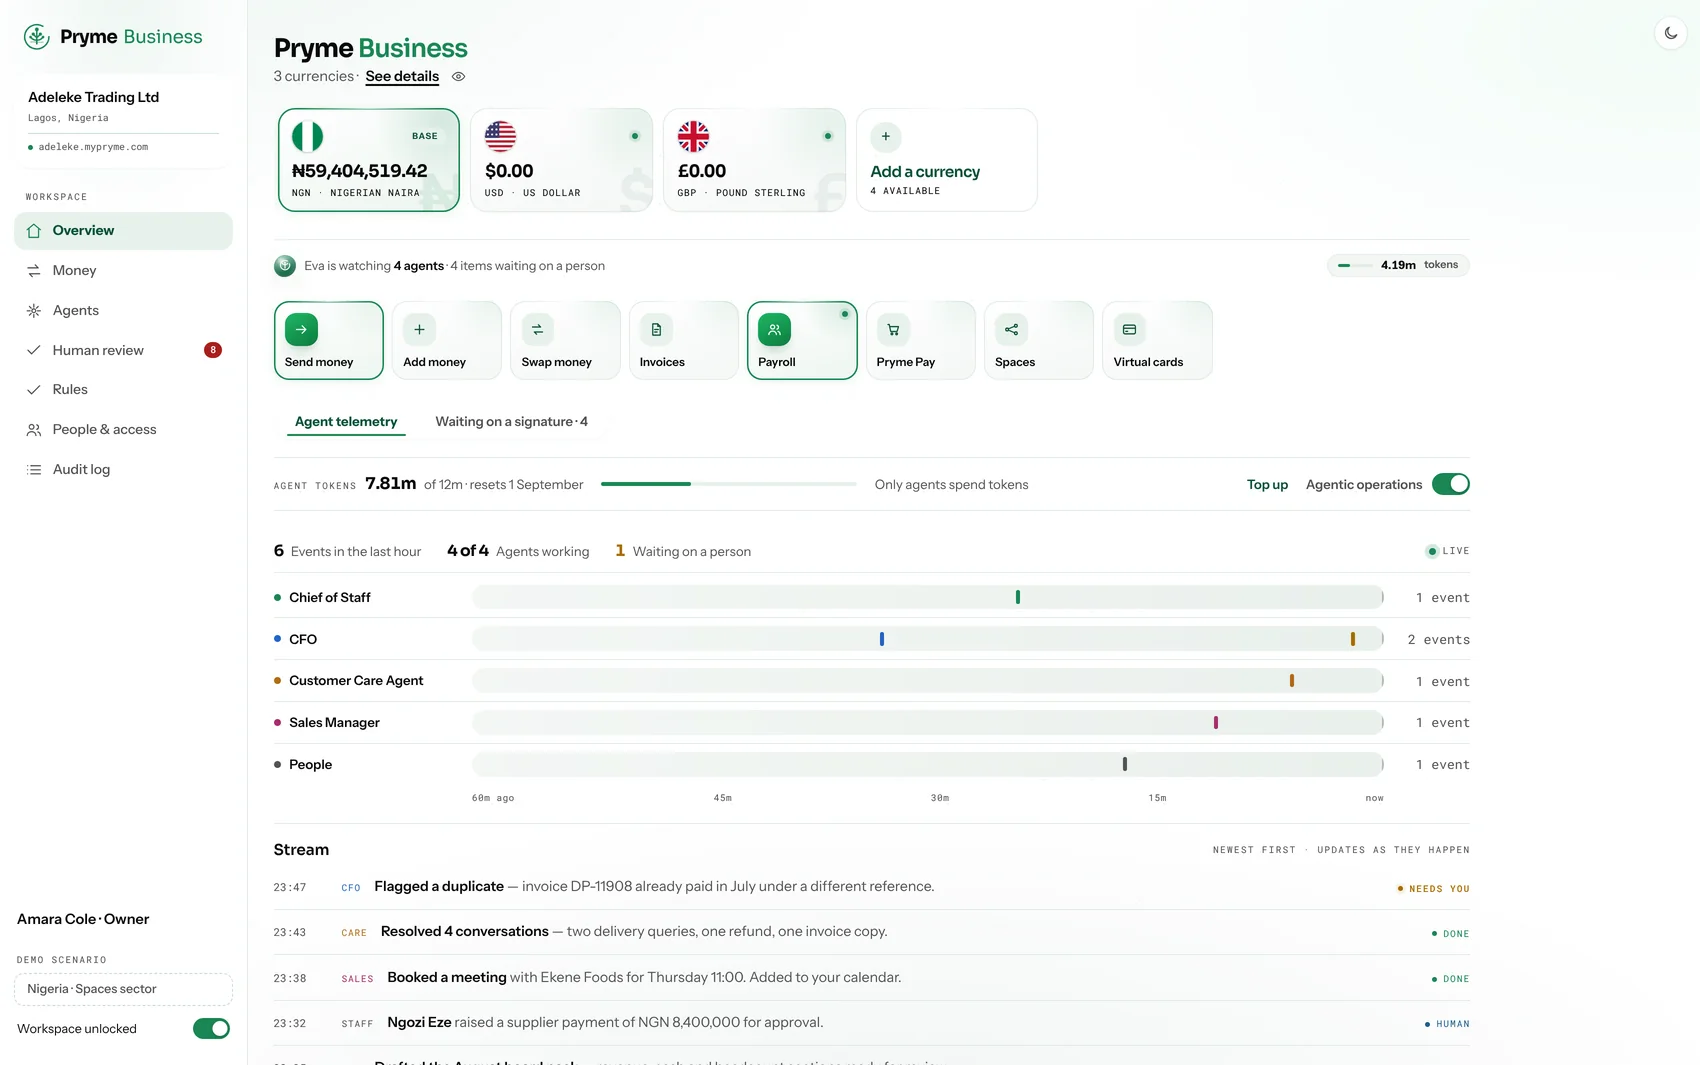
Five agents come with the account. Each one has a job description, a budget and a ceiling you set. They do the work and bring it to you — nothing leaves the account without your signature.
Knows what is stuck, who is waiting and what you promised — and keeps all three moving.
Booked a meeting with John Doe Foods for Thursday 11:00.Keeps the books as you trade and tells you the moment something does not add up.
Flagged a duplicate — invoice DP‑11908 was already paid in July.Holds every filing to its own clock and screens names and payments against your policy — and logs what it refuses.
Screened 412 payments overnight and refused two of them.Goes back to the buyers who went quiet, with the receipt already attached.
Recovered ₦410,000 across three overdue invoices.Replies, follows up on what they asked for and hands you only the ones that need you.
Resolved 4 conversations — two deliveries, one refund.Issue a dedicated Naira account number to each of your own customers, collect into it and reconcile against it. The same rails the Business Account runs on, with the licence behind them.
Dollars, pounds and euros beside a Naira account, on one ledger and one set of books. Five agents come with it and run the account — nothing leaves without your signature.
Five agents come with the account. Each has a job description, a budget and a ceiling you set. They do the work and bring it to you — they propose, you approve.
Knows what is stuck, who is waiting and what you promised, and keeps all three moving.
Booked the quarterly review with your auditor for Thursday.Keeps the books in every currency you hold and flags the moment something does not add up.
Flagged a duplicate — invoice DP‑11908 was already paid in July.Holds every filing to its own clock and screens names and payments against your policy — and logs what it refuses.
Screened 412 payments overnight and refused two of them.Goes back to the buyers who went quiet, with the invoice and the receipt already attached.
Recovered $12,400 across three overdue invoices.Replies, follows up on what they asked for and hands you only the ones that need you.
Resolved 4 conversations — two deliveries, one refund.The business has changed shape four times and never changed what it was rooted in. Each version was built out of what the last one could not do.
An online grocery store, built out of a faulty tab. Selling the food was the easy part — taking the money for it, and moving it, turned out to be the business.
A prepaid card. The first time the company issued rather than resold, and the first time it carried the obligations that come with holding somebody else’s money.
Solid Allianze acquired — an existing bank with an existing licence. The perimeter stopped being someone else’s to draw.
More than one currency on one balance, and the rebrand to Pryme. A Nigerian business could hold dollars without holding a second institution.
Accounts that do the work rather than only hold value. Five agents on the account, inside a policy you write — which is where the new mark starts.
Pryme is a financial technology company. It gives people and businesses in Nigeria one account that holds Naira alongside dollars, pounds and euros, and a set of agents that do the running of it — keeping the books, chasing what is owed, answering customers and paying bills. Nothing leaves an account without the owner’s approval.
Yes. A Pryme account holds Naira, US dollars, pounds sterling and euros side by side on one ledger, each with its own account details — a Nigerian account number, a US account number, a UK sort code and an IBAN for the euro area. You can swap between them at a rate you set, and every currency has its own statement.
Spaces is available in Nigeria. It gives a shopper money to spend that can only be spent with a participating business. The business is paid into its Naira account whether or not the shopper repays, because Pryme carries the credit. For the business it is free to join, there is nothing monthly, and the customer’s identity is never shown — only a reference and what it is worth.
Five agents come with the account. The Chief of Staff runs the week and keeps what is stuck moving. Finance watches the money and keeps the books as you trade. Compliance keeps the filings on time and screens what moves. Sales chases what you are owed. Customer Support answers your customers and follows up. Each has a job description, a budget and a ceiling you set, and each one proposes rather than acts — nothing leaves the account without your signature.
Pryme Pay takes payments on your own site or on a checkout page you control. The buyer is given a one-time account number and transfers to it from any bank app or by USSD — no card, no OTP, nothing to type in. The money lands in the same account your agents are running, already matched to the order and already in your books.
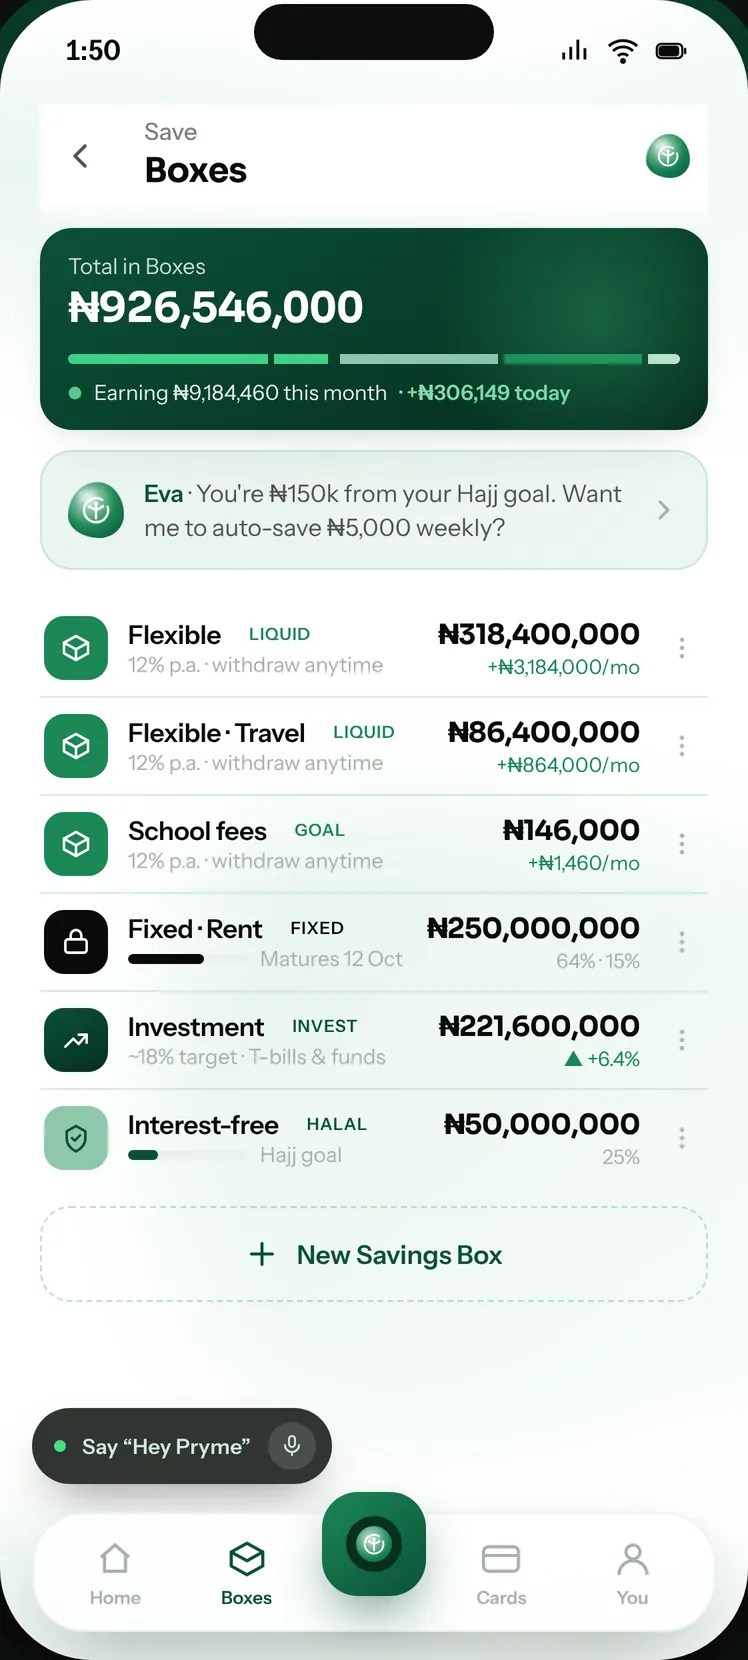
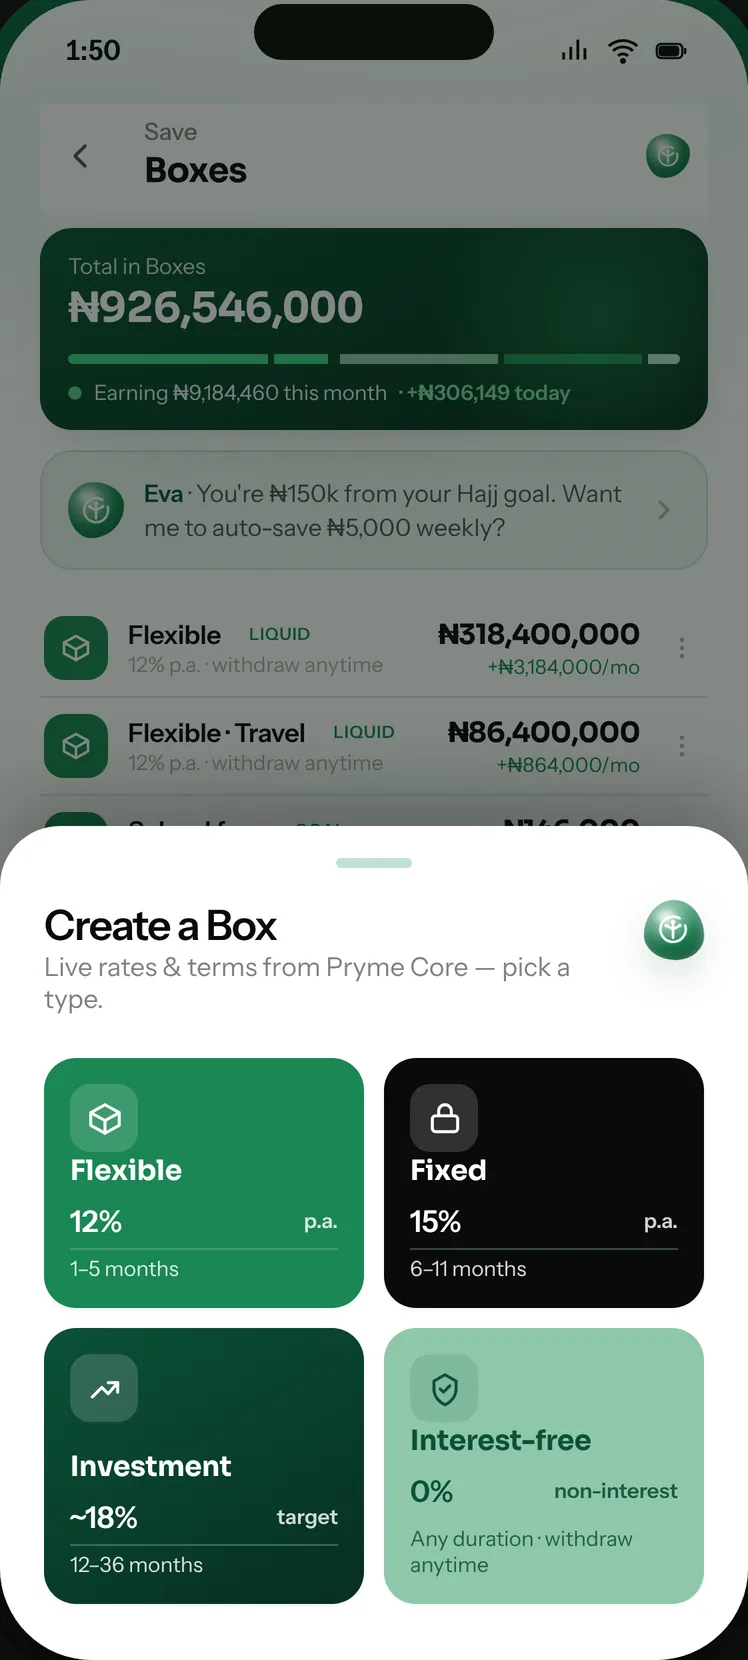
Savings Boxes are separate pots inside a Pryme account, held in Naira. Flexible Boxes can be withdrawn at any time, Fixed Boxes hold to a date, Investment Boxes hold for longer, and Interest-free Boxes earn nothing by design. A business can use them to ring-fence payroll and the tax it withholds, so that money cannot be spent by accident.
Pryme is a financial technology company, not a bank. Accounts and deposits are provided by Solid Allianze Microfinance Bank Limited, which is licensed by the Central Bank of Nigeria and is a member of the Nigeria Deposit Insurance Corporation.
Yes. Pryme Rails lets a platform issue a dedicated Naira account number to each of its own customers, collect into it and reconcile against it, over one API — the same rails the Pryme Business Account runs on.
Pryme is a financial technology company. It gives you one account that holds US dollars, pounds sterling and euros beside Naira, with an assistant that runs the account for you and asks before anything moves. Accounts are provided in Nigeria today, and further markets open as each licence lands.
Accounts are provided in Nigeria today, subject to verification and approval. Foreign-currency balances are held and converted inside that account, so you can hold, receive and swap dollars, pounds and euros wherever you are.
Naira, US dollars, pounds sterling and euros, side by side on one ledger. Each has its own details — a Nigerian account number, a US account number, a UK sort code and an IBAN for the euro area — and each has its own statement.
Swap at a rate you set rather than the rate of the day, then send to any Pryme username or to a Nigerian bank account. There is no fee to send to another Pryme account.
Eva is the assistant inside the Pryme app. She opens accounts, moves money, saves toward your goals, pays what is due and follows up what is owed to you — and asks you before anything moves.
Pryme Rails lets a platform issue a dedicated Naira account number to each of its own customers, collect into it and reconcile against it, over one API — the same rails the Pryme Business Account runs on.
Notes on money that does the work: what we are building, what the regulation actually says, and how we think about letting software act on money. Read the Ledger
What AI agents can do in bookkeeping, close, collections and compliance today, where a person must stay in charge, and how to judge a product.
How multi-currency business accounts work: local details vs SWIFT, payment rails, the real cost of FX, safeguarding vs deposit protection, and hedging.
How UK, US, Canadian and European firms pay Nigerian suppliers and get paid by Nigerian clients: FX, Form A and M, tax, compliance and payout routes.
What it really costs to send money to Nigeria from the UK, US, Canada and Europe: fees, exchange-rate margins, CBN naira rules, BVN, speed and scams.
What AI can and cannot do in day-to-day bookkeeping, how much time it saves on real numbers, and which jobs must stay with you or your accountant.
How an AI agent can chase overdue invoices for a UK small business, calculate statutory interest and compensation, and when a person must step in.
An AI agent can send polite, well-timed reminders, log every contact, and work out the statutory interest and fixed compensation the Late Payment of Commercial Debts (Interest) Act 1998 allows on business-to-business debts. What it should not do alone is charge interest to a valued client, threaten legal action or start a claim; those decisions affect relationships and need a person.
When one business pays another late in the UK, the Late Payment of Commercial Debts (Interest) Act 1998 gives the supplier a right to statutory interest and fixed compensation, unless the contract sets out a substantial alternative remedy. It applies to business-to-business sales, not to sales to consumers. If no payment date was agreed, the law treats payment as due 30 days after the customer received the invoice or the goods or services, whichever is later.
| What you can claim | Amount |
|---|---|
| Statutory interest | 8% a year above the Bank of England reference rate |
| Fixed compensation, debt under £1,000 | £40 |
| Fixed compensation, £1,000 to £9,999.99 | £70 |
| Fixed compensation, £10,000 or more | £100 |
| Reasonable recovery costs | Can be claimed where they exceed the fixed sum |
The reference rate is the Bank of England base rate on 31 December for debts that became overdue in January to June, and on 30 June for July to December. The government has also introduced the Small Business Protections Bill, which would limit payment terms and give the Small Business Commissioner new powers. At the time of writing it was still before Parliament and not law, so check the current position before relying on it.
Most late payments in small firms are not disputes. The invoice went to the wrong inbox, the purchase order number was missing, the client's payment run happens monthly, or nobody followed up. Chasing is dull, awkward and easy to postpone, which is why it suits an agent.
Prevention helps as much as chasing. An agent can check new clients before work starts, confirm who approves invoices on their side, and make sure your payment terms and the right to statutory interest are stated on every invoice. Clear terms at the start make the later conversation easier.
The agent's job at step four is to give you the facts in one place, not to escalate on its own. Many owners choose not to charge interest to a long-standing client who pays reliably but slowly; others add it routinely. Both are business decisions.
This is an illustrative example using an assumed reference rate of 4%. A small IT support firm in Manchester invoiced a client £4,800 on 30-day terms. Payment arrives 45 days after the due date. Statutory interest is 12% a year (8% plus 4%), so the daily interest is £4,800 × 12% ÷ 365, about £1.58, and 45 days comes to about £71. Because the debt is between £1,000 and £9,999.99, fixed compensation is £70. The firm could claim about £141 on top of the invoice.
The agent works this out and shows it to the owner alongside the client's payment record over the past year. The owner decides to waive it this time but tells the client future late payments will attract interest. The agent records the decision and the message.
If a larger business repeatedly pays you late, the Office of the Small Business Commissioner can look into complaints from small suppliers. An agent can assemble the evidence pack; you decide whether to file it.
The Pryme Sales agent holds receivables alongside the pipeline and drafts follow-ups that cite the thread they came from, while the Finance agent matches payments as they land so chasing stops the moment a client pays. Pryme invoicing issues the invoice from the same account in GBP, USD, EUR or NGN. Anything beyond the cadence you set comes to you. For more on the process, read AI for accounts receivable and Cash flow forecasting with an AI agent.
For business-to-business debts, usually yes: the 1998 Act allows statutory interest at 8% above the Bank of England reference rate, unless your contract has a substantial alternative remedy.
The 1998 Act does not apply to consumers. Any charge must be in your agreed terms and be fair under consumer law. Take advice.
They can if they are badly timed or rude. Set the tone and cadence yourself, stop reminders when a client replies, and let the agent escalate to you rather than keep sending.
Not yet. The Small Business Protections Bill, which would cap payment terms and strengthen the Small Business Commissioner, was still before Parliament at the time of writing. Check GOV.UK for the current position.
This article is general information, not financial, legal or tax advice. Products described are provided under the terms on this site and are subject to regulation and eligibility.
How an AI agent builds a 13-week cash flow forecast for a UK small business, including VAT, PAYE and Corporation Tax dates, and what to check yourself.
The legal steps for a UK firm hiring its first employee, from right to work checks to pensions, and which ones an AI agent can track for you.
How a UK employer can use an AI agent to check pay against the 2026 minimum wage rates each pay period, and the calls a person must still make.
You can add the other type later — many of our customers hold both.
The business first, then you. Nothing is submitted until you review it.
Ideal customer profiles
Generated from your website by VerifiedLead.ai
Pick the ones that look right. Your Sales agent works these first, and you can change them at any time after opening.
We ask this because you have not given us a website. It helps us set the right limits from day one.
Which of these represents you?
Officers listed against this company on the UK register.
We have sent a six-digit code to your email address. Enter it below to confirm the address is yours.
Wrong address? Go back and change it — nothing is created until this step passes. We never ask for a code by phone or email; anyone who does is not us.
Last step. Each time you sign in we email you a six-digit code — we never send codes by SMS.