AI agents for business finance: what they can and can't do
What AI agents can do in bookkeeping, close, collections and compliance today, where a person must stay in charge, and how to judge a product.
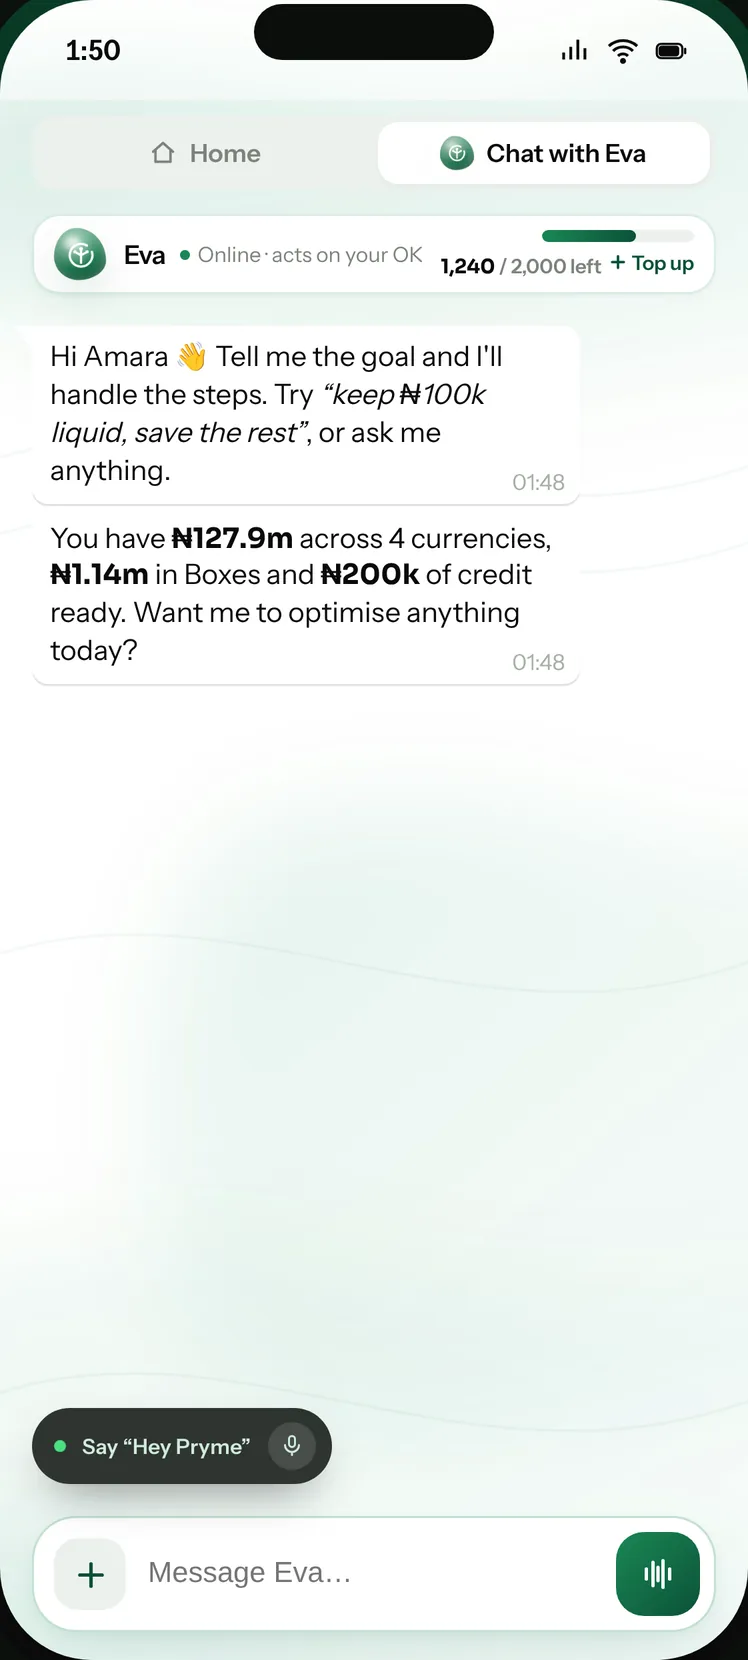
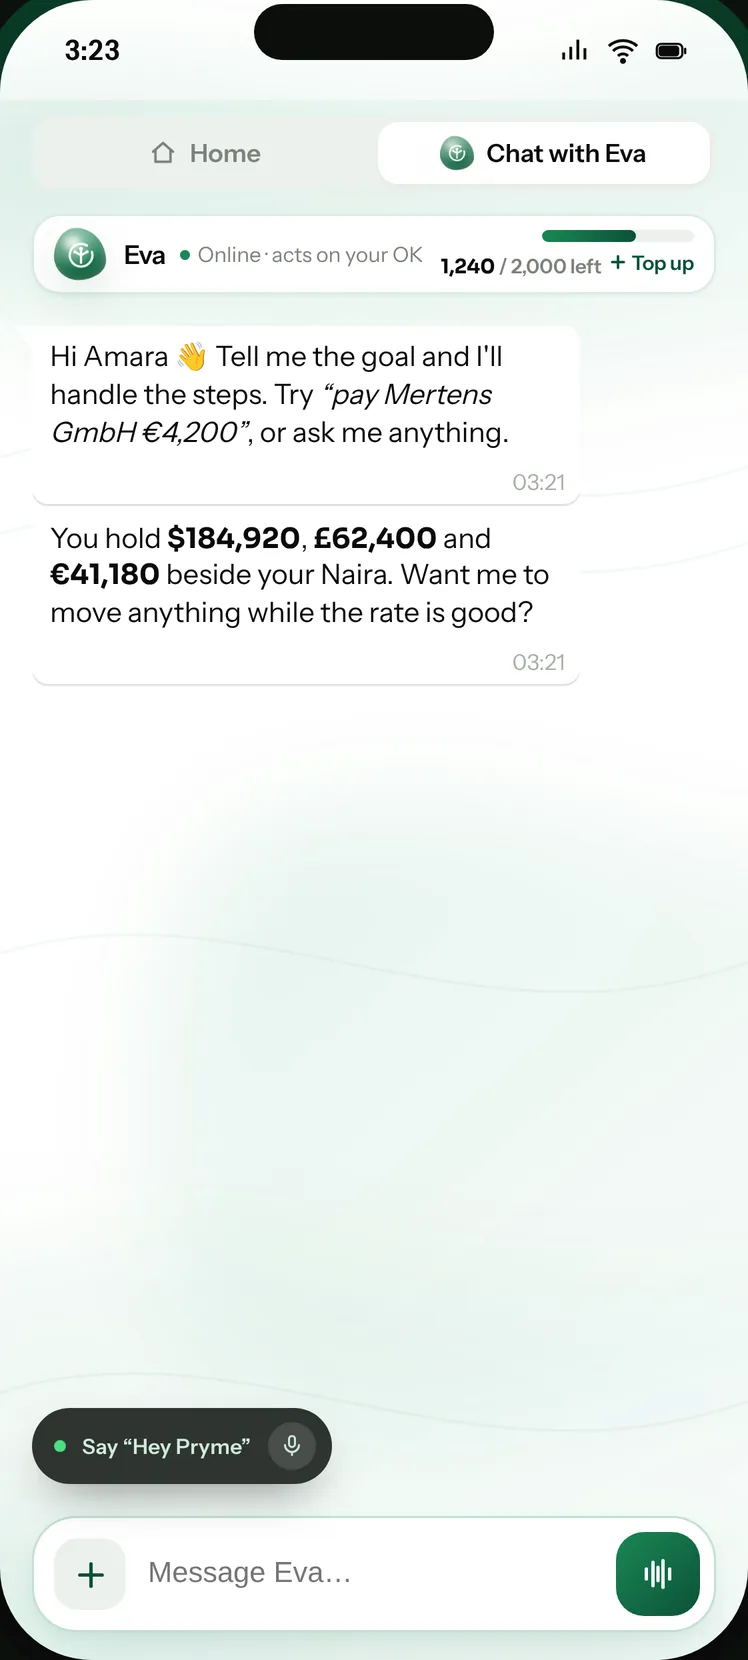
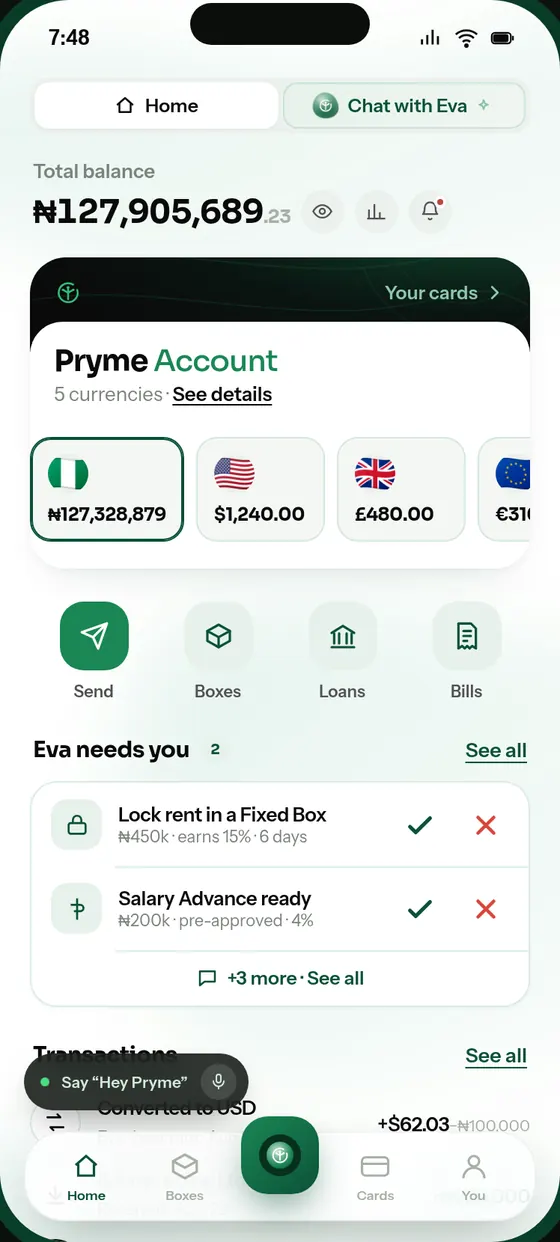
Meet Eva, the assistant inside the Pryme app. She opens accounts, moves money, saves toward your goals and follows up. Nothing leaves your account without your approval.
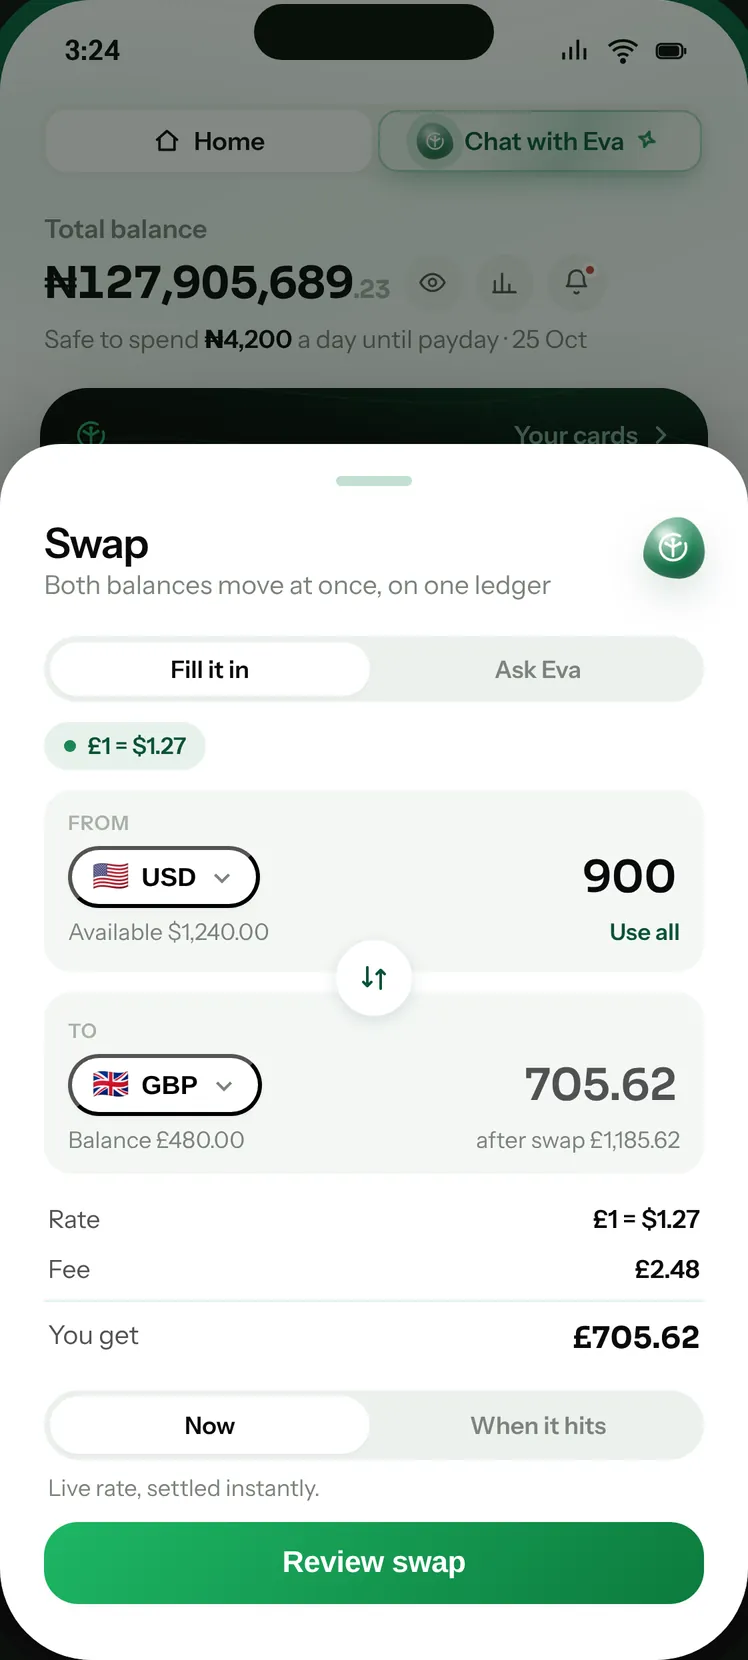
Meet Eva, the assistant inside the Pryme app. She holds dollars, pounds, euros and Naira side by side, swaps at a locked rate, pays bills in any of them and sends anywhere, asking before anything moves.
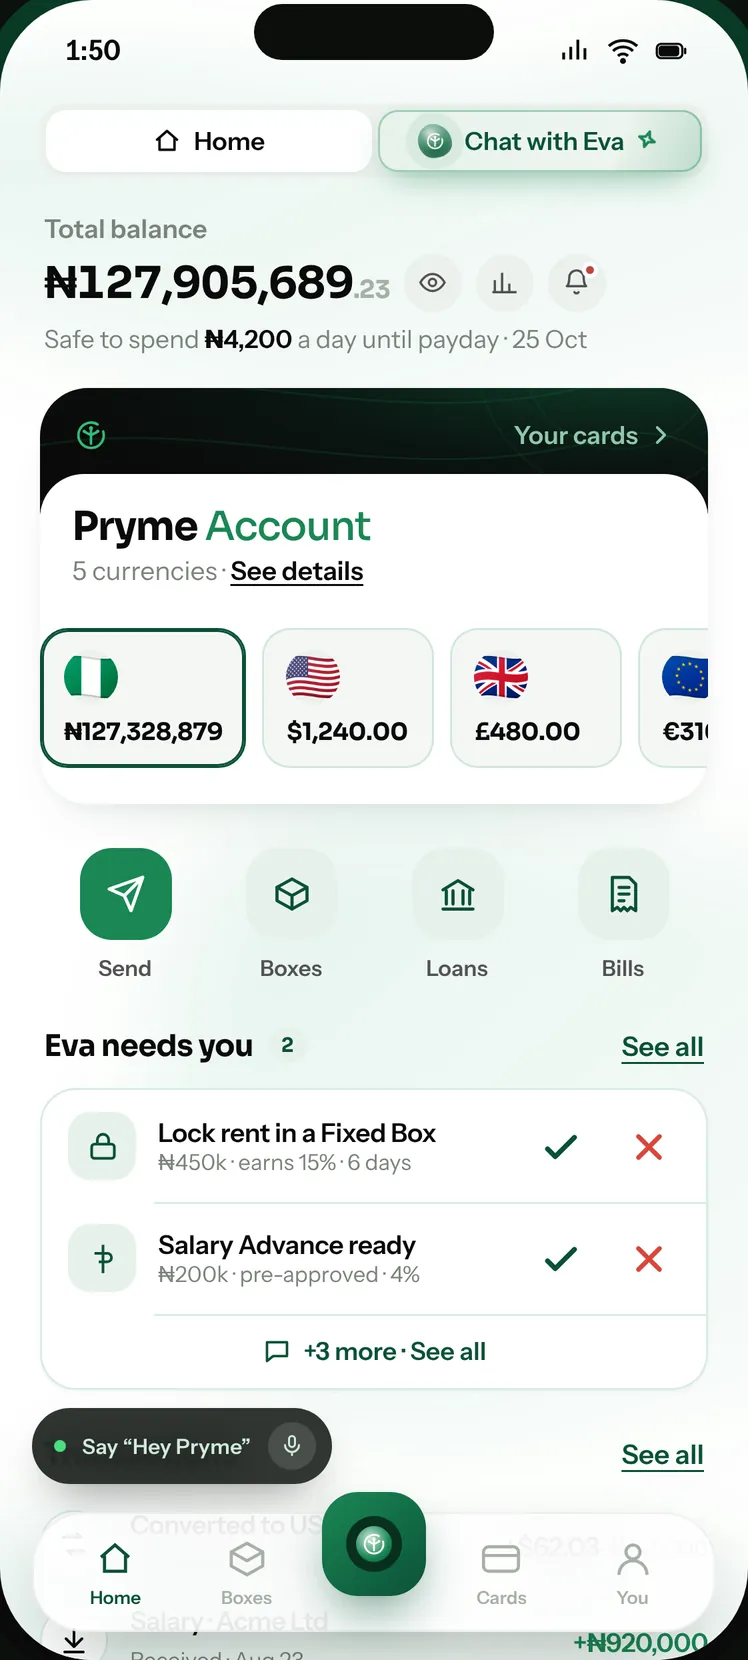
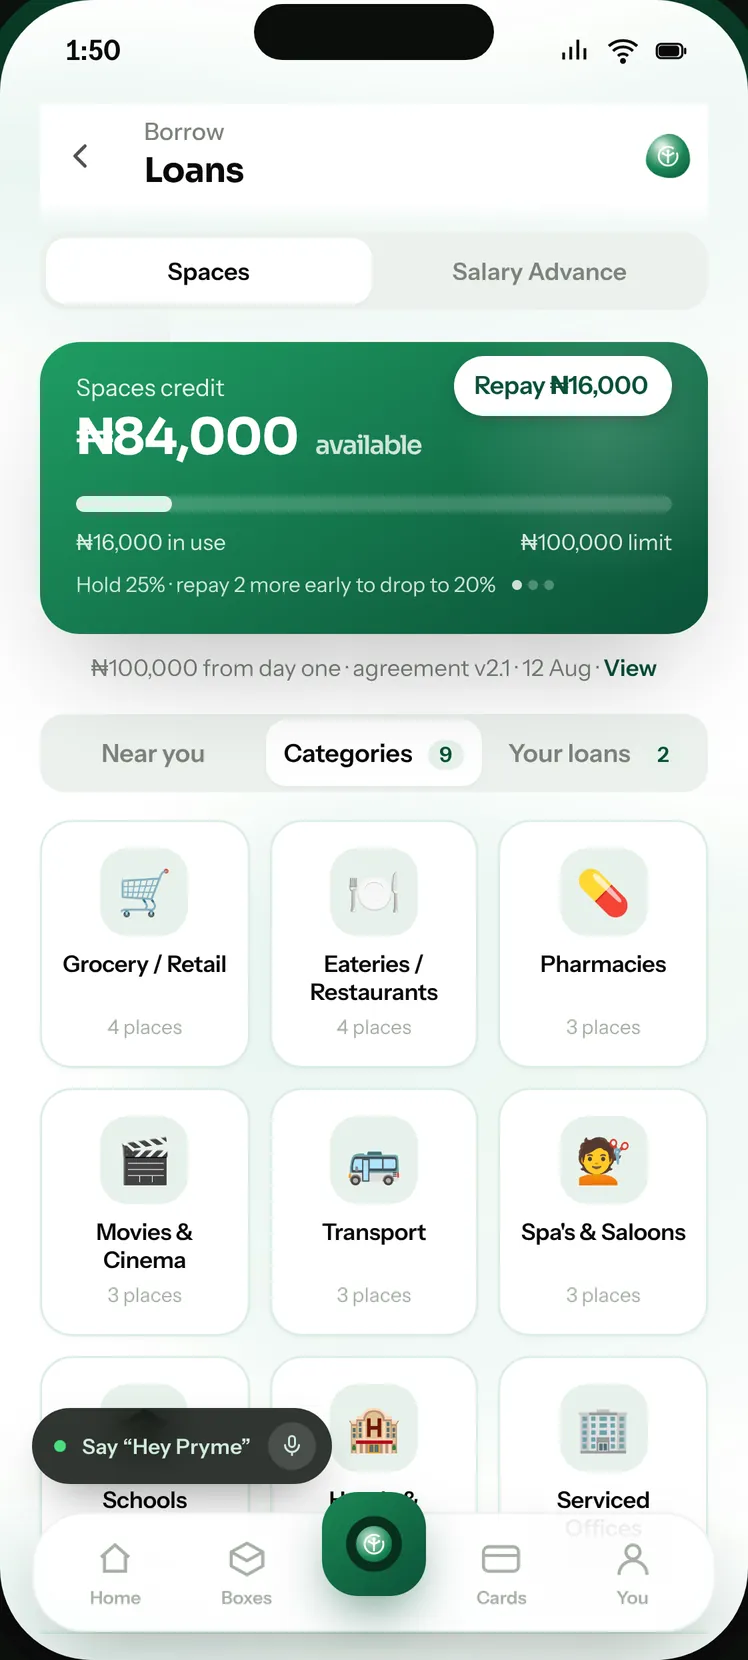
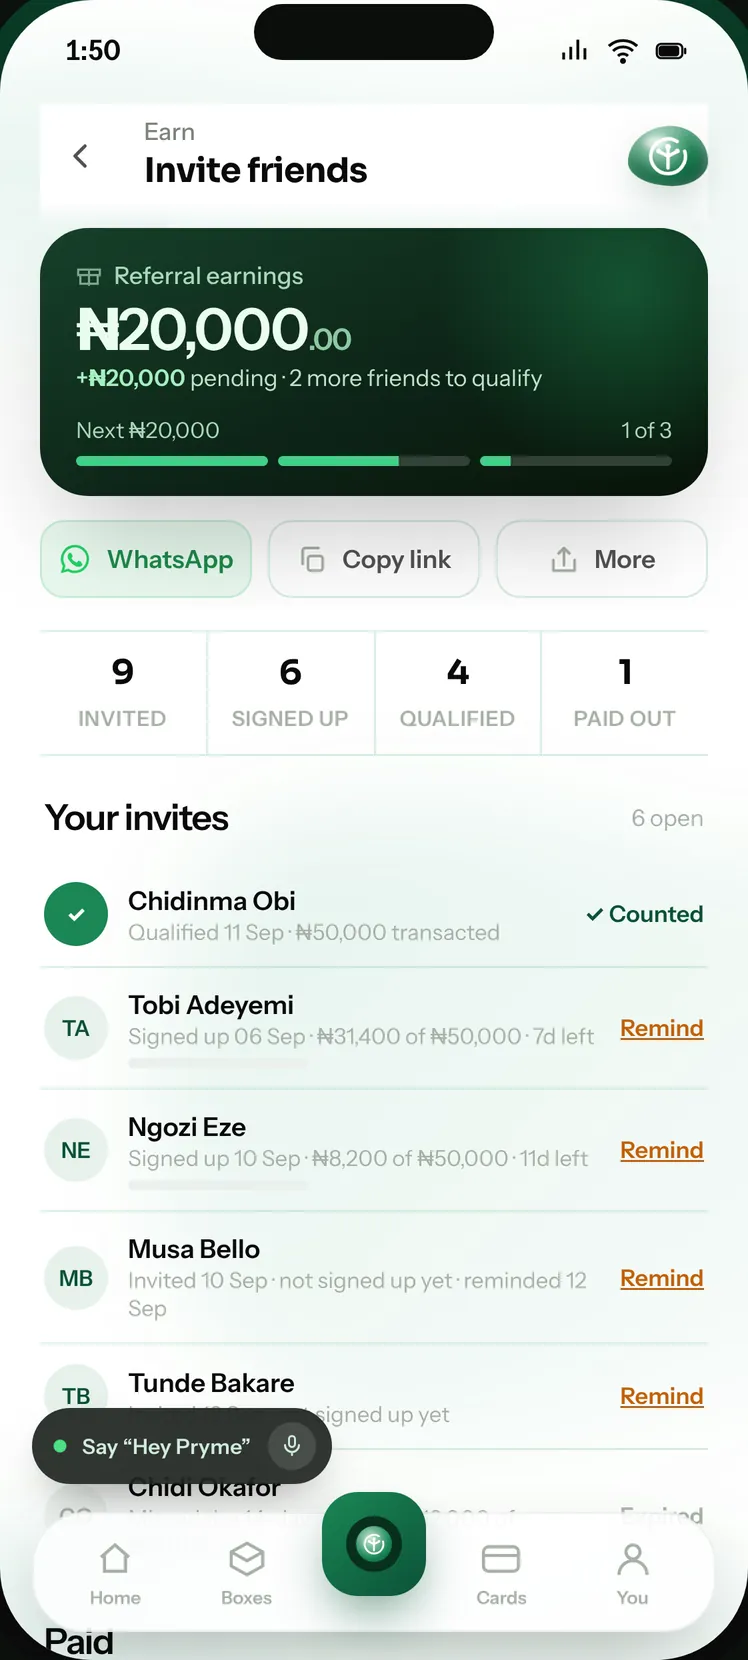
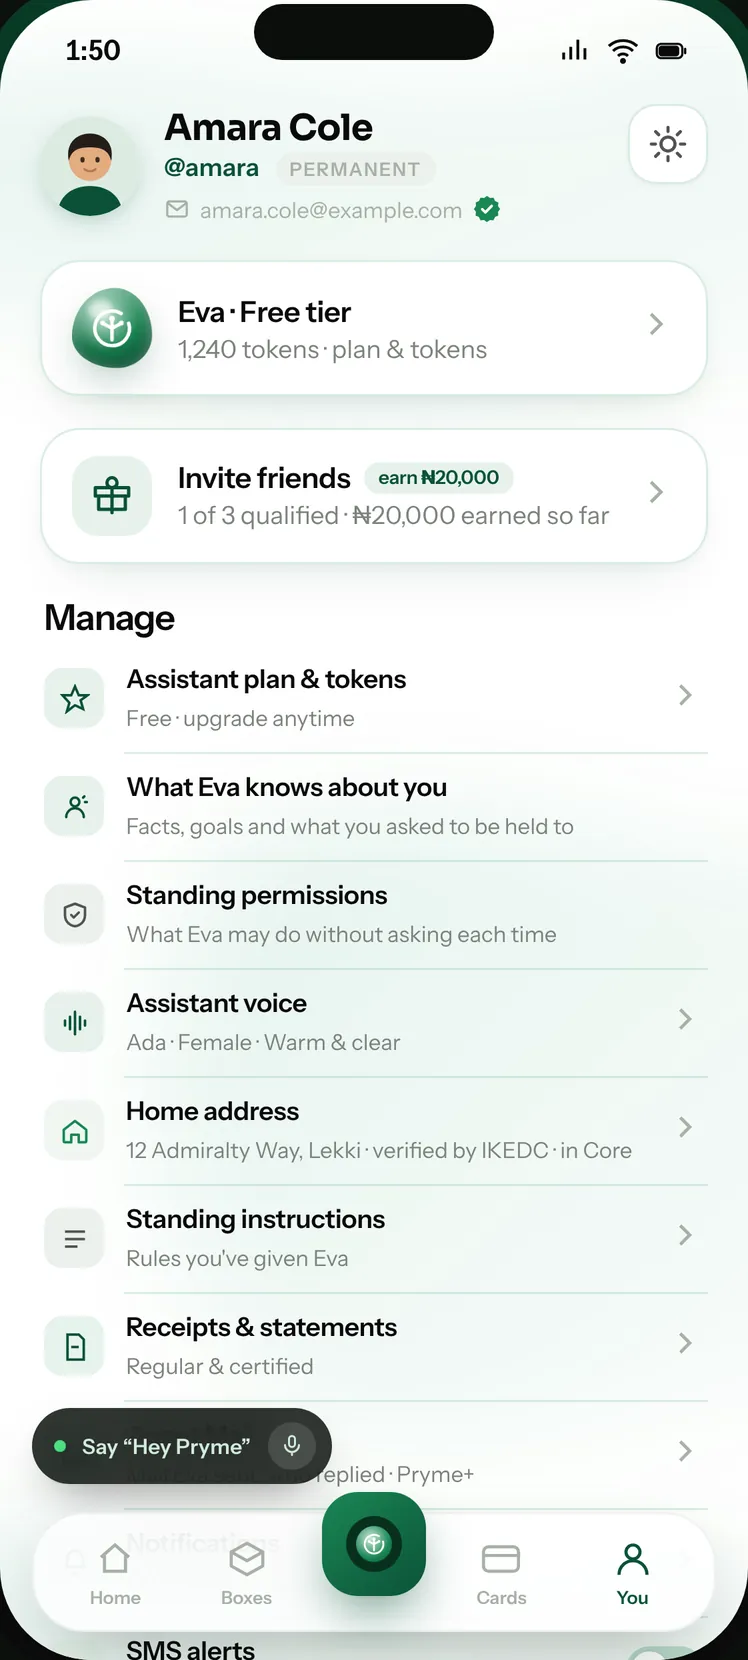
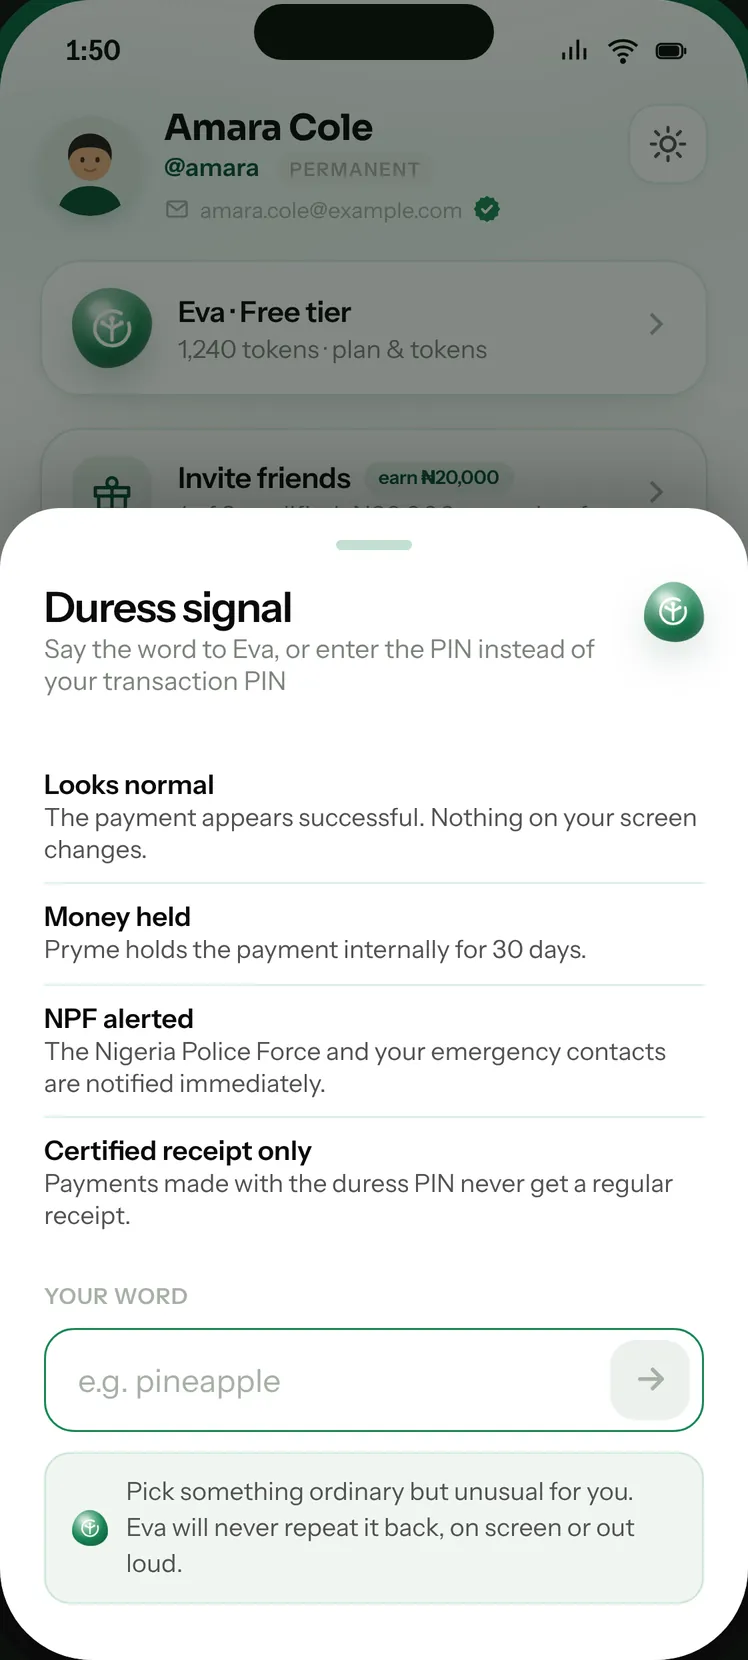
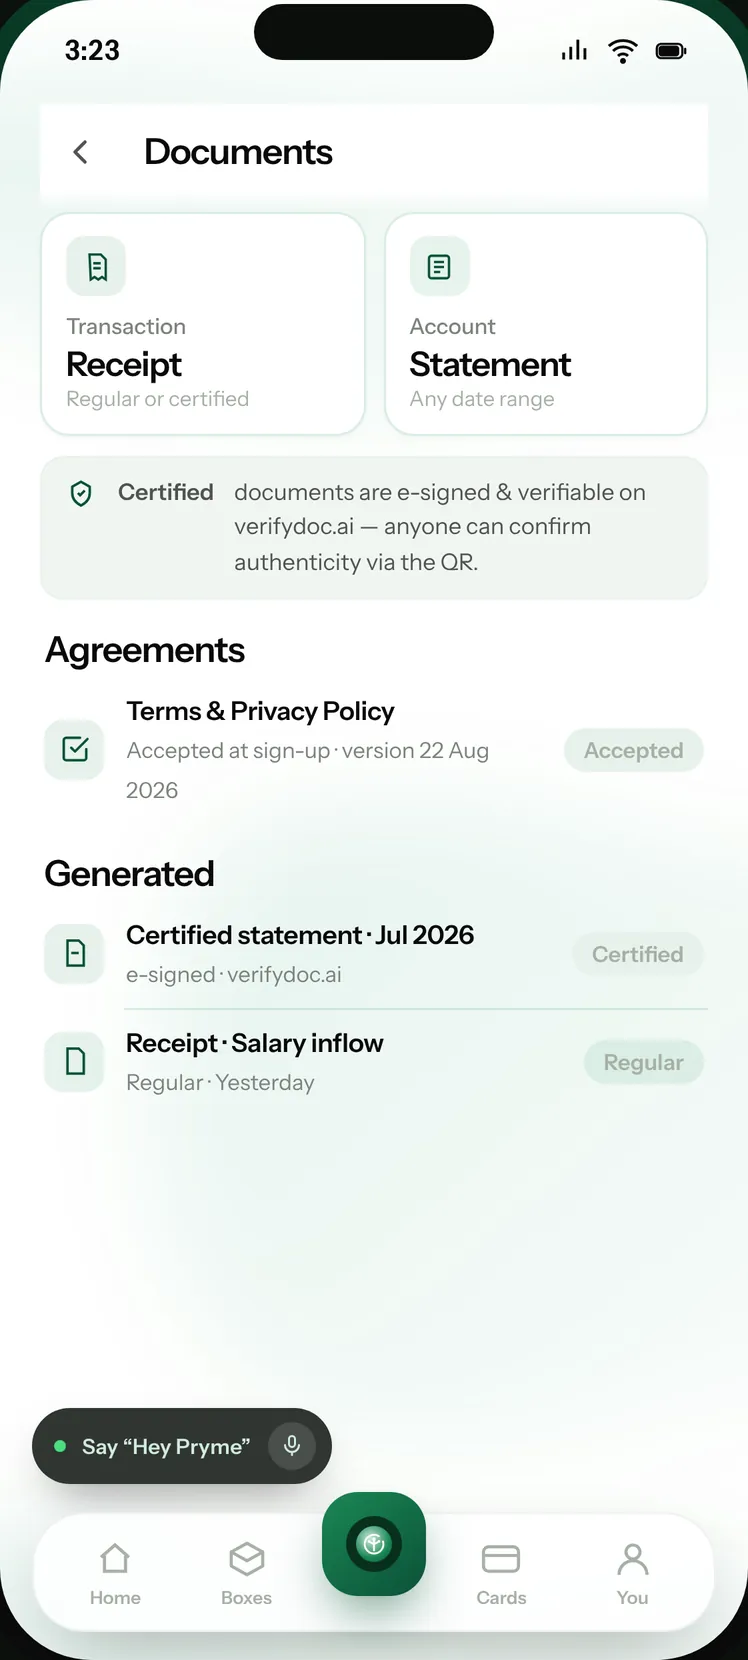
We give you a limit to spend at the shops and services you already use — and an account that works on your month while you get on with it. Dollars, pounds and euros sit beside your Naira, and an assistant handles the running of it, asking you first every single time.
One global account for your money and business. Move across currencies, automate everyday operations and put AI agents to work — with you in control of every important decision.
 Evayour assistant
 DanielChief of Staff
 BenFinance
 BruceCare
Your competitor down the road sells the same thing you sell. The difference is who walks in. We put money in people’s hands that can only be spent in businesses like yours — and then we point them at you.
You are not borrowing. You are selling to somebody who already has the money — and that money can only be spent with a business like yours.
₦100,000 from day one · agreement v2.1 · 12 Aug · View
Eva waits for your rate and asks before she moves anything.
No card, no OTP, nothing for the buyer to type in. They transfer from the bank app they already use, and the money lands in the same account your agents are running — already matched to the order, already in your books.
We give the buyer a one-time account number. They transfer to it from any bank app or by USSD — no card, no OTP, nothing to type in.
Get the account numberTo this account, from any bank app. We watch it, and the page updates itself.
₦26,767.50 from GTBank · John D., matched to order ORD‑1042.
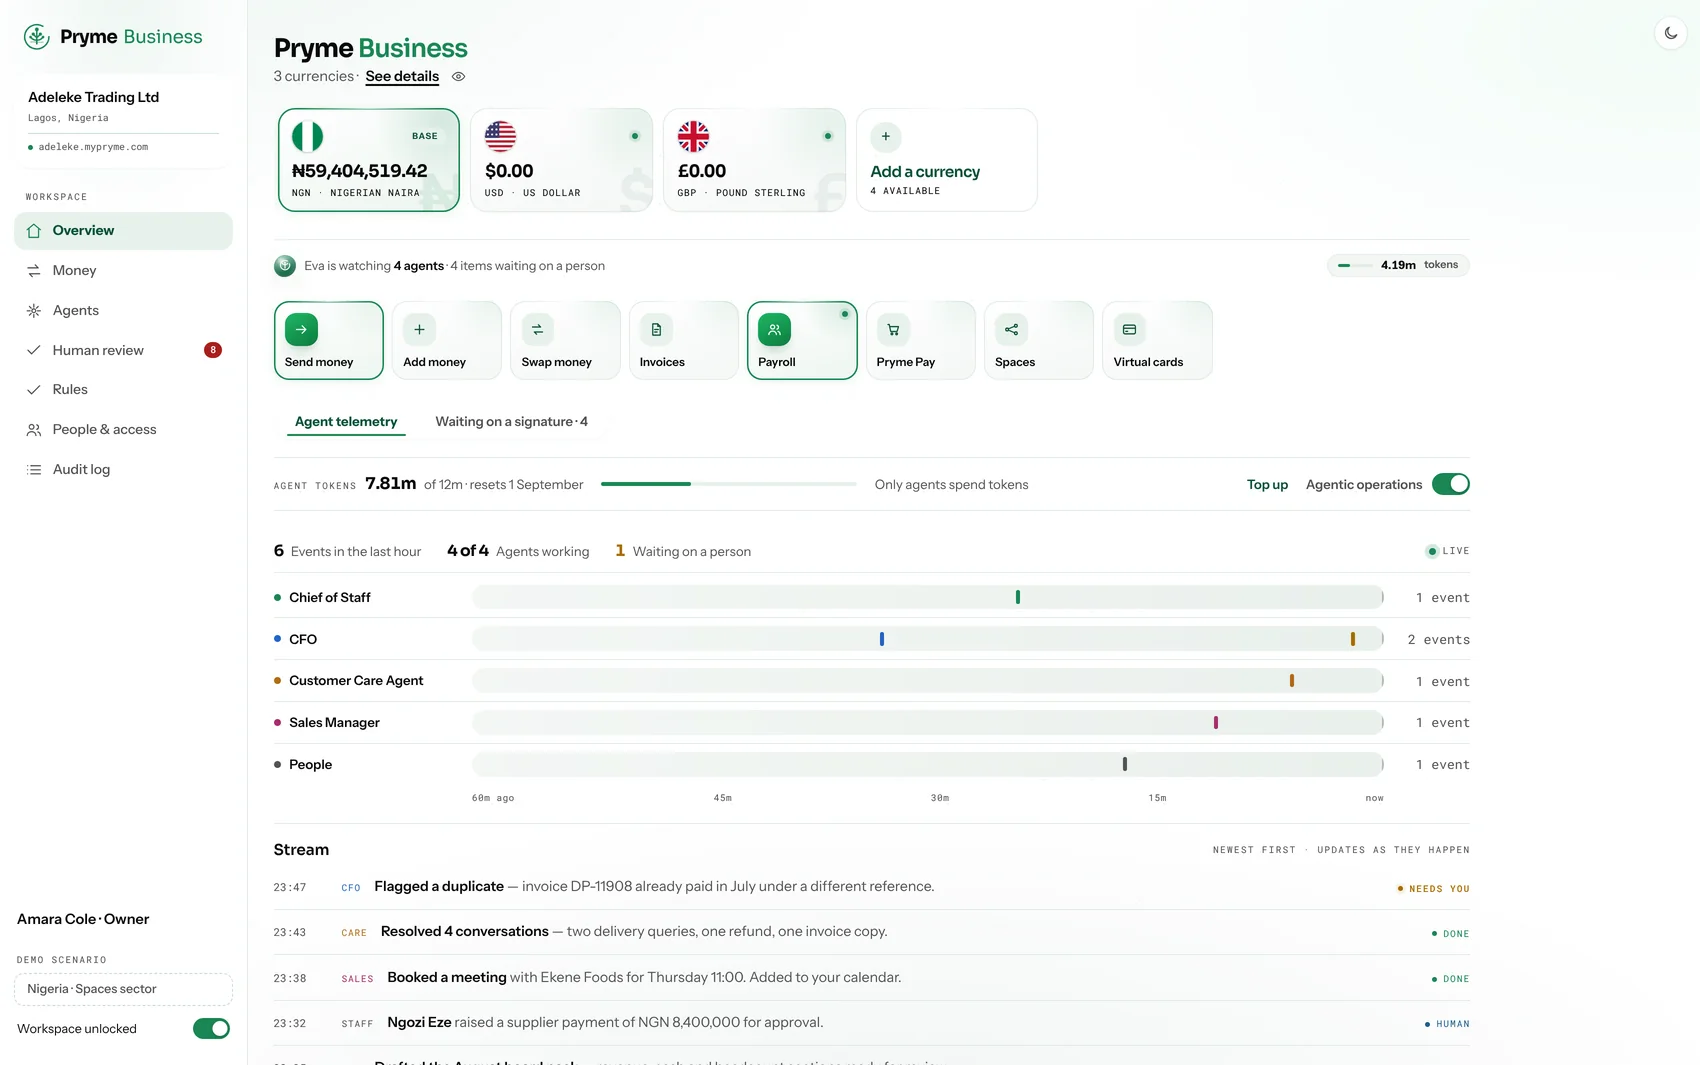
Five agents come with the account. Each one has a job description, a budget and a ceiling you set. They do the work and bring it to you — nothing leaves the account without your signature.
Knows what is stuck, who is waiting and what you promised — and keeps all three moving.
Booked a meeting with John Doe Foods for Thursday 11:00.Keeps the books as you trade and tells you the moment something does not add up.
Flagged a duplicate — invoice DP‑11908 was already paid in July.Holds every filing to its own clock and screens names and payments against your policy — and logs what it refuses.
Screened 412 payments overnight and refused two of them.Goes back to the buyers who went quiet, with the receipt already attached.
Recovered ₦410,000 across three overdue invoices.Replies, follows up on what they asked for and hands you only the ones that need you.
Resolved 4 conversations — two deliveries, one refund.Issue a dedicated Naira account number to each of your own customers, collect into it and reconcile against it. The same rails the Business Account runs on, with the licence behind them.
Dollars, pounds and euros beside a Naira account, on one ledger and one set of books. Five agents come with it and run the account — nothing leaves without your signature.
Five agents come with the account. Each has a job description, a budget and a ceiling you set. They do the work and bring it to you — they propose, you approve.
Knows what is stuck, who is waiting and what you promised, and keeps all three moving.
Booked the quarterly review with your auditor for Thursday.Keeps the books in every currency you hold and flags the moment something does not add up.
Flagged a duplicate — invoice DP‑11908 was already paid in July.Holds every filing to its own clock and screens names and payments against your policy — and logs what it refuses.
Screened 412 payments overnight and refused two of them.Goes back to the buyers who went quiet, with the invoice and the receipt already attached.
Recovered $12,400 across three overdue invoices.Replies, follows up on what they asked for and hands you only the ones that need you.
Resolved 4 conversations — two deliveries, one refund.The business has changed shape four times and never changed what it was rooted in. Each version was built out of what the last one could not do.
An online grocery store, built out of a faulty tab. Selling the food was the easy part — taking the money for it, and moving it, turned out to be the business.
A prepaid card. The first time the company issued rather than resold, and the first time it carried the obligations that come with holding somebody else’s money.
Solid Allianze acquired — an existing bank with an existing licence. The perimeter stopped being someone else’s to draw.
More than one currency on one balance, and the rebrand to Pryme. A Nigerian business could hold dollars without holding a second institution.
Accounts that do the work rather than only hold value. Five agents on the account, inside a policy you write — which is where the new mark starts.
Pryme is a financial technology company. It gives people and businesses in Nigeria one account that holds Naira alongside dollars, pounds and euros, and a set of agents that do the running of it — keeping the books, chasing what is owed, answering customers and paying bills. Nothing leaves an account without the owner’s approval.
Yes. A Pryme account holds Naira, US dollars, pounds sterling and euros side by side on one ledger, each with its own account details — a Nigerian account number, a US account number, a UK sort code and an IBAN for the euro area. You can swap between them at a rate you set, and every currency has its own statement.
Spaces is available in Nigeria. It gives a shopper money to spend that can only be spent with a participating business. The business is paid into its Naira account whether or not the shopper repays, because Pryme carries the credit. For the business it is free to join, there is nothing monthly, and the customer’s identity is never shown — only a reference and what it is worth.
Five agents come with the account. The Chief of Staff runs the week and keeps what is stuck moving. Finance watches the money and keeps the books as you trade. Compliance keeps the filings on time and screens what moves. Sales chases what you are owed. Customer Support answers your customers and follows up. Each has a job description, a budget and a ceiling you set, and each one proposes rather than acts — nothing leaves the account without your signature.
Pryme Pay takes payments on your own site or on a checkout page you control. The buyer is given a one-time account number and transfers to it from any bank app or by USSD — no card, no OTP, nothing to type in. The money lands in the same account your agents are running, already matched to the order and already in your books.
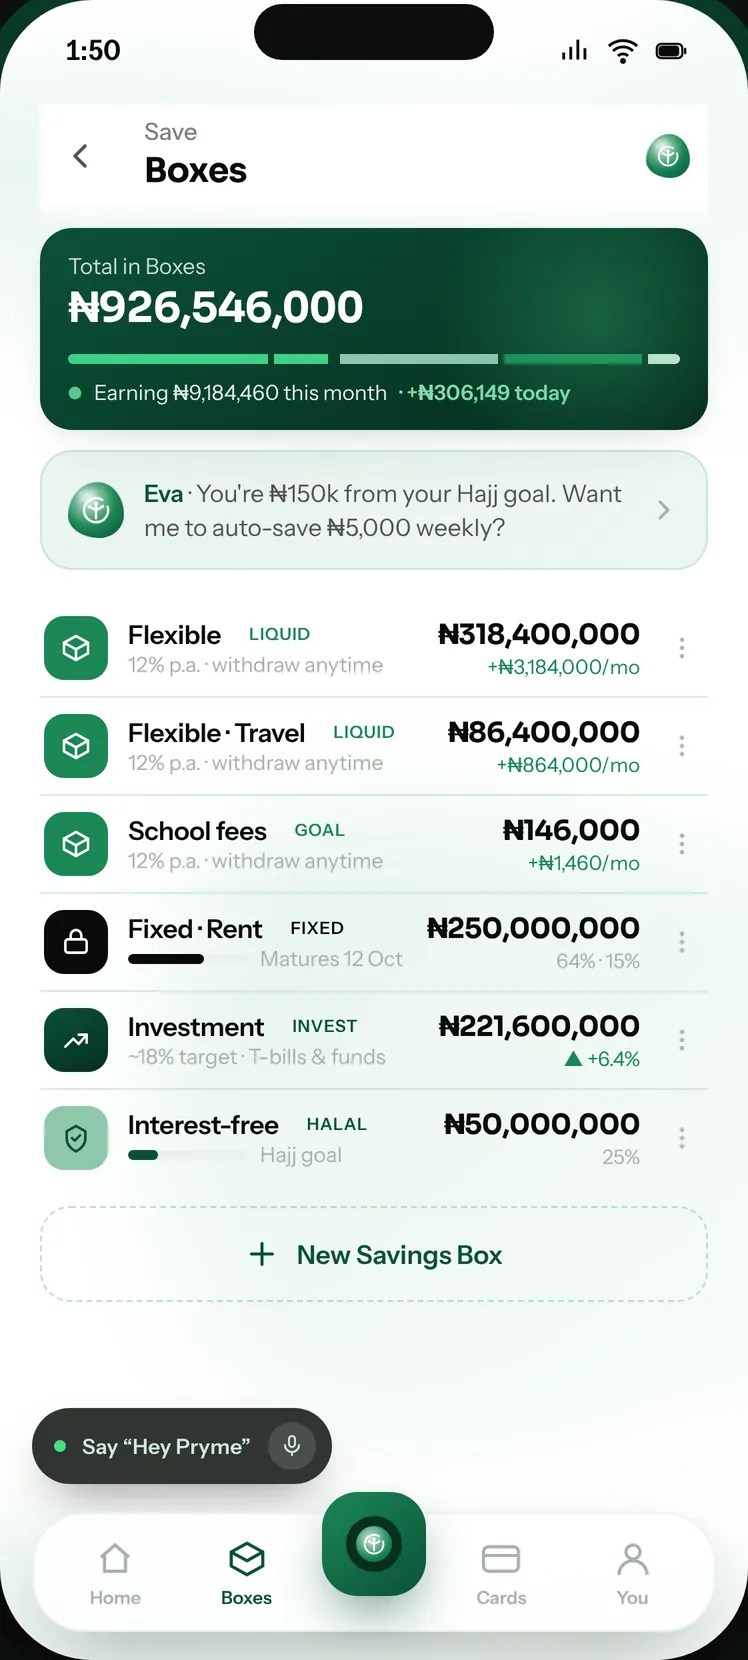
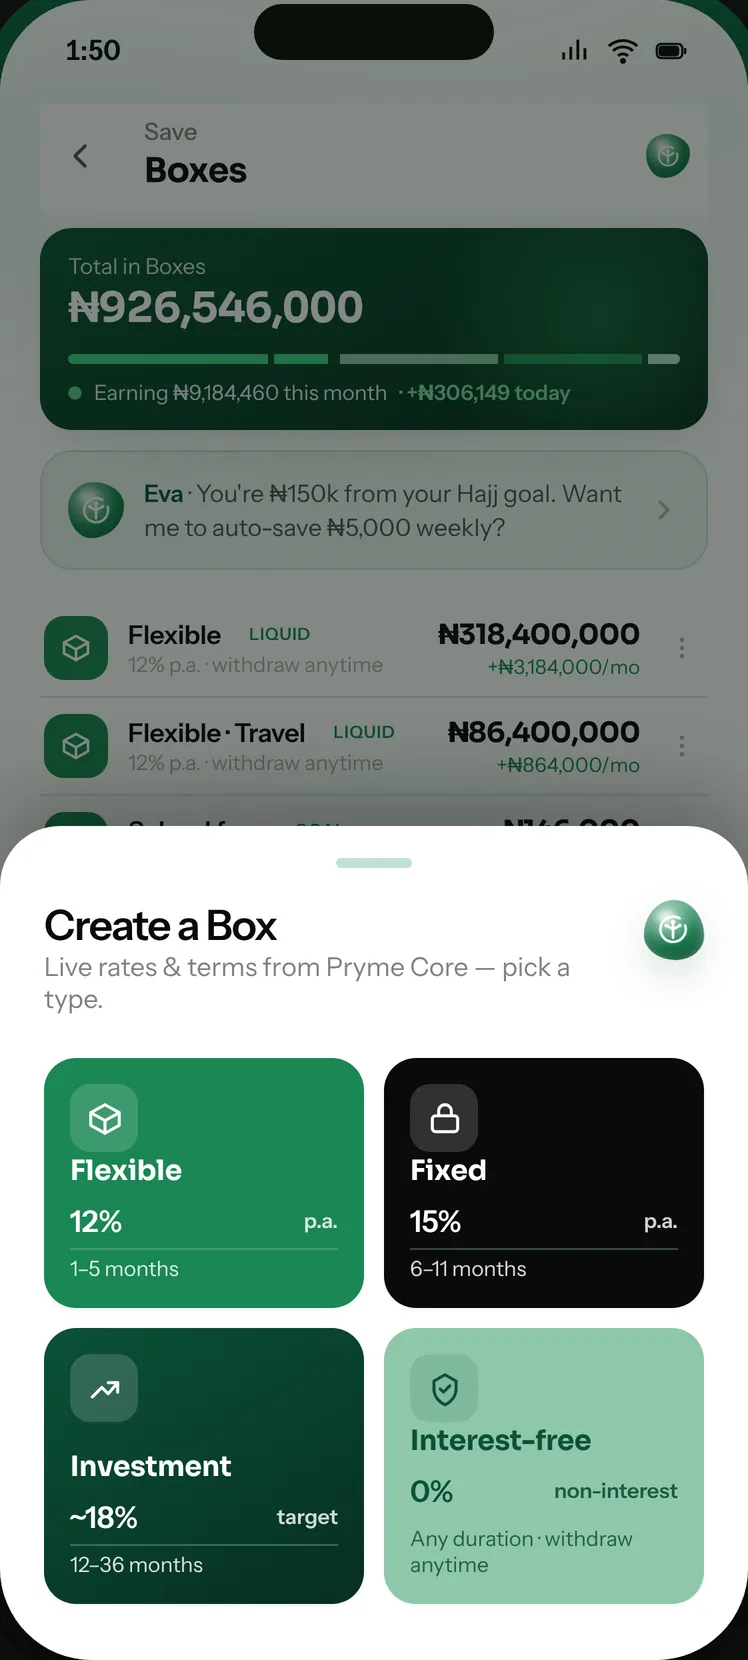
Savings Boxes are separate pots inside a Pryme account, held in Naira. Flexible Boxes can be withdrawn at any time, Fixed Boxes hold to a date, Investment Boxes hold for longer, and Interest-free Boxes earn nothing by design. A business can use them to ring-fence payroll and the tax it withholds, so that money cannot be spent by accident.
Pryme is a financial technology company, not a bank. Accounts and deposits are provided by Solid Allianze Microfinance Bank Limited, which is licensed by the Central Bank of Nigeria and is a member of the Nigeria Deposit Insurance Corporation.
Yes. Pryme Rails lets a platform issue a dedicated Naira account number to each of its own customers, collect into it and reconcile against it, over one API — the same rails the Pryme Business Account runs on.
Pryme is a financial technology company. It gives you one account that holds US dollars, pounds sterling and euros beside Naira, with an assistant that runs the account for you and asks before anything moves. Accounts are provided in Nigeria today, and further markets open as each licence lands.
Accounts are provided in Nigeria today, subject to verification and approval. Foreign-currency balances are held and converted inside that account, so you can hold, receive and swap dollars, pounds and euros wherever you are.
Naira, US dollars, pounds sterling and euros, side by side on one ledger. Each has its own details — a Nigerian account number, a US account number, a UK sort code and an IBAN for the euro area — and each has its own statement.
Swap at a rate you set rather than the rate of the day, then send to any Pryme username or to a Nigerian bank account. There is no fee to send to another Pryme account.
Eva is the assistant inside the Pryme app. She opens accounts, moves money, saves toward your goals, pays what is due and follows up what is owed to you — and asks you before anything moves.
Pryme Rails lets a platform issue a dedicated Naira account number to each of its own customers, collect into it and reconcile against it, over one API — the same rails the Pryme Business Account runs on.
Notes on money that does the work: what we are building, what the regulation actually says, and how we think about letting software act on money. Read the Ledger
What AI agents can do in bookkeeping, close, collections and compliance today, where a person must stay in charge, and how to judge a product.
How multi-currency business accounts work: local details vs SWIFT, payment rails, the real cost of FX, safeguarding vs deposit protection, and hedging.
How UK, US, Canadian and European firms pay Nigerian suppliers and get paid by Nigerian clients: FX, Form A and M, tax, compliance and payout routes.
What it really costs to send money to Nigeria from the UK, US, Canada and Europe: fees, exchange-rate margins, CBN naira rules, BVN, speed and scams.
What AI can and cannot do in day-to-day bookkeeping, how much time it saves on real numbers, and which jobs must stay with you or your accountant.
Why a SWIFT transfer can arrive late and short, how providers use local rails instead, and when SWIFT is still the right choice for a business.
Part of the guideOne account, every currency: a guide for cross-border businesses
A SWIFT payment travels from bank to bank, sometimes through one or more correspondent banks, and each can take a fee or add a check, so it can arrive later and for less than was sent. A payment over local rails is settled as a domestic transfer in the destination country, such as SEPA in the euro area or ACH in the US, usually by a provider that holds accounts at both ends. Local rails are typically faster, cheaper and arrive in full; SWIFT remains the route for currencies and destinations a provider does not cover locally, and for some very large payments.
When a business pays a supplier abroad, the money can take one of two kinds of route. The difference explains most of the variation in cost and speed that businesses see. For the full list of rails by country, see the table in our guide to multi-currency business accounts; this article explains how the two routes work and how to choose.
Swift is a messaging network, not a bank. When you send an international transfer, your bank sends a payment instruction to the recipient's bank. If the two banks do not hold accounts with each other, the money moves through correspondent banks that do, each debiting one account and crediting another. Every hop can add a charge, a compliance check and a cut-off time.
The network has become much faster. Swift reports that about 90% of payments reach the beneficiary's bank within an hour. The slower part is the last step: only about 43% are credited to the end customer's account within the hour, because of local operating hours, checks on incoming payments and back offices that do not run around the clock. The G20 target is for 75% of cross-border payments to reach the recipient within an hour by 2027.
The messages have also changed. In November 2025, Swift ended the period in which its old MT message formats could be used for cross-border payments, moving to the ISO 20022 standard, which carries richer, structured data about the payer, payee and purpose. That should mean fewer payments held for missing information, but only if the details you supply are complete.
A provider that offers local rails holds accounts inside each payment system it serves. To pay a supplier in Spain from pounds, it takes your pounds in the UK, converts them, and pays the supplier from its own euro account over SEPA. To your supplier it looks like a domestic euro payment. No correspondent banks are involved, so nothing is deducted along the way.
The same works in reverse for receiving money. Local account details, such as a euro IBAN or a US routing number, let foreign customers pay you domestically; our article on receiving US dollars as a UK business shows the effect on a single invoice.
There is a trade-off. With local rails, your money passes through the provider's own accounts for a short time, so you are relying on the provider rather than on a chain of banks. That makes two questions important: is the provider regulated in each country where it holds your money, and how is that money protected while it is in transit? Our article on safeguarding and FSCS protection explains the difference between the two main kinds of protection. Providers also set their own limits per payment and per day, which may be lower than the scheme limits.
| SWIFT | Local rails | |
|---|---|---|
| Route | Bank to bank, possibly via correspondents | Domestic payment in each country, via the provider's accounts |
| Deductions in transit | Possible, unless the sender pays all charges (OUR) | None on the domestic leg |
| Speed | Often within an hour to the receiving bank; crediting can take longer | Seconds to one business day, depending on the local system |
| Operating hours | Depends on each bank in the chain | Some local systems run 24/7, such as SEPA Instant; others follow business days |
| Currency coverage | Almost any currency | Only currencies and countries where the provider has local accounts |
| Size limits | Few scheme limits; bank limits apply | Scheme and provider limits; for example, Same Day ACH is capped at $1 million per payment until September 2027 |
A UK company must pay a Spanish supplier €8,000. To compare the routes alone, assume the same exchange rate applies in each case, so only the rail costs differ. The fees are illustrative.
| SWIFT, shared charges (SHA) | SWIFT, sender pays all (OUR) | Local rail via provider | |
|---|---|---|---|
| Fee to send | £25 | £40 | Included in the conversion fee |
| Deducted on the way | €20 | None | None |
| Supplier receives | €7,980 | €8,000 | €8,000 |
| Typical arrival | Same day to two days | Same day to two days | Within seconds by SEPA Instant, or by the next business day |
| Follow-up needed | Supplier chases the €20 shortfall | None | None |
The SHA payment looks cheaper at the point of sending, but the supplier's ledger now shows €20 unpaid, and someone must send a top-up or agree a write-off. The OUR payment solves that at a higher fee. The local route delivers the full amount without either cost. Add the conversion cost on top, which our article on hidden FX margins shows how to measure.
In practice, most businesses use both. Local rails handle the regular flow of supplier payments and customer receipts in the main currencies, and SWIFT handles the exceptions. The aim is to make SWIFT the exception rather than the default.
When you do use SWIFT, give complete, structured names and addresses, choose OUR if the full amount must arrive, and keep the payment's tracking reference so your bank can trace it. For euro payments specifically, our article on SEPA Instant for businesses explains what changed in 2025.
Pryme accounts hold four currencies with local details for each: a UK sort code and account number, a euro IBAN, a US account and routing number, and a Nigerian NUBAN, so customers in those markets can pay domestically. Before you plan supplier payments, check in the app which currencies and destinations you can send to and by which route. Bulk payouts validate account names before you approve.
Outside Nigeria, Pryme's services are provided through regulated partners. For how rails, conversion and protection fit together, see the multi-currency business account guide.
If the sender chose shared (SHA) or beneficiary (BEN) charges, correspondent or receiving banks may have deducted fees along the way. The amount sent was correct; the amount credited was lower. Ask the payer to use OUR charges, or give them local account details so the payment is domestic.
Usually, though less than it used to be. Most SWIFT payments reach the receiving bank within an hour, but crediting the end account can take longer. Instant local systems such as SEPA Instant credit the account within seconds, and standard local transfers usually within a business day.
They are the domestic payment systems of each country or currency area, such as Faster Payments in the UK, SEPA in the euro area and ACH in the US. Cross-border providers use them by holding accounts in each system, so an international payment becomes two domestic ones.
Yes. Each SWIFT payment carries a unique reference that your bank can use to trace where it is in the chain. Ask your bank for it if a payment is late, and give it to the recipient so their bank can look for it too.
It can be, provided the provider is regulated where it operates and keeps customer money protected. Ask which regulated firm holds your money and how it is protected before you use it.
This article is general information, not financial, legal or tax advice. Products described are provided under the terms on this site and are subject to regulation and eligibility.
How multi-currency business accounts work: local details vs SWIFT, payment rails, the real cost of FX, safeguarding vs deposit protection, and hedging.
Since October 2025, euro-area banks must send instant euro payments at no extra cost and check payee names. What it means for your business payments.
ACH is cheap and batched; a wire is fast, final and costs more. How each works, the 2026 limits and cut-offs, and which to use for which payment.
You can add the other type later — many of our customers hold both.
The business first, then you. Nothing is submitted until you review it.
Ideal customer profiles
Generated from your website by VerifiedLead.ai
Pick the ones that look right. Your Sales agent works these first, and you can change them at any time after opening.
We ask this because you have not given us a website. It helps us set the right limits from day one.
Which of these represents you?
Officers listed against this company on the UK register.
We have sent a six-digit code to your email address. Enter it below to confirm the address is yours.
Wrong address? Go back and change it — nothing is created until this step passes. We never ask for a code by phone or email; anyone who does is not us.
Last step. Each time you sign in we email you a six-digit code — we never send codes by SMS.